21886 This document is effective from 1 January 2027 to accompany PS1/26.
21887Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
21888 PRA2026/1
21890 S b = max {−K b ; min (∑ WS k ; K b )}
21891 k∈b
21892 where:
21894 WS k = calculated in accordance with 5.23;
21896 K b = calculated in accordance with 5.24(1);
21898 S c = the sum of the weighted sensitivities for all risk factors (k) within each bucket (c),
21899 floored by −K c and capped by K c in accordance with the following formula:
21901 S c = max {−K c ; min (∑ WS k ; K c )}
21902 k∈c
21903 where:
21905 WS k is calculated in accordance with 5.23;
21907 K c is calculated in accordance with 5.24(1) where K c is a different bucket from K b .
21909 Interest rate risk
21910 5.25 For the purposes of calculating the own funds requirement for interest rate risk in accordance
21911 with 5.14 to 5.24, a firm must:
21912 (1) set buckets for individual currencies;
21914 (2) set cross-bucket correlation (γ bc ) at 0.5 for all currency pairs (b, c);
21916 (3) set the delta risk factor for interest rate risk to either:
21918 (a) for the following currencies: USD, EUR, GBP, AUD, CAD, SEK or JPY, the absolute
21919 change of the inflation rate and of the risk-free yields for the following five tenors: one
21920 year, two years, five years, 10 years and 30 years; or
21922 (b) for all other currencies, the absolute change of the inflation rate and the parallel shift of
21923 the entire risk-free yield curve for a given currency;
21925 (4) for each interest rate delta risk factor measure the sensitivities to:
21927 (a) the risk-free yields by changing the risk-free yield for the relevant tenor for all curves
21928 in the relevant currency associated with the bucket by 0.0001 and dividing the
21929 resulting change in the aggregate CVA, and the value of eligible CVA hedges, by
21930 0.0001; and
21932 (b) the inflation rate by changing the inflation rate by 0.0001 and dividing the resulting
21933 change in the aggregate CVA, and the value of eligible CVA hedges, by 0.0001;
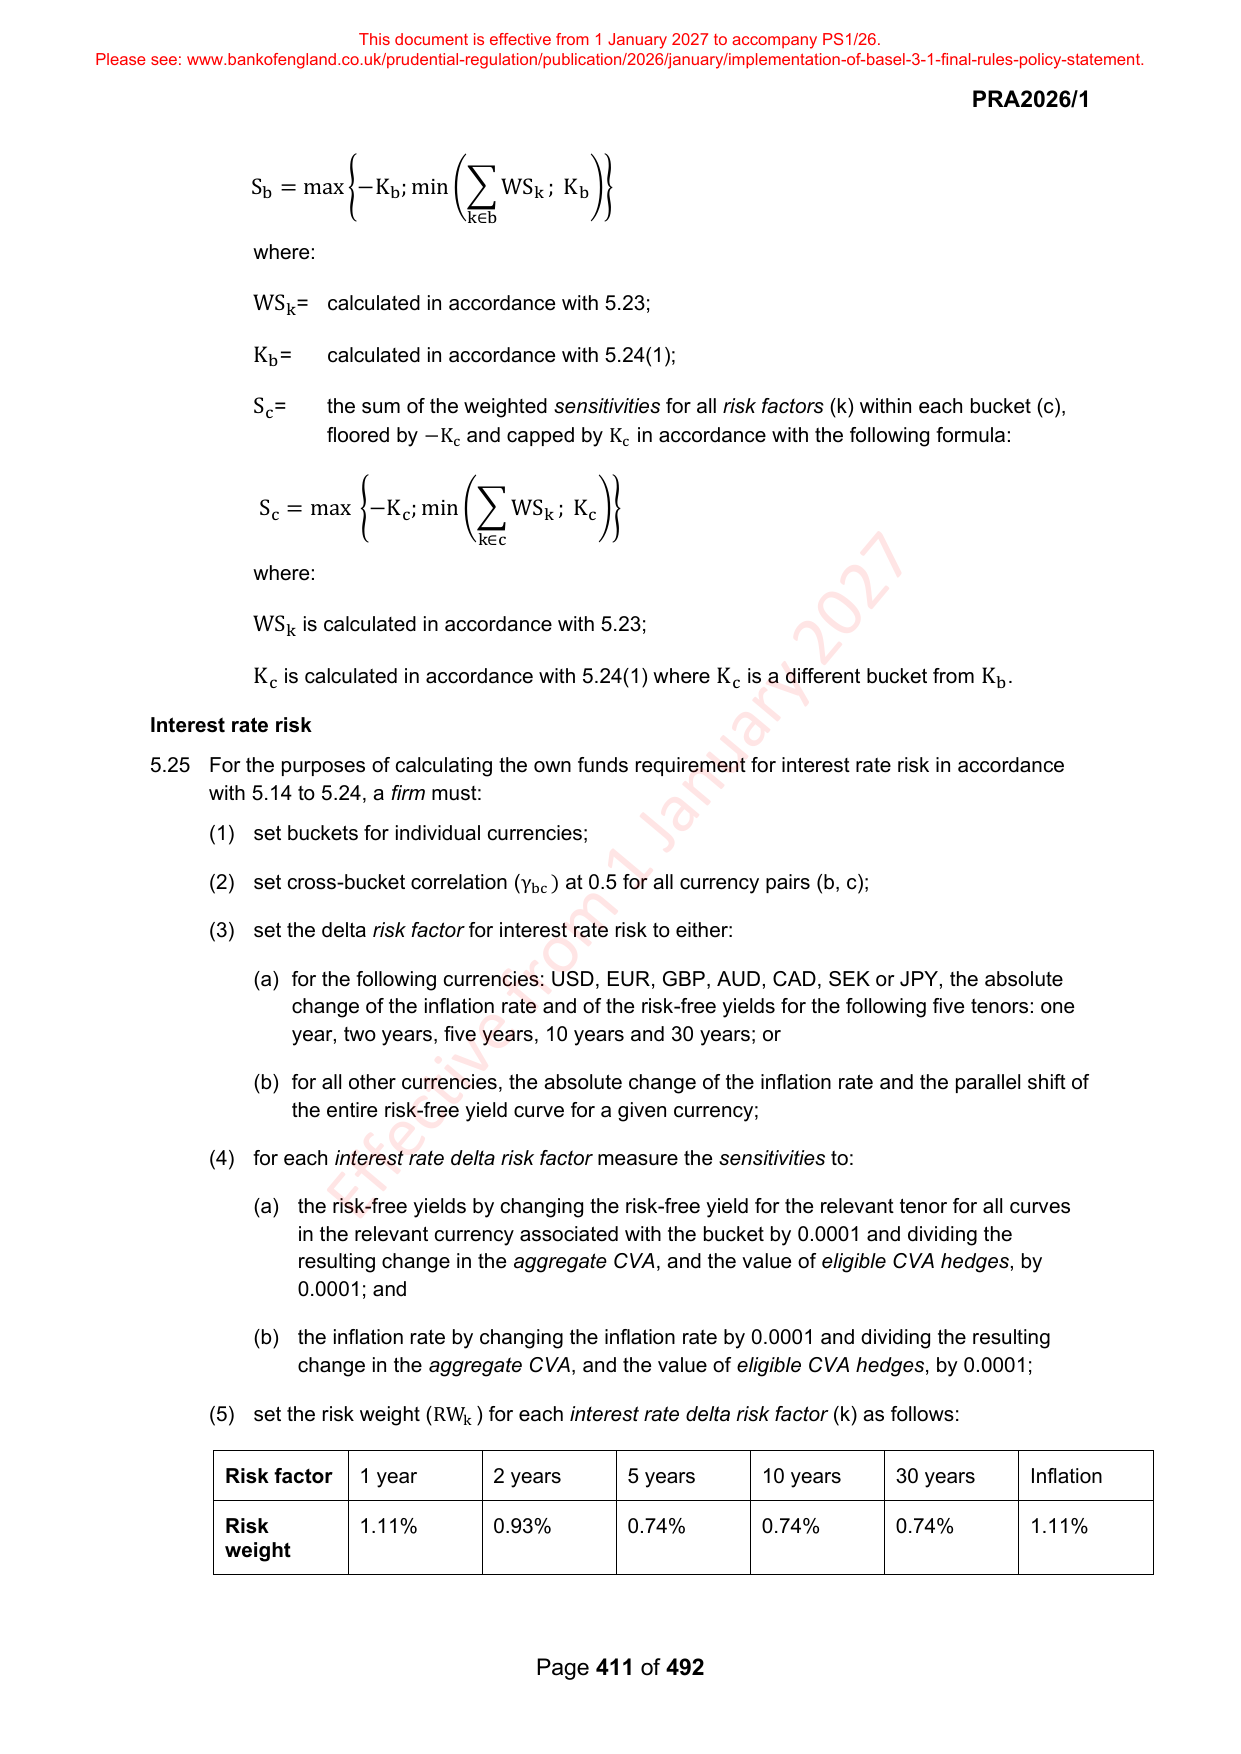
21935 (5) set the risk weight (RW k ) for each interest rate delta risk factor (k) as follows:
21937 Risk factor 1 year 2 years 5 years 10 years 30 years Inflation
21939 Risk 1.11% 0.93% 0.74% 0.74% 0.74% 1.11%
21940 weight
21942 Page 411 of 492