21823 This document is effective from 1 January 2027 to accompany PS1/26.
21824Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
21825 PRA2026/1
21827 Hdg
21828 s = the net sensitivity of the market value of all the eligible CVA hedges in the CVA
21829 k
21830 portfolio to risk factor (k).
21832 5.23 A firm must calculate the net weighted sensitivity of the CVA portfolio to each risk factor in
21833 accordance with the following formula:
21834 Hdg
21835 WS k = WS kCVA − WS k
21836 where:
21838 WS k = net weighted sensitivity of the CVA portfolio to risk factor (k);
21840 WS kCVA is calculated in accordance with 5.22; and
21842 Hdg
21843 WS is calculated in accordance with 5.22.
21844 k
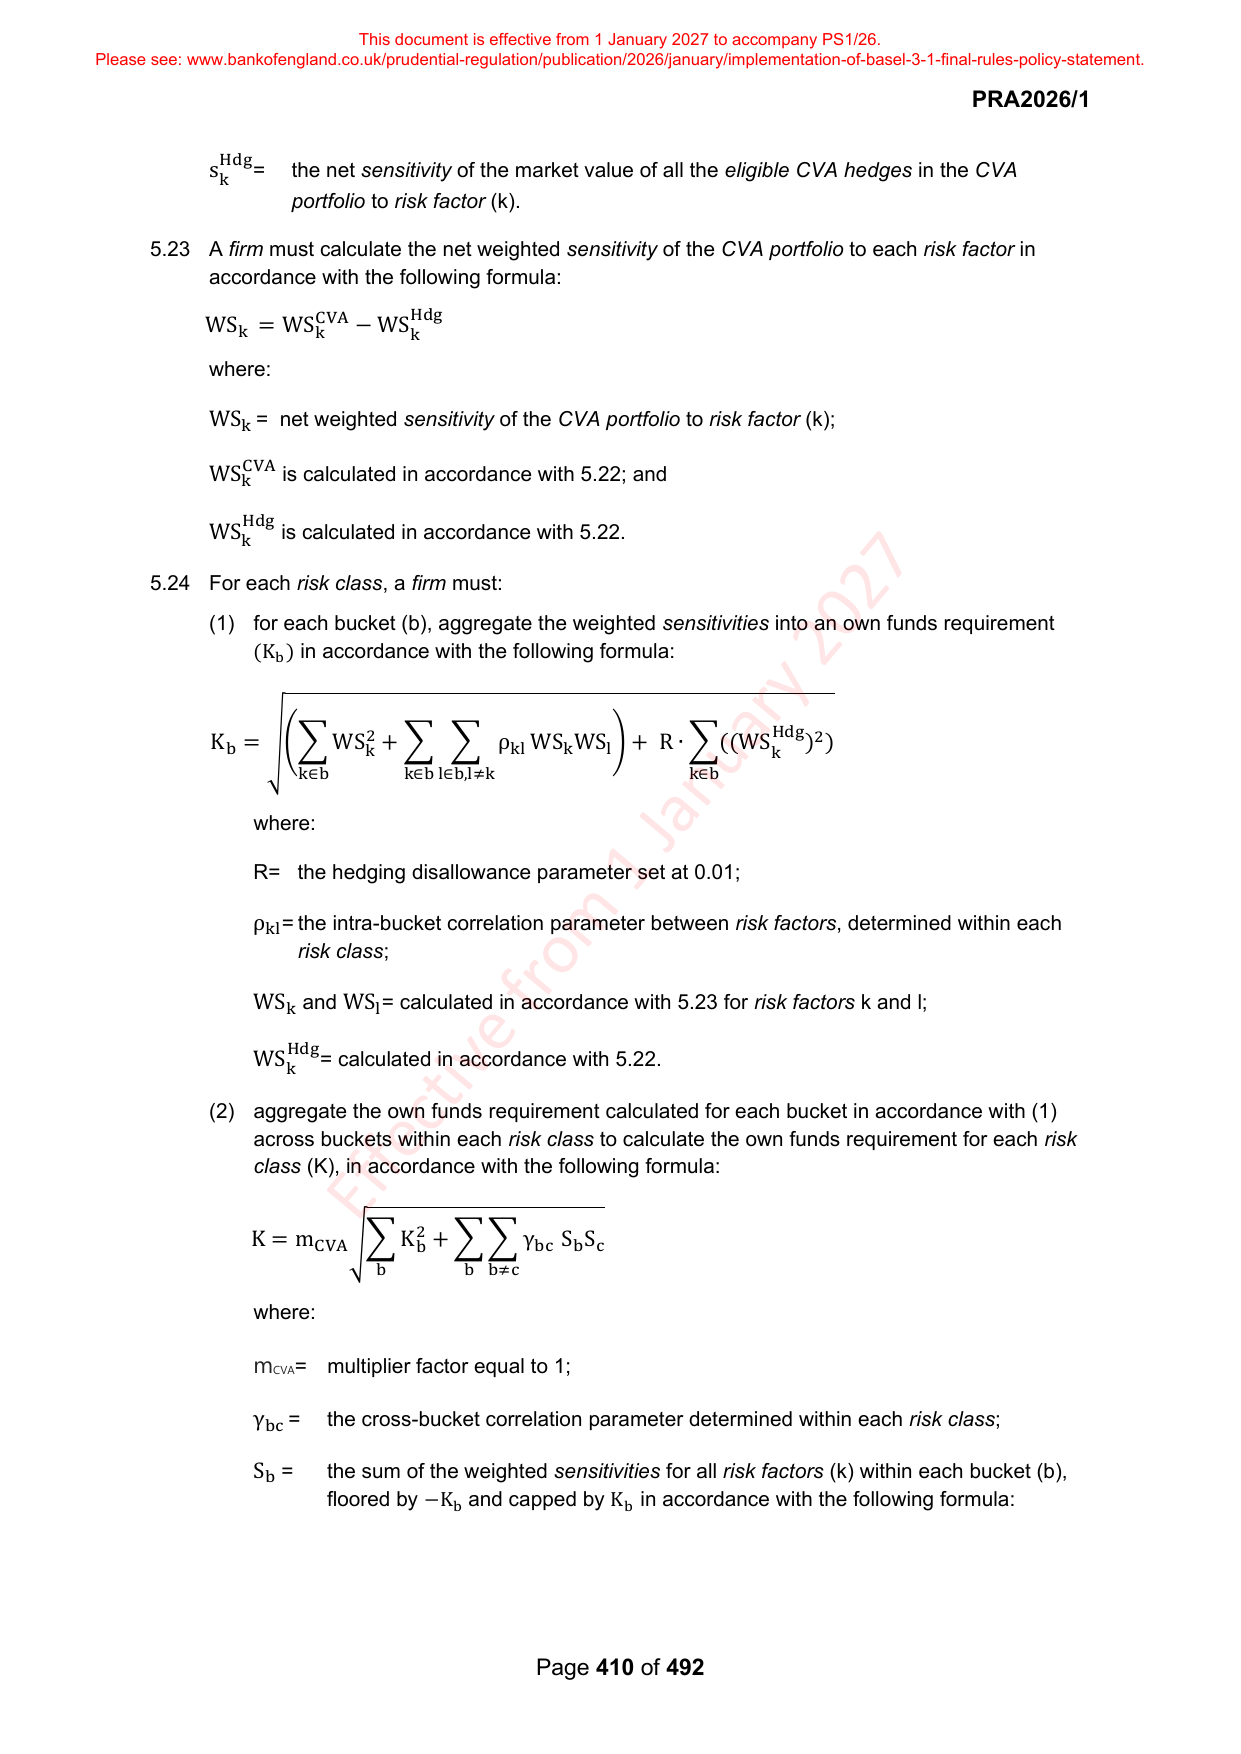
21846 5.24 For each risk class, a firm must:
21847 (1) for each bucket (b), aggregate the weighted sensitivities into an own funds requirement
21848 (K b ) in accordance with the following formula:
21850 Hdg 2
21851 K b = √(∑ WS k2 + ∑ ∑ ρ kl WS k WS l ) + R ∙ ∑((WS ) )
21852 k
21853 k∈b k∈b l∈b,l≠k k∈b
21855 where:
21857 R= the hedging disallowance parameter set at 0.01;
21859 ρ kl = the intra-bucket correlation parameter between risk factors, determined within each
21860 risk class;
21862 WS k and WS l = calculated in accordance with 5.23 for risk factors k and l;
21864 Hdg
21865 WS = calculated in accordance with 5.22.
21866 k
21868 (2) aggregate the own funds requirement calculated for each bucket in accordance with (1)
21869 across buckets within each risk class to calculate the own funds requirement for each risk
21870 class (K), in accordance with the following formula:
21872 2
21873 K = m CVA √∑ K b + ∑ ∑ γ bc S b S c
21874 b b b≠c
21876 where:
21878 m CVA = multiplier factor equal to 1;
21880 γ bc = the cross-bucket correlation parameter determined within each risk class;
21882 S b = the sum of the weighted sensitivities for all risk factors (k) within each bucket (b),
21883 floored by −K b and capped by K b in accordance with the following formula:
21885 Page 410 of 492