21943 This document is effective from 1 January 2027 to accompany PS1/26.
21944Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
21945 PRA2026/1
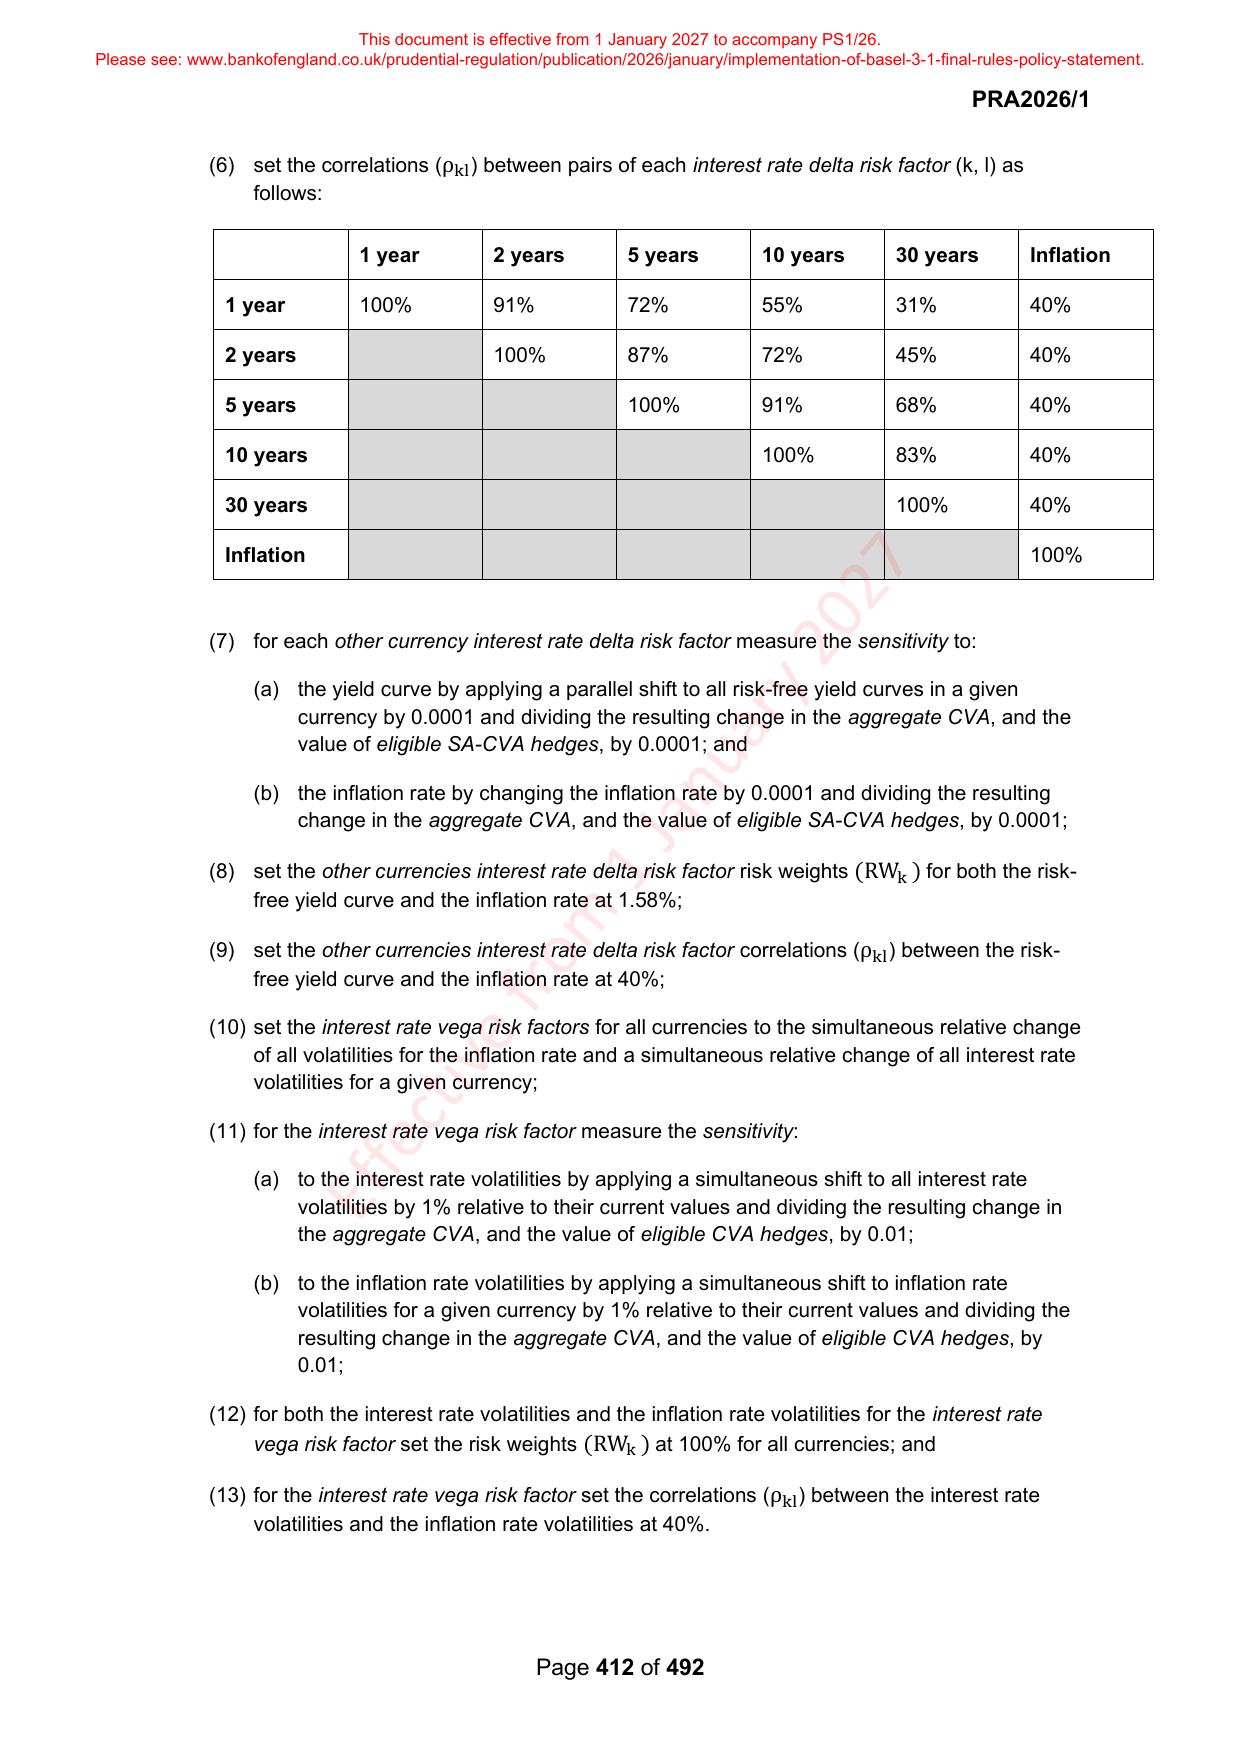
21947 (6) set the correlations ( ρ kl ) between pairs of each interest rate delta risk factor (k, l) as
21948 follows:
21950 1 year 2 years 5 years 10 years 30 years Inflation
21952 1 year 100% 91% 72% 55% 31% 40%
21954 2 years 100% 87% 72% 45% 40%
21956 5 years 100% 91% 68% 40%
21958 10 years 100% 83% 40%
21960 30 years 100% 40%
21962 Inflation 100%
21964 (7) for each other currency interest rate delta risk factor measure the sensitivity to:
21966 (a) the yield curve by applying a parallel shift to all risk-free yield curves in a given
21967 currency by 0.0001 and dividing the resulting change in the aggregate CVA, and the
21968 value of eligible SA-CVA hedges, by 0.0001; and
21970 (b) the inflation rate by changing the inflation rate by 0.0001 and dividing the resulting
21971 change in the aggregate CVA, and the value of eligible SA-CVA hedges, by 0.0001;
21973 (8) set the other currencies interest rate delta risk factor risk weights (RW k ) for both the risk-
21974 free yield curve and the inflation rate at 1.58%;
21976 (9) set the other currencies interest rate delta risk factor correlations ( ρ kl ) between the risk-
21977 free yield curve and the inflation rate at 40%;
21979 (10) set the interest rate vega risk factors for all currencies to the simultaneous relative change
21980 of all volatilities for the inflation rate and a simultaneous relative change of all interest rate
21981 volatilities for a given currency;
21983 (11) for the interest rate vega risk factor measure the sensitivity:
21985 (a) to the interest rate volatilities by applying a simultaneous shift to all interest rate
21986 volatilities by 1% relative to their current values and dividing the resulting change in
21987 the aggregate CVA, and the value of eligible CVA hedges, by 0.01;
21989 (b) to the inflation rate volatilities by applying a simultaneous shift to inflation rate
21990 volatilities for a given currency by 1% relative to their current values and dividing the
21991 resulting change in the aggregate CVA, and the value of eligible CVA hedges, by
21992 0.01;
21994 (12) for both the interest rate volatilities and the inflation rate volatilities for the interest rate
21995 vega risk factor set the risk weights (RW k ) at 100% for all currencies; and
21997 (13) for the interest rate vega risk factor set the correlations ( ρ kl ) between the interest rate
21998 volatilities and the inflation rate volatilities at 40%.
22000 Page 412 of 492