21761 This document is effective from 1 January 2027 to accompany PS1/26.
21762Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
21763 PRA2026/1
21765 (2) foreign exchange risk;
21767 (3) reference credit spread risk;
21769 (4) equity risk;
21771 (5) commodity risk.
21773 5.18 A firm may use smaller values of risk factor shifts than the shifts specified in 5.25 to 5.30 for
21774 each risk class if doing so is consistent with its internal risk management calculations.
21775 5.19 A firm must calculate sensitivities for vega risk:
21776 (1) whether or not the CVA portfolio includes options; and
21778 (2) by applying the relevant volatility shift to the risk class as required by 5.25 to 5.30 to the
21779 volatilities used for generating risk factor paths and pricing options.
21781 5.20 If an eligible SA-CVA hedge is an index instrument, a firm must:
21782 (1) calculate its sensitivities to all risk factors upon which the value of the index depends; and
21784 (2) calculate the index sensitivity to the risk factor by applying the shift of the risk factor to all
21785 index constituents that depend on the risk factor and recalculating the changed value of
21786 the index.
21788 5.21 For the purpose of calculating the delta and vega sensitivities for counterparty credit spread
21789 risk, reference credit spread risk and equity risk in accordance with 5.25 to 5.30, a firm may use
21790 additional risk factors that correspond to qualified index instruments, provided that the firm:
21791 (1) calculates delta and vega sensitivities to a risk factor that corresponds to a qualified index
21792 as a single sensitivity to the underlying qualified index;
21794 (2) where 75% or more of the constituents of a qualified index are mapped to the same sector,
21795 maps the qualified index to that same sector; and
21797 (3) where less than 75% of the constituents of a qualified index are mapped to the same
21798 sector, maps the sensitivity to the applicable qualified index bucket.
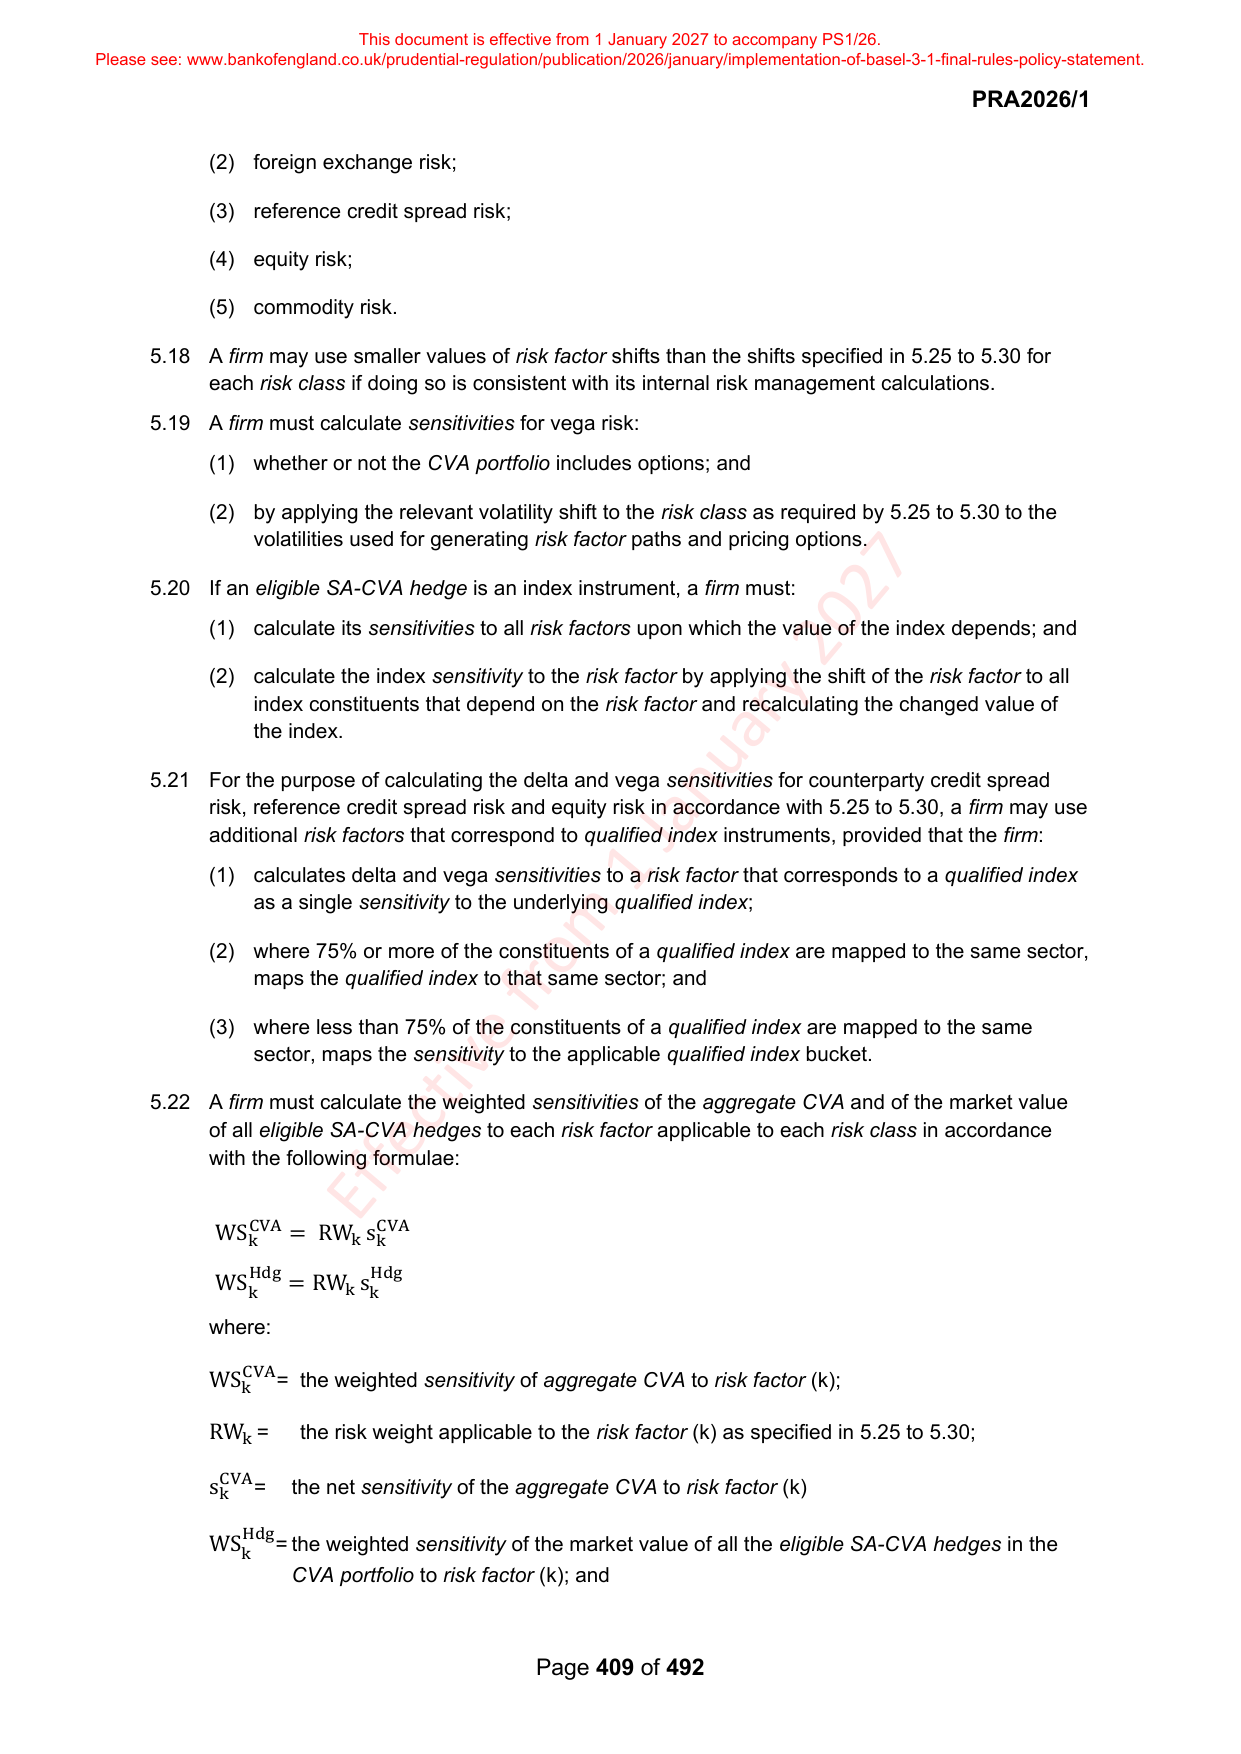
21800 5.22 A firm must calculate the weighted sensitivities of the aggregate CVA and of the market value
21801 of all eligible SA-CVA hedges to each risk factor applicable to each risk class in accordance
21802 with the following formulae:
21804 WS kCVA = RW k s kCVA
21805 Hdg Hdg
21806 WS = RW k s
21807 k k
21809 where:
21811 WS kCVA = the weighted sensitivity of aggregate CVA to risk factor (k);
21813 RW k = the risk weight applicable to the risk factor (k) as specified in 5.25 to 5.30;
21815 s kCVA = the net sensitivity of the aggregate CVA to risk factor (k)
21817 Hdg
21818 WS = the weighted sensitivity of the market value of all the eligible SA-CVA hedges in the
21819 k
21820 CVA portfolio to risk factor (k); and
21822 Page 409 of 492