12802 This document is effective from 1 January 2027 to accompany PS1/26.
12803Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
12804 PRA2026/1
12806 2 20
12808 3 40
12810 4 60
12812 5 120
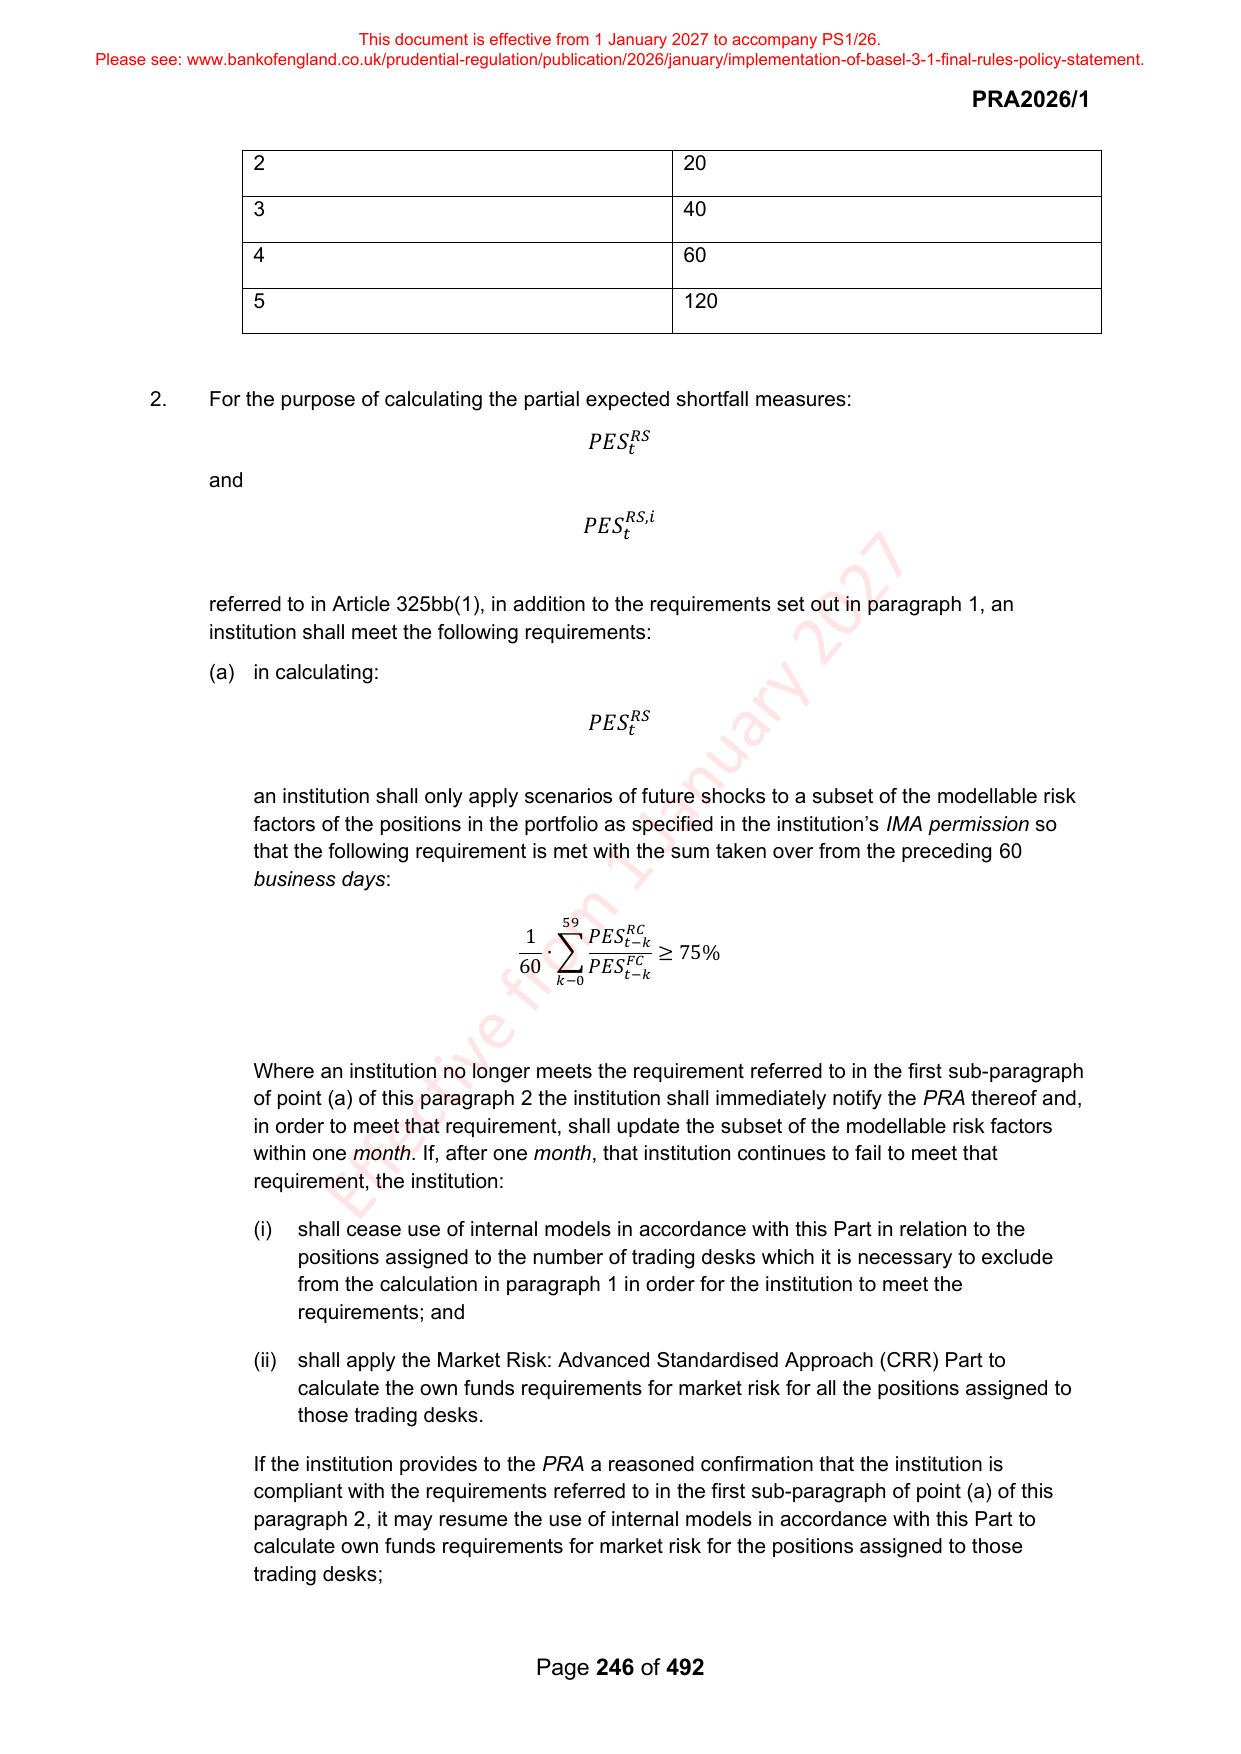
12814 2. For the purpose of calculating the partial expected shortfall measures:
12816 𝑃𝐸𝑆 𝑡𝑅𝑆
12817 and
12819 𝑃𝐸𝑆 𝑡𝑅𝑆,𝑖
12821 referred to in Article 325bb(1), in addition to the requirements set out in paragraph 1, an
12822 institution shall meet the following requirements:
12823 (a) in calculating:
12825 𝑃𝐸𝑆 𝑡𝑅𝑆
12827 an institution shall only apply scenarios of future shocks to a subset of the modellable risk
12828 factors of the positions in the portfolio as specified in the institution’s IMA permission so
12829 that the following requirement is met with the sum taken over from the preceding 60
12830 business days:
12832 59
12833 𝑅𝐶
12834 1 𝑃𝐸𝑆 𝑡−𝑘
12835 ∙∑ ≥ 75%
12836 60 𝐹𝐶
12837 𝑃𝐸𝑆 𝑡−𝑘
12838 𝑘−0
12840 Where an institution no longer meets the requirement referred to in the first sub-paragraph
12841 of point (a) of this paragraph 2 the institution shall immediately notify the PRA thereof and,
12842 in order to meet that requirement, shall update the subset of the modellable risk factors
12843 within one month. If, after one month, that institution continues to fail to meet that
12844 requirement, the institution:
12846 (i) shall cease use of internal models in accordance with this Part in relation to the
12847 positions assigned to the number of trading desks which it is necessary to exclude
12848 from the calculation in paragraph 1 in order for the institution to meet the
12849 requirements; and
12851 (ii) shall apply the Market Risk: Advanced Standardised Approach (CRR) Part to
12852 calculate the own funds requirements for market risk for all the positions assigned to
12853 those trading desks.
12855 If the institution provides to the PRA a reasoned confirmation that the institution is
12856 compliant with the requirements referred to in the first sub-paragraph of point (a) of this
12857 paragraph 2, it may resume the use of internal models in accordance with this Part to
12858 calculate own funds requirements for market risk for the positions assigned to those
12859 trading desks;
12861 Page 246 of 492