12737 This document is effective from 1 January 2027 to accompany PS1/26.
12738Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
12739 PRA2026/1
12741 𝑃𝐸𝑆 𝑡𝑅𝑆,𝑖
12743 𝑃𝐸𝑆 𝑡𝑅𝐶,𝑖
12745 and
12747 𝑃𝐸𝑆 𝑡𝐹𝐶,𝑖
12749 from weekly to daily if required by the PRA.
12751 [Note: This rule corresponds to Article 325bb of CRR as it applied immediately before revocation by
12752 the Treasury]
12754 Article 325bc PARTIAL EXPECTED SHORTFALL CALCULATIONS
12756 1. An institution shall calculate all the partial expected shortfall measures referred to in
12757 Article 325bb(1) as follows:
12758 (a) daily calculations of the partial expected shortfall measures;
12760 (b) at 97.5th percentile, one tailed confidence interval; and
12762 (c) for a given portfolio of trading book positions and non-trading book positions that are
12763 subject to foreign exchange or commodity risk, an institution shall calculate the partial
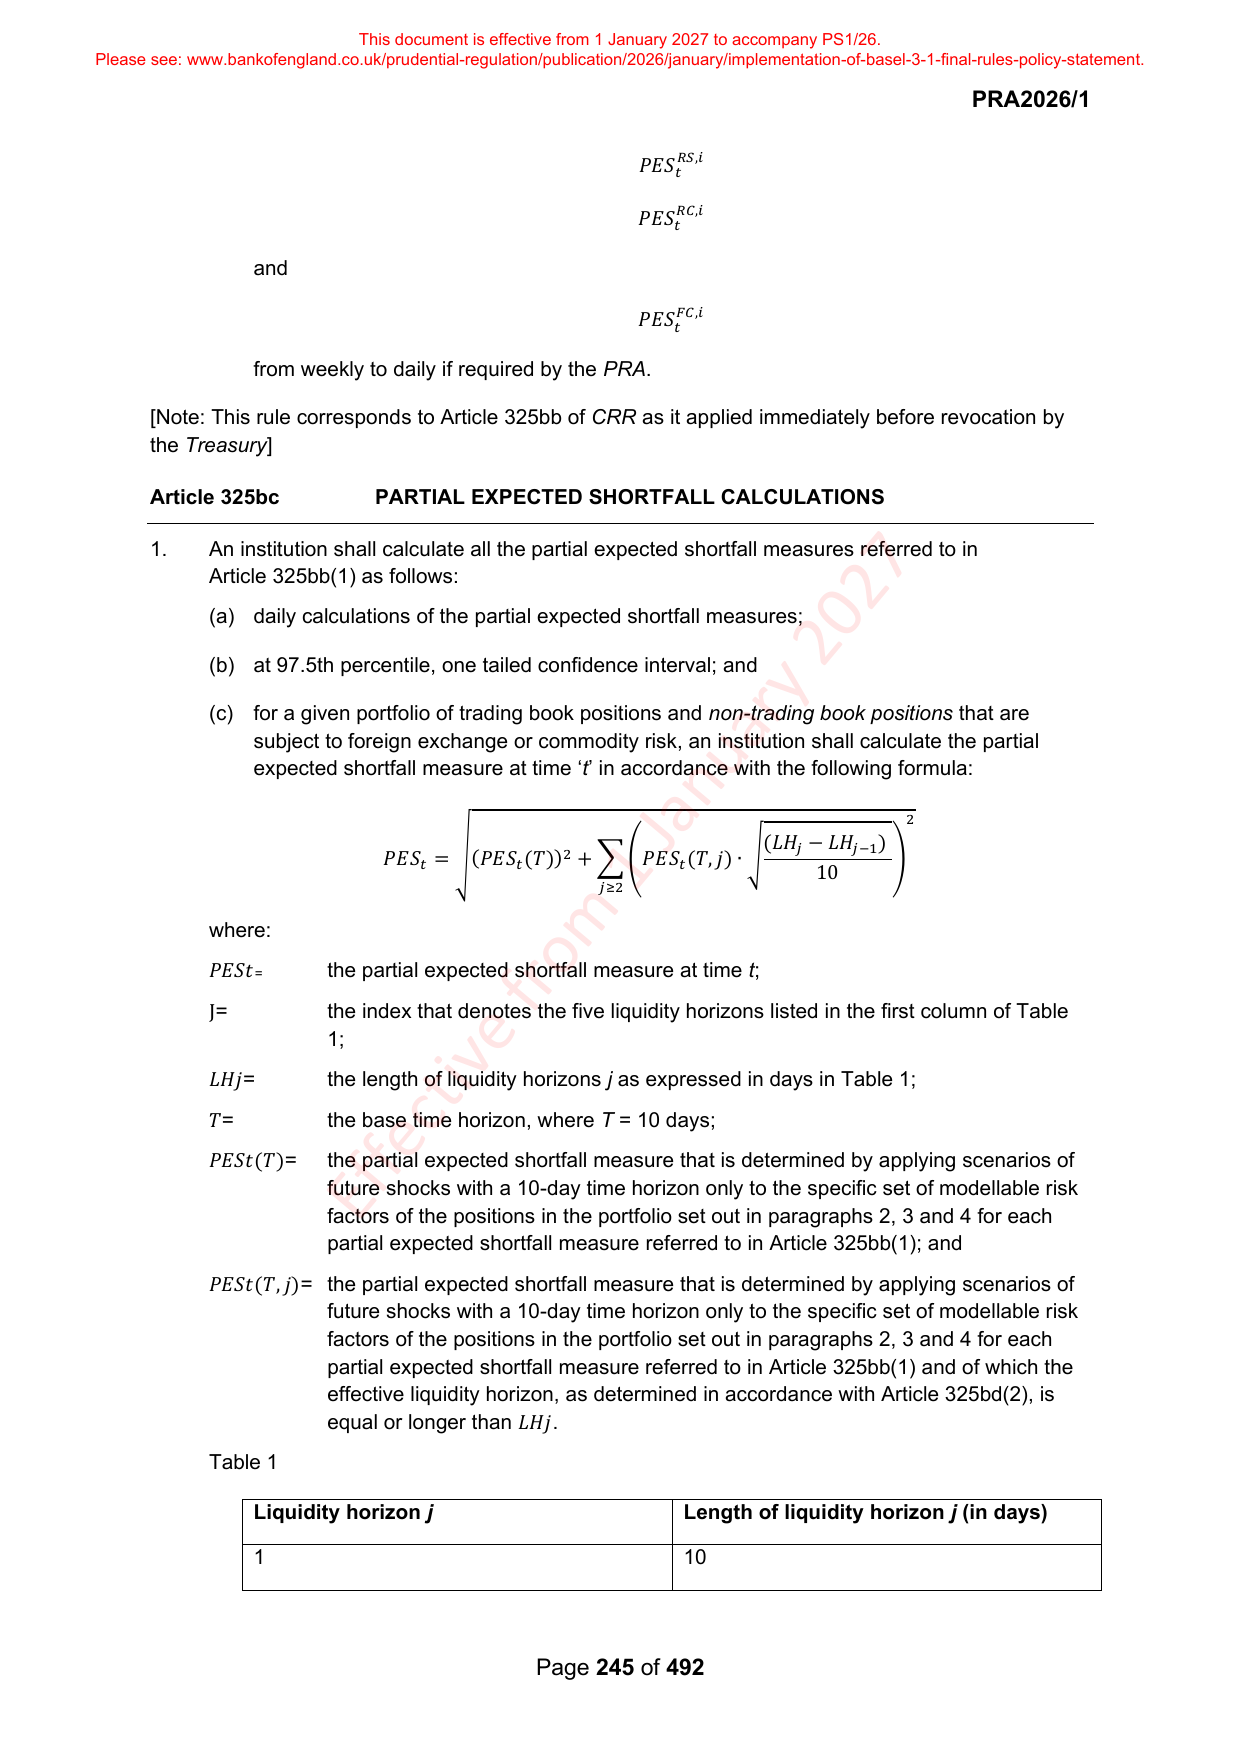
12764 expected shortfall measure at time ‘t’ in accordance with the following formula:
12766 2
12767 (𝐿𝐻 𝑗 − 𝐿𝐻 𝑗−1 )
12768 𝑃𝐸𝑆 = √(𝑃𝐸𝑆 (𝑇)) 2 + ∑ (𝑃𝐸𝑆 (𝑇, 𝑗) ∙ √ )
12769 𝑡 𝑡 𝑡
12770 10
12771 𝑗≥2
12773 where:
12775 𝑃𝐸𝑆𝑡 = the partial expected shortfall measure at time t;
12777 J= the index that denotes the five liquidity horizons listed in the first column of Table
12778 1;
12780 𝐿𝐻𝑗= the length of liquidity horizons j as expressed in days in Table 1;
12782 𝑇= the base time horizon, where T = 10 days;
12784 𝑃𝐸𝑆𝑡(𝑇)= the partial expected shortfall measure that is determined by applying scenarios of
12785 future shocks with a 10-day time horizon only to the specific set of modellable risk
12786 factors of the positions in the portfolio set out in paragraphs 2, 3 and 4 for each
12787 partial expected shortfall measure referred to in Article 325bb(1); and
12789 𝑃𝐸𝑆𝑡(𝑇, 𝑗)= the partial expected shortfall measure that is determined by applying scenarios of
12790 future shocks with a 10-day time horizon only to the specific set of modellable risk
12791 factors of the positions in the portfolio set out in paragraphs 2, 3 and 4 for each
12792 partial expected shortfall measure referred to in Article 325bb(1) and of which the
12793 effective liquidity horizon, as determined in accordance with Article 325bd(2), is
12794 equal or longer than 𝐿𝐻𝑗.
12795 Table 1
12797 Liquidity horizon j Length of liquidity horizon j (in days)
12799 1 10
12801 Page 245 of 492