12679 This document is effective from 1 January 2027 to accompany PS1/26.
12680Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
12681 PRA2026/1
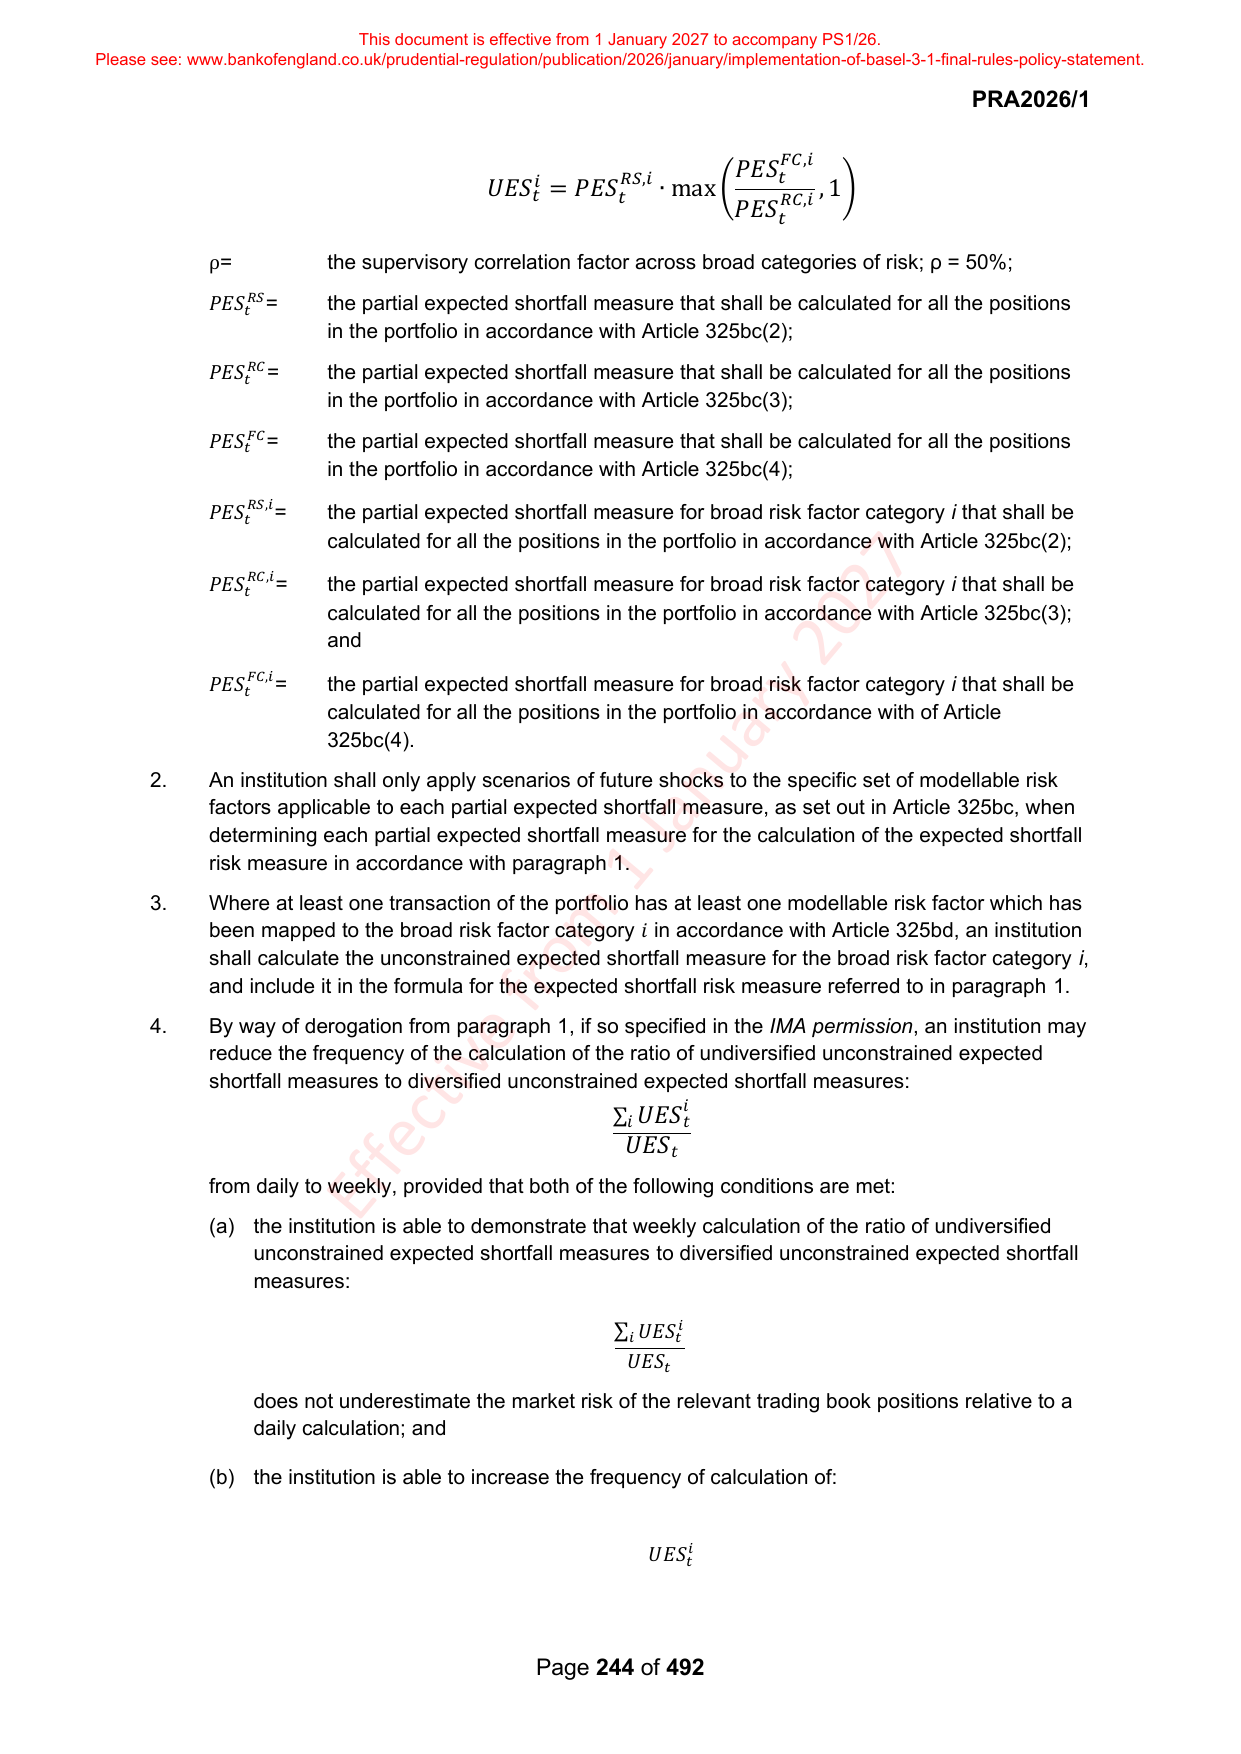
12683 𝑖 𝑅𝑆,𝑖 𝑃𝐸𝑆 𝑡𝐹𝐶,𝑖
12684 𝑈𝐸𝑆 𝑡 = 𝑃𝐸𝑆 𝑡 ∙ max ( , 1)
12685 𝑃𝐸𝑆 𝑡𝑅𝐶,𝑖
12687 ρ= the supervisory correlation factor across broad categories of risk; ρ = 50%;
12689 𝑃𝐸𝑆 𝑡𝑅𝑆 = the partial expected shortfall measure that shall be calculated for all the positions
12690 in the portfolio in accordance with Article 325bc(2);
12692 𝑃𝐸𝑆 𝑡𝑅𝐶 = the partial expected shortfall measure that shall be calculated for all the positions
12693 in the portfolio in accordance with Article 325bc(3);
12695 𝑃𝐸𝑆 𝑡𝐹𝐶 = the partial expected shortfall measure that shall be calculated for all the positions
12696 in the portfolio in accordance with Article 325bc(4);
12698 𝑃𝐸𝑆 𝑡𝑅𝑆,𝑖 = the partial expected shortfall measure for broad risk factor category i that shall be
12699 calculated for all the positions in the portfolio in accordance with Article 325bc(2);
12701 𝑃𝐸𝑆 𝑡𝑅𝐶,𝑖 = the partial expected shortfall measure for broad risk factor category i that shall be
12702 calculated for all the positions in the portfolio in accordance with Article 325bc(3);
12703 and
12705 𝑃𝐸𝑆 𝑡𝐹𝐶,𝑖 = the partial expected shortfall measure for broad risk factor category i that shall be
12706 calculated for all the positions in the portfolio in accordance with of Article
12707 325bc(4).
12708 2. An institution shall only apply scenarios of future shocks to the specific set of modellable risk
12709 factors applicable to each partial expected shortfall measure, as set out in Article 325bc, when
12710 determining each partial expected shortfall measure for the calculation of the expected shortfall
12711 risk measure in accordance with paragraph 1.
12712 3. Where at least one transaction of the portfolio has at least one modellable risk factor which has
12713 been mapped to the broad risk factor category 𝑖 in accordance with Article 325bd, an institution
12714 shall calculate the unconstrained expected shortfall measure for the broad risk factor category i,
12715 and include it in the formula for the expected shortfall risk measure referred to in paragraph 1.
12716 4. By way of derogation from paragraph 1, if so specified in the IMA permission, an institution may
12717 reduce the frequency of the calculation of the ratio of undiversified unconstrained expected
12718 shortfall measures to diversified unconstrained expected shortfall measures:
12719 𝑖
12720 ∑ 𝑖 𝑈𝐸𝑆 𝑡
12721 𝑈𝐸𝑆 𝑡
12722 from daily to weekly, provided that both of the following conditions are met:
12723 (a) the institution is able to demonstrate that weekly calculation of the ratio of undiversified
12724 unconstrained expected shortfall measures to diversified unconstrained expected shortfall
12725 measures:
12727 ∑ 𝑖 𝑈𝐸𝑆 𝑡𝑖
12728 𝑈𝐸𝑆 𝑡
12729 does not underestimate the market risk of the relevant trading book positions relative to a
12730 daily calculation; and
12732 (b) the institution is able to increase the frequency of calculation of:
12734 𝑈𝐸𝑆 𝑡𝑖
12736 Page 244 of 492