10894 This document is effective from 1 January 2027 to accompany PS1/26.
10895Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
10896 PRA2026/1
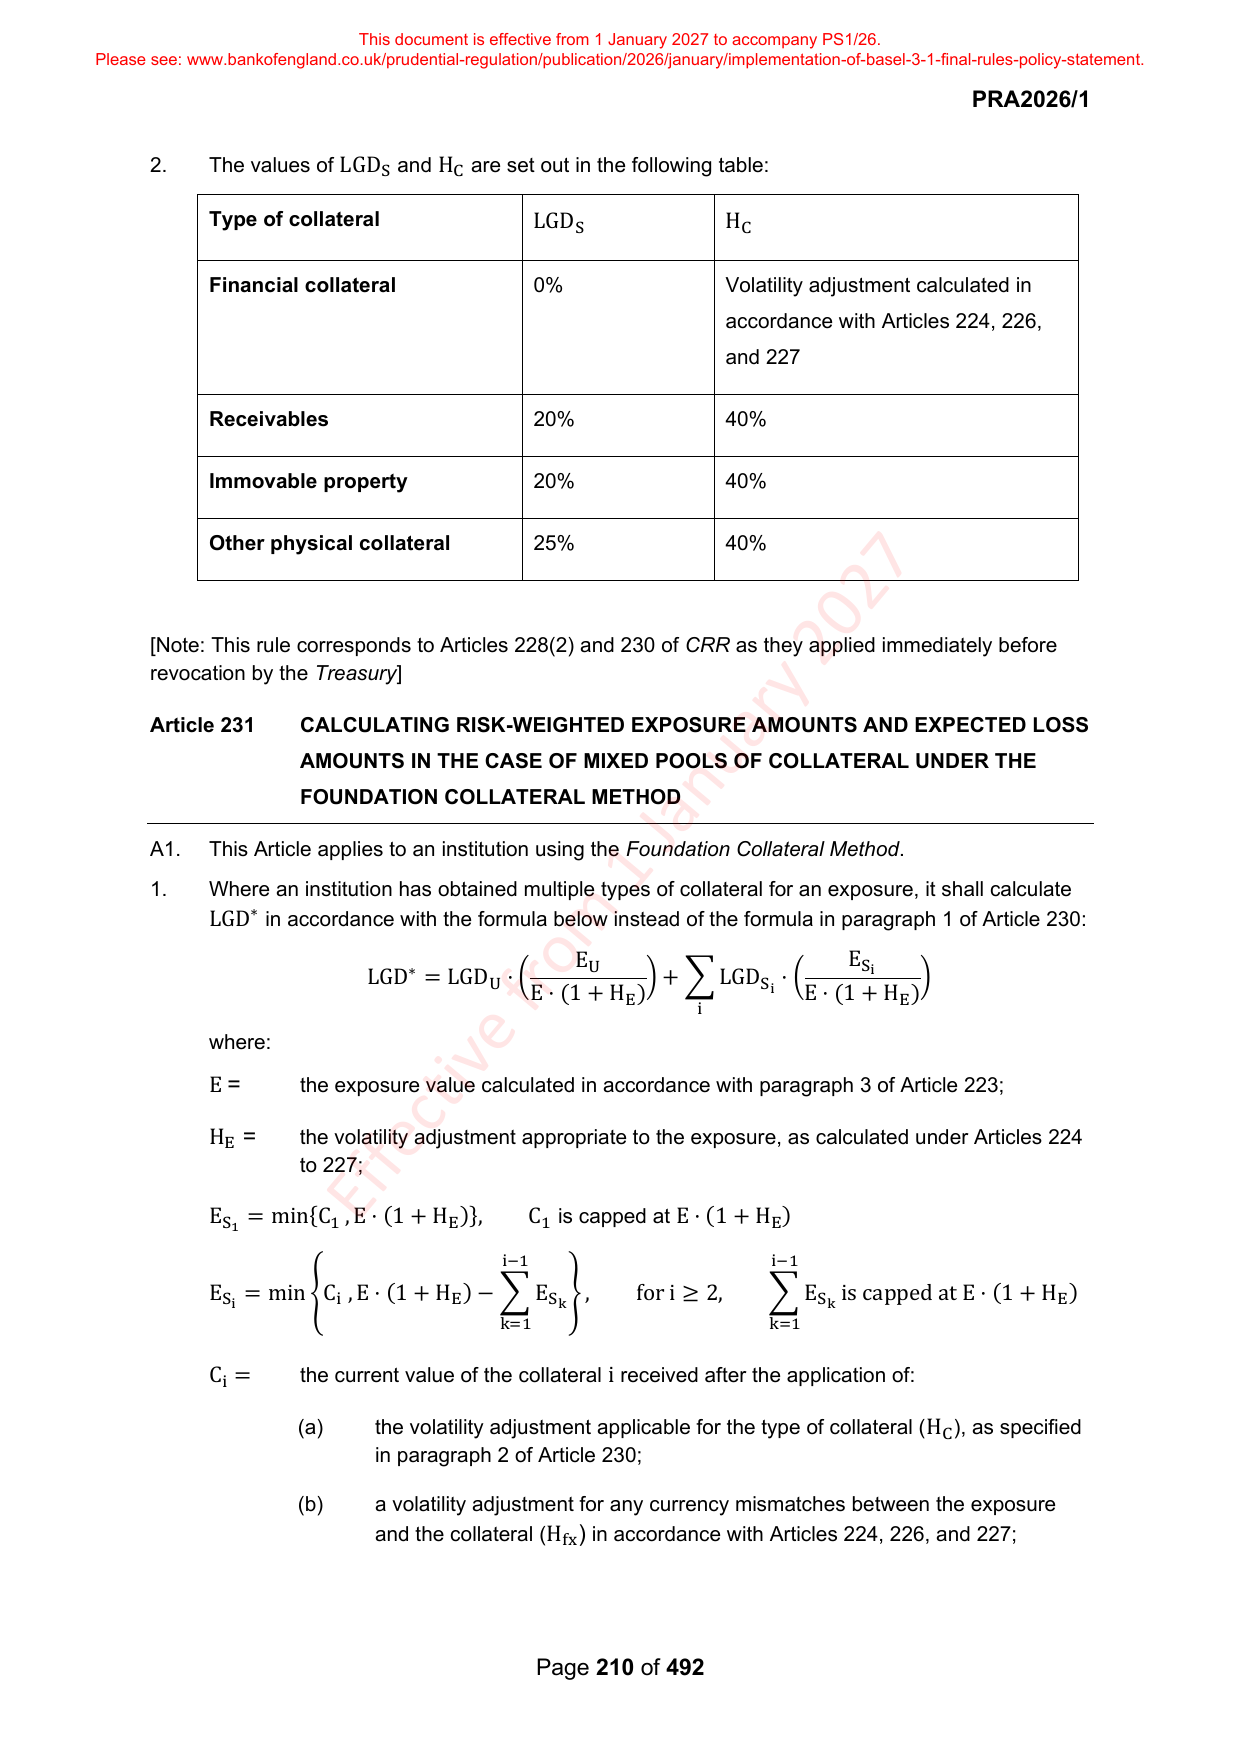
10898 2. The values of LGD S and H C are set out in the following table:
10900 Type of collateral LGD H
10901 S C
10903 Financial collateral 0% Volatility adjustment calculated in
10904 accordance with Articles 224, 226,
10905 and 227
10907 Receivables 20% 40%
10909 Immovable property 20% 40%
10911 Other physical collateral 25% 40%
10913 [Note: This rule corresponds to Articles 228(2) and 230 of CRR as they applied immediately before
10914 revocation by the Treasury]
10916 Article 231 CALCULATING RISK-WEIGHTED EXPOSURE AMOUNTS AND EXPECTED LOSS
10917 AMOUNTS IN THE CASE OF MIXED POOLS OF COLLATERAL UNDER THE
10918 FOUNDATION COLLATERAL METHOD
10920 A1. This Article applies to an institution using the Foundation Collateral Method.
10921 1. Where an institution has obtained multiple types of collateral for an exposure, it shall calculate
10922 ∗ in accordance with the formula below instead of the formula in paragraph 1 of Article 230:
10923 LGD
10924 E U E S
10925 ∗ i
10926 LGD = LGD U · ( ) + ∑ LGD S · ( )
10927 E · (1 + H ) i E · (1 + H )
10928 E E
10929 i
10930 where:
10932 E = the exposure value calculated in accordance with paragraph 3 of Article 223;
10934 H E = the volatility adjustment appropriate to the exposure, as calculated under Articles 224
10935 to 227;
10937 E S = min{C 1 , E · (1 + H E )}, C 1 is capped at E · (1 + H E )
10938 1
10940 i−1 i−1
10941 E S = min {C i , E · (1 + H E ) − ∑ E S } , for i ≥ 2, ∑ E S is capped at E · (1 + H E )
10942 i k k
10943 k=1 k=1
10945 C i = the current value of the collateral i received after the application of:
10947 (a) the volatility adjustment applicable for the type of collateral ( H C ), as specified
10948 in paragraph 2 of Article 230;
10950 (b) a volatility adjustment for any currency mismatches between the exposure
10951 and the collateral ( H fx ) in accordance with Articles 224, 226, and 227;
10953 Page 210 of 492