10954 This document is effective from 1 January 2027 to accompany PS1/26.
10955Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
10956 PRA2026/1
10958 (c) an adjustment for any maturity mismatches calculated in accordance with
10959 Articles 237 to 239.
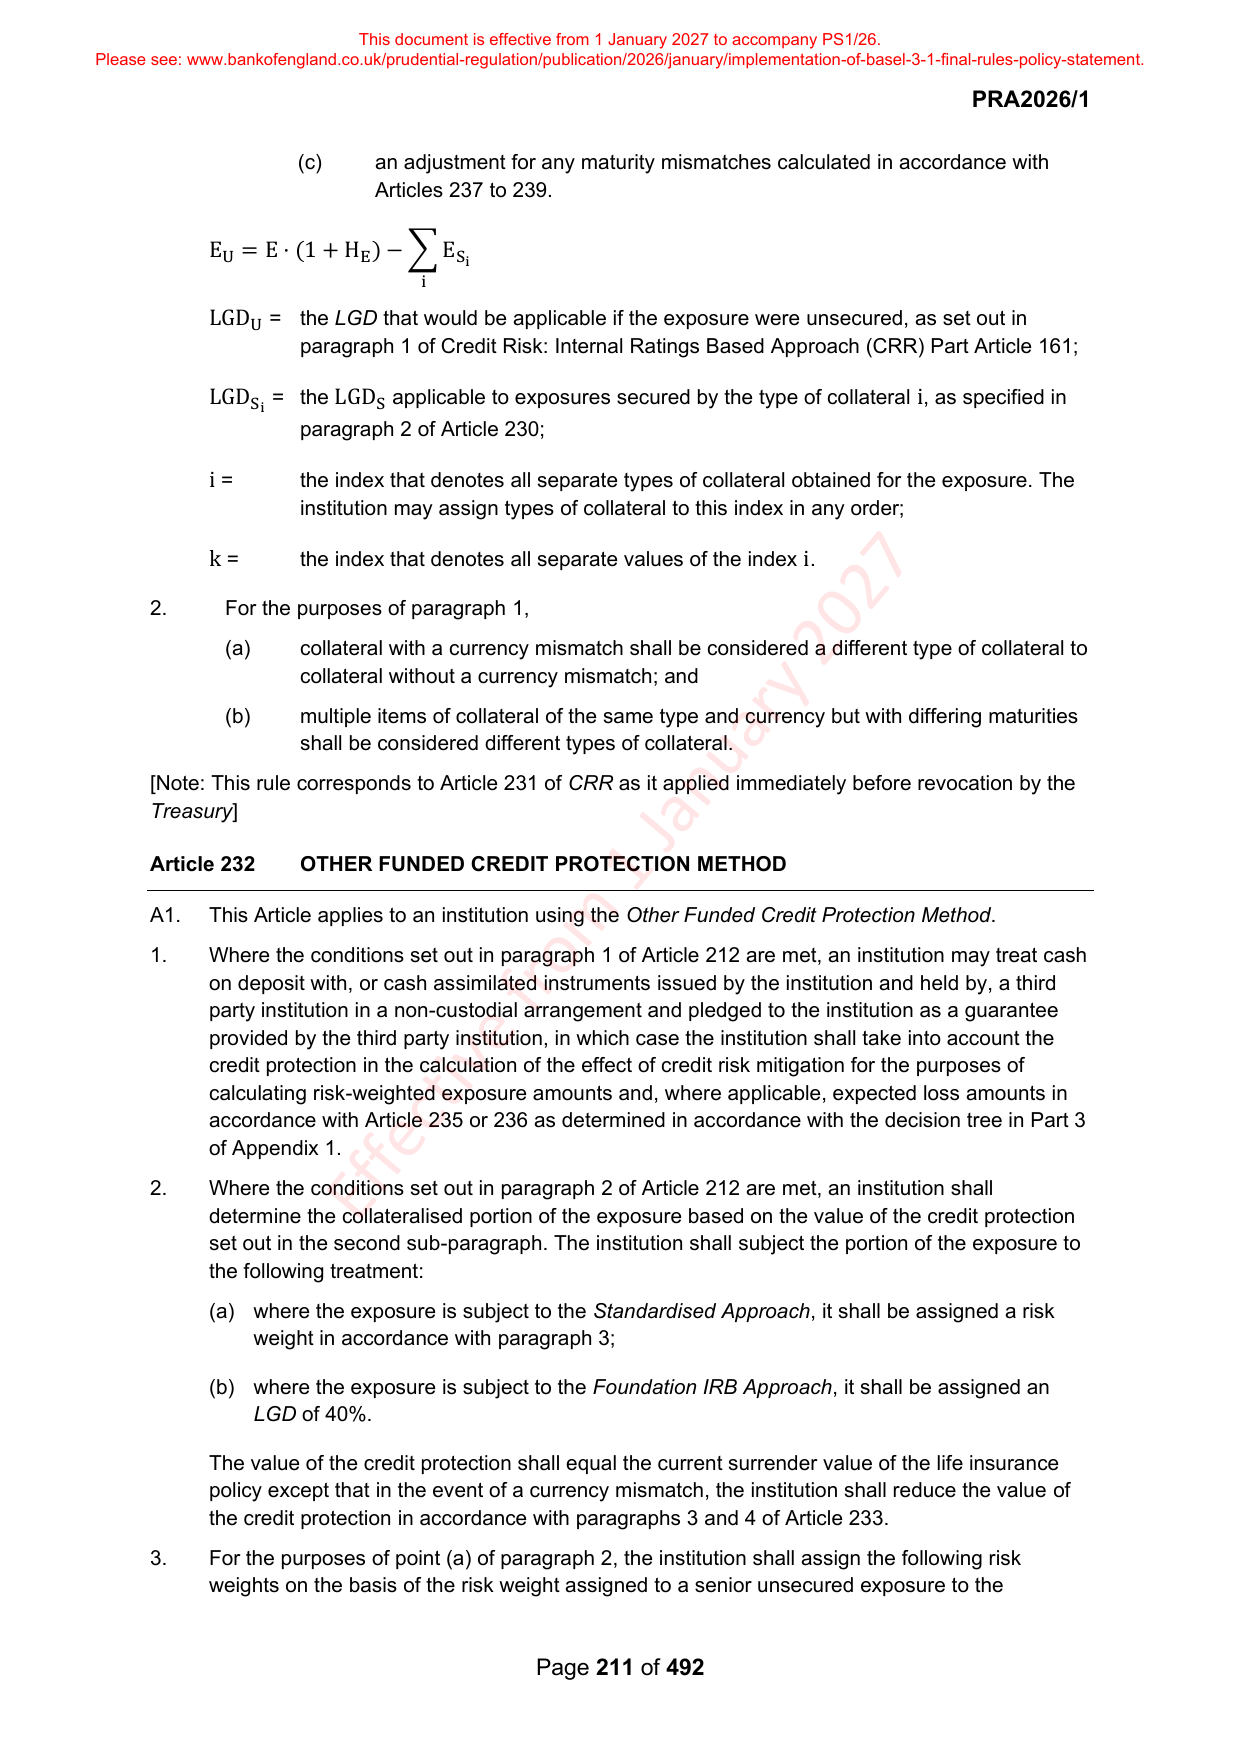
10961 E U = E · (1 + H E ) − ∑ E S
10962 i
10963 i
10965 LGD U = the LGD that would be applicable if the exposure were unsecured, as set out in
10966 paragraph 1 of Credit Risk: Internal Ratings Based Approach (CRR) Part Article 161;
10968 LGD S = the LGD S applicable to exposures secured by the type of collateral i , as specified in
10969 i
10970 paragraph 2 of Article 230;
10972 i = the index that denotes all separate types of collateral obtained for the exposure. The
10973 institution may assign types of collateral to this index in any order;
10975 k = the index that denotes all separate values of the index i .
10977 2. For the purposes of paragraph 1,
10978 (a) collateral with a currency mismatch shall be considered a different type of collateral to
10979 collateral without a currency mismatch; and
10980 (b) multiple items of collateral of the same type and currency but with differing maturities
10981 shall be considered different types of collateral.
10982 [Note: This rule corresponds to Article 231 of CRR as it applied immediately before revocation by the
10983 Treasury]
10985 Article 232 OTHER FUNDED CREDIT PROTECTION METHOD
10987 A1. This Article applies to an institution using the Other Funded Credit Protection Method.
10988 1. Where the conditions set out in paragraph 1 of Article 212 are met, an institution may treat cash
10989 on deposit with, or cash assimilated instruments issued by the institution and held by, a third
10990 party institution in a non-custodial arrangement and pledged to the institution as a guarantee
10991 provided by the third party institution, in which case the institution shall take into account the
10992 credit protection in the calculation of the effect of credit risk mitigation for the purposes of
10993 calculating risk-weighted exposure amounts and, where applicable, expected loss amounts in
10994 accordance with Article 235 or 236 as determined in accordance with the decision tree in Part 3
10995 of Appendix 1.
10996 2. Where the conditions set out in paragraph 2 of Article 212 are met, an institution shall
10997 determine the collateralised portion of the exposure based on the value of the credit protection
10998 set out in the second sub-paragraph. The institution shall subject the portion of the exposure to
10999 the following treatment:
11000 (a) where the exposure is subject to the Standardised Approach, it shall be assigned a risk
11001 weight in accordance with paragraph 3;
11003 (b) where the exposure is subject to the Foundation IRB Approach, it shall be assigned an
11004 LGD of 40%.
11006 The value of the credit protection shall equal the current surrender value of the life insurance
11007 policy except that in the event of a currency mismatch, the institution shall reduce the value of
11008 the credit protection in accordance with paragraphs 3 and 4 of Article 233.
11009 3. For the purposes of point (a) of paragraph 2, the institution shall assign the following risk
11010 weights on the basis of the risk weight assigned to a senior unsecured exposure to the
11012 Page 211 of 492