10834 This document is effective from 1 January 2027 to accompany PS1/26.
10835Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
10836 PRA2026/1
10838 Where the calculations under this paragraph 1 result in a negative value, the institution shall
10839 assign zero value to the collateral.
10841 2. For receivables, an institution shall use the amount receivable as the value of receivables.
10842 3. For physical collateral other than immovable property, an institution shall ensure the collateral
10843 is valued at, or at less than, its market value, by a suitably robust statistical method or by an
10844 independent valuer who possesses the necessary qualifications, ability and experience to
10845 execute a valuation.
10846 4. For the purposes of this Article, the market value is the estimated amount for which the
10847 property would exchange on the date of valuation between a willing buyer and a willing seller in
10848 an arm’s-length transaction.
10849 [Note: This rule corresponds to Article 229 of CRR as it applied immediately before revocation by the
10850 Treasury]
10852 Article 230 CALCULATING RISK-WEIGHTED EXPOSURE AMOUNTS AND EXPECTED LOSS
10853 AMOUNTS FOR ELIGIBLE COLLATERAL UNDER THE FOUNDATION
10854 COLLATERAL METHOD
10856 A1. This Article applies to an institution using the Foundation Collateral Method.
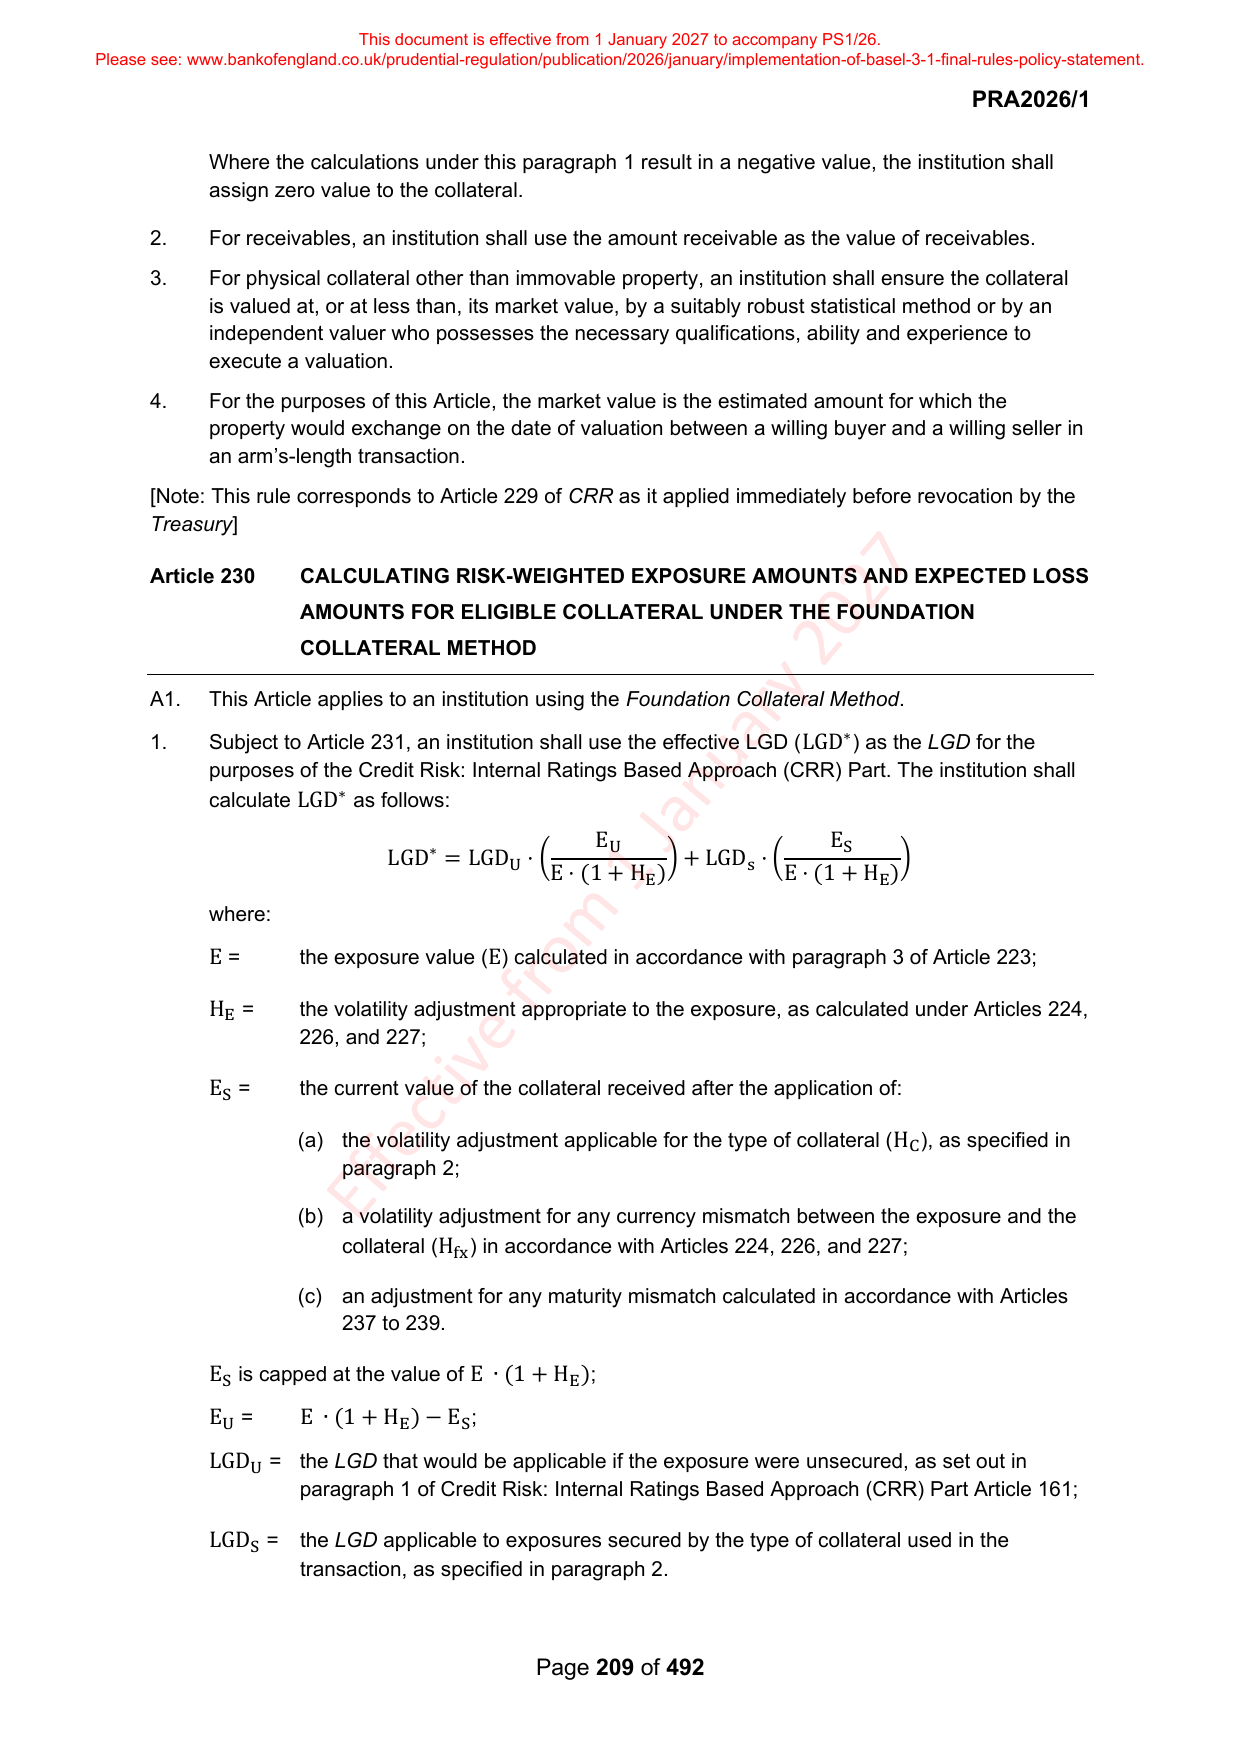
10858 1. Subject to Article 231, an institution shall use the effective LGD ( ∗ ) as the LGD for the
10859 LGD
10860 purposes of the Credit Risk: Internal Ratings Based Approach (CRR) Part. The institution shall
10861 calculate ∗ as follows:
10862 LGD
10863 E U E S
10864 ∗
10865 LGD = LGD U · ( ) + LGD s · ( )
10866 E · (1 + H E ) E · (1 + H E )
10867 where:
10869 E = the exposure value ( E ) calculated in accordance with paragraph 3 of Article 223;
10871 H E = the volatility adjustment appropriate to the exposure, as calculated under Articles 224,
10872 226, and 227;
10874 E S = the current value of the collateral received after the application of:
10876 (a) the volatility adjustment applicable for the type of collateral ( H C ), as specified in
10877 paragraph 2;
10879 (b) a volatility adjustment for any currency mismatch between the exposure and the
10880 collateral ( H fx ) in accordance with Articles 224, 226, and 227;
10882 (c) an adjustment for any maturity mismatch calculated in accordance with Articles
10883 237 to 239.
10885 E S is capped at the value of E ∙ (1 + H E ) ;
10886 E U = E ∙ (1 + H E ) − E S ;
10887 LGD U = the LGD that would be applicable if the exposure were unsecured, as set out in
10888 paragraph 1 of Credit Risk: Internal Ratings Based Approach (CRR) Part Article 161;
10890 LGD S = the LGD applicable to exposures secured by the type of collateral used in the
10891 transaction, as specified in paragraph 2.
10893 Page 209 of 492