10775 This document is effective from 1 January 2027 to accompany PS1/26.
10776Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
10777 PRA2026/1
10779 (e) regulated pension funds;
10781 (f) recognised clearing organisations.
10783 4. Where an institution is calculating the volatility adjustments to be applied for exposures subject
10784 to an eligible master netting agreement under Article 220, the institution may apply a 0%
10785 volatility adjustment under this Article only if all of the conditions in paragraph 2 are met for all
10786 transactions subject to the master netting agreement.
10787 [Note: This rule corresponds to Article 227 of CRR as it applied immediately before revocation by the
10788 Treasury]
10790 Article 228 CALCULATING RISK-WEIGHTED EXPOSURE AMOUNTS USING THE
10791 FINANCIAL COLLATERAL COMPREHENSIVE METHOD
10793 1. An institution using the Financial Collateral Comprehensive Method shall use ∗ as calculated
10794 E
10795 under paragraph 5 of Article 223 as the exposure value for the purposes of Credit Risk:
10796 Standardised Approach (CRR) Part Article 113 and Credit Risk: Internal Ratings Based
10797 Approach (CRR) Part Articles 166A to 166C. In the case of off-balance sheet items, the
10798 institution shall use ∗ as the value to which the percentages indicated in paragraph 1 of Credit
10799 E
10800 Risk: Standardised Approach (CRR) Part Article 111 and in paragraph 1 of Credit Risk: Internal
10801 Ratings Based Approach (CRR) Part Article 166C, as applicable, shall be applied to arrive at
10802 the exposure value.
10803 2. [Note: Provision left blank]
10804 [Note: This rule corresponds to Article 228(1) of CRR as it applied immediately before revocation by
10805 the Treasury]
10807 Article 229 VALUATION PRINCIPLES FOR OTHER ELIGIBLE COLLATERAL UNDER THE
10808 FOUNDATION COLLATERAL METHOD
10810 A1. This Article applies to an institution using the Foundation Collateral Method.
10811 1. For immovable property collateral, an institution shall ensure the collateral is valued at, or at
10812 less than, the market value by a suitably robust statistical method or by an independent valuer
10813 who possesses the necessary qualifications, ability and experience to execute a valuation. The
10814 institution shall ensure that the market value is documented in a transparent and clear manner.
10815 The value of the collateral shall be the market value reduced as appropriate:
10816 (a) to reflect the results of the monitoring required under paragraph 3 of Article 208;
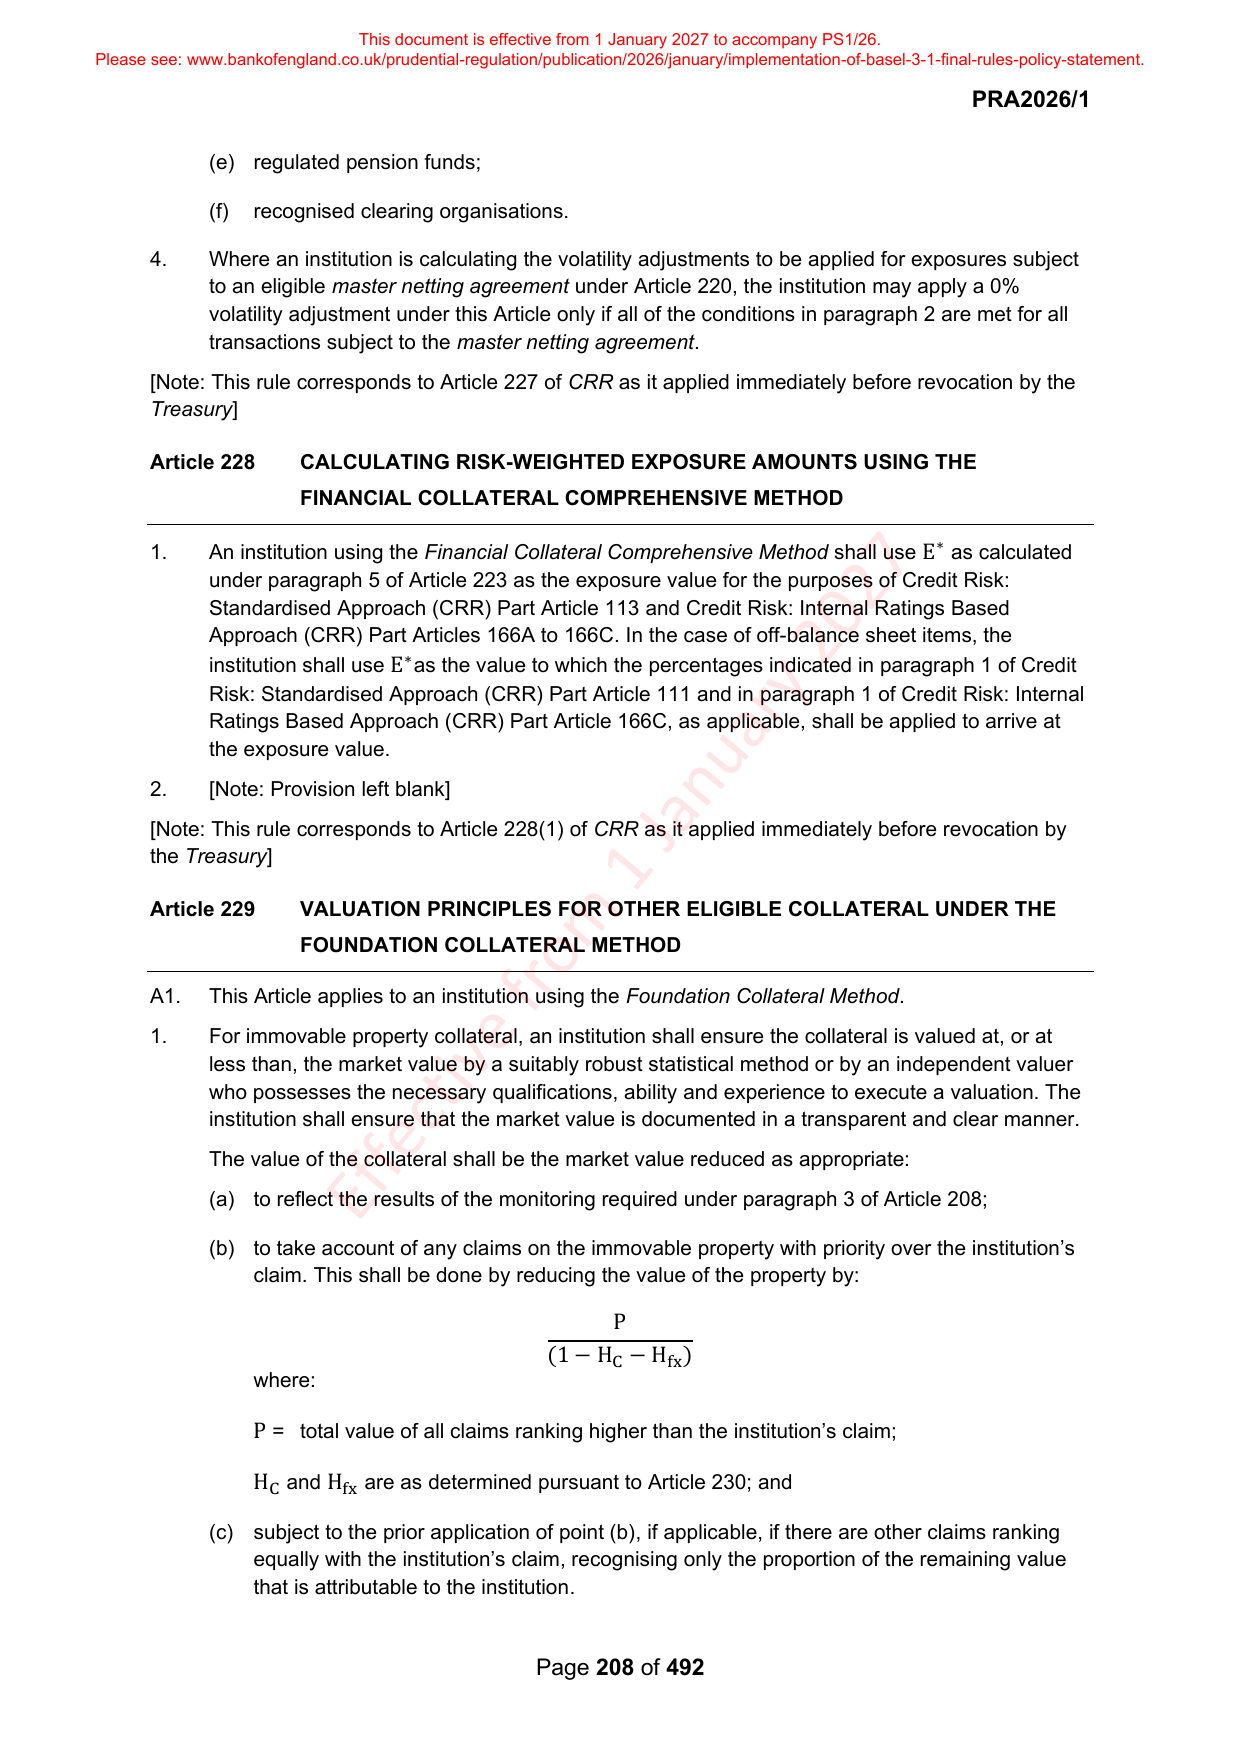
10818 (b) to take account of any claims on the immovable property with priority over the institution’s
10819 claim. This shall be done by reducing the value of the property by:
10821 P
10822 (1 − H C − H fx )
10823 where:
10825 P = total value of all claims ranking higher than the institution’s claim;
10827 H C and H fx are as determined pursuant to Article 230; and
10829 (c) subject to the prior application of point (b), if applicable, if there are other claims ranking
10830 equally with the institution’s claim, recognising only the proportion of the remaining value
10831 that is attributable to the institution.
10833 Page 208 of 492