22665 This document is effective from 1 January 2027 to accompany PS1/26.
22666Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
22667 PRA2026/1
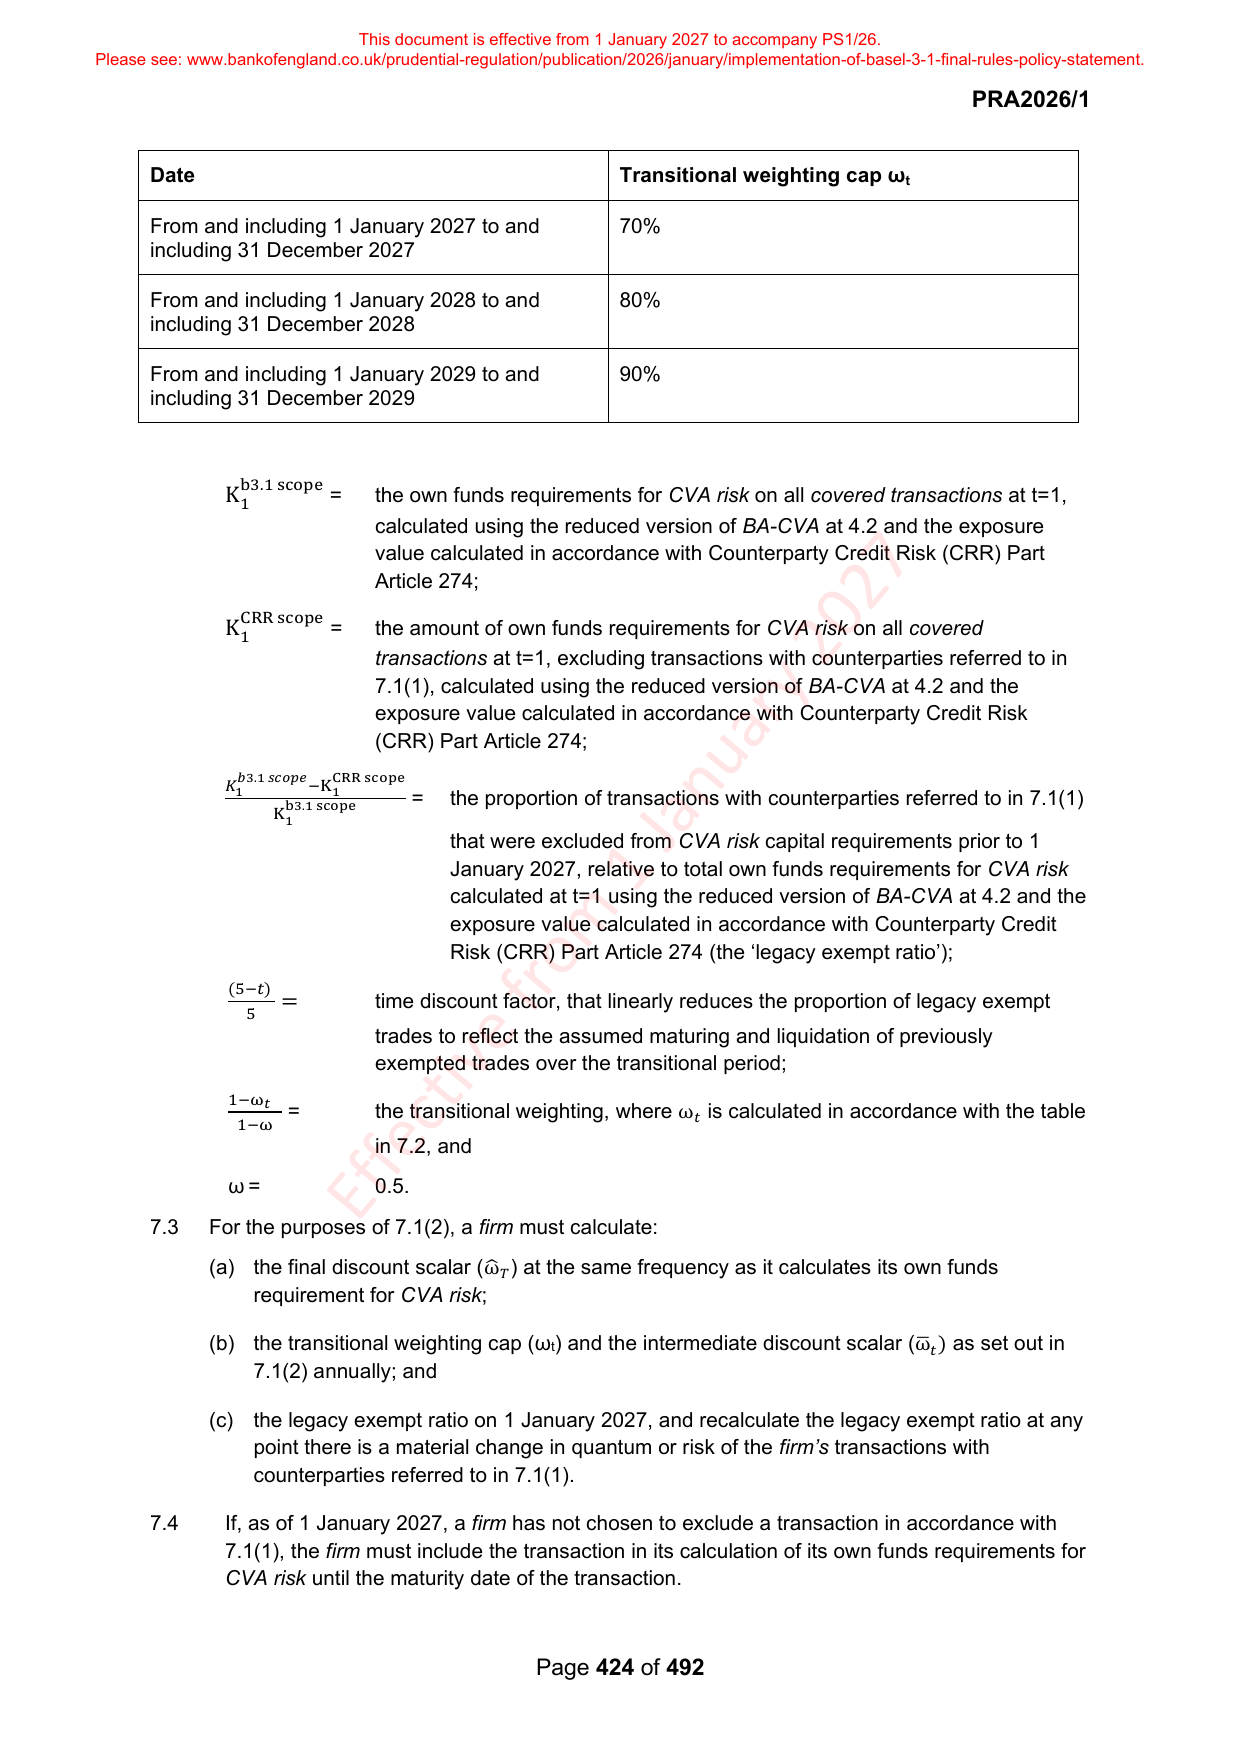
22669 Date Transitional weighting cap ω t
22671 From and including 1 January 2027 to and 70%
22672 including 31 December 2027
22674 From and including 1 January 2028 to and 80%
22675 including 31 December 2028
22677 From and including 1 January 2029 to and 90%
22678 including 31 December 2029
22680 b3.1 scope
22681 K = the own funds requirements for CVA risk on all covered transactions at t=1,
22682 1
22683 calculated using the reduced version of BA-CVA at 4.2 and the exposure
22684 value calculated in accordance with Counterparty Credit Risk (CRR) Part
22685 Article 274;
22686 CRR scope
22687 K = the amount of own funds requirements for CVA risk on all covered
22688 1
22689 transactions at t=1, excluding transactions with counterparties referred to in
22690 7.1(1), calculated using the reduced version of BA-CVA at 4.2 and the
22691 exposure value calculated in accordance with Counterparty Credit Risk
22692 (CRR) Part Article 274;
22694 𝑏3.1 𝑠𝑐𝑜𝑝𝑒 CRR scope
22695 𝐾 1 −K 1
22696 b3.1 scope = the proportion of transactions with counterparties referred to in 7.1(1)
22697 K
22698 1
22699 that were excluded from CVA risk capital requirements prior to 1
22700 January 2027, relative to total own funds requirements for CVA risk
22701 calculated at t=1 using the reduced version of BA-CVA at 4.2 and the
22702 exposure value calculated in accordance with Counterparty Credit
22703 Risk (CRR) Part Article 274 (the ‘legacy exempt ratio’);
22704 (5−𝑡)
22705 = time discount factor, that linearly reduces the proportion of legacy exempt
22706 5
22707 trades to reflect the assumed maturing and liquidation of previously
22708 exempted trades over the transitional period;
22709 1−ω 𝑡
22710 = the transitional weighting, where ω 𝑡 is calculated in accordance with the table
22711 1−ω
22712 in 7.2, and
22713 ω = 0.5.
22714 7.3 For the purposes of 7.1(2), a firm must calculate:
22715 (a) the final discount scalar (ω ̂ 𝑇 ) at the same frequency as it calculates its own funds
22716 requirement for CVA risk;
22718 (b) the transitional weighting cap (ω t ) and the intermediate discount scalar (ω ̅ 𝑡 ) as set out in
22719 7.1(2) annually; and
22721 (c) the legacy exempt ratio on 1 January 2027, and recalculate the legacy exempt ratio at any
22722 point there is a material change in quantum or risk of the firm’s transactions with
22723 counterparties referred to in 7.1(1).
22725 7.4 If, as of 1 January 2027, a firm has not chosen to exclude a transaction in accordance with
22726 7.1(1), the firm must include the transaction in its calculation of its own funds requirements for
22727 CVA risk until the maturity date of the transaction.
22729 Page 424 of 492