22596 This document is effective from 1 January 2027 to accompany PS1/26.
22597Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
22598 PRA2026/1
22600 (1) not recognise the effect of CVA hedges; and
22602 (2) apply the alternative approach to the firm’s entire portfolio of covered transactions.
22604 6.4 A firm that chooses to use the alternative approach in 6.2 must notify the PRA in writing that it
22605 meets the condition in 6.1(1) prior to using the alternative approach.
22607 7 TRANSITIONAL PROVISIONS
22609 7.1 A firm may, until 1 January 2030:
22610 (1) exclude from its calculation of own funds requirements for CVA risk transactions entered
22611 into prior to 1 January 2027 with the following counterparties:
22612 (a) non-financial counterparties as defined in point (9) of Article 2 of Regulation (EU) No
22613 648/2012 and non-financial counterparties established in a third country where those
22614 transactions do not exceed the clearing threshold as specified in Article 10(3) and (4)
22615 of Regulation (EU) No 648/2012;
22617 (b) counterparties referred to in point (10) of Article 2 of Regulation (EU) No 648/2012
22618 and point (1) of Article 89 of Regulation (EU) No 648/2012; and
22620 (c) counterparties referred to in Article 1(4) and (5) of Regulation (EU) No 648/2012 and
22621 counterparties for which the firm had been assigning a risk weight of 0% for
22622 exposures to those counterparties in accordance with Articles 114(4) and 115(2) of
22623 CRR as those Articles applied immediately before revocation by the Treasury; or
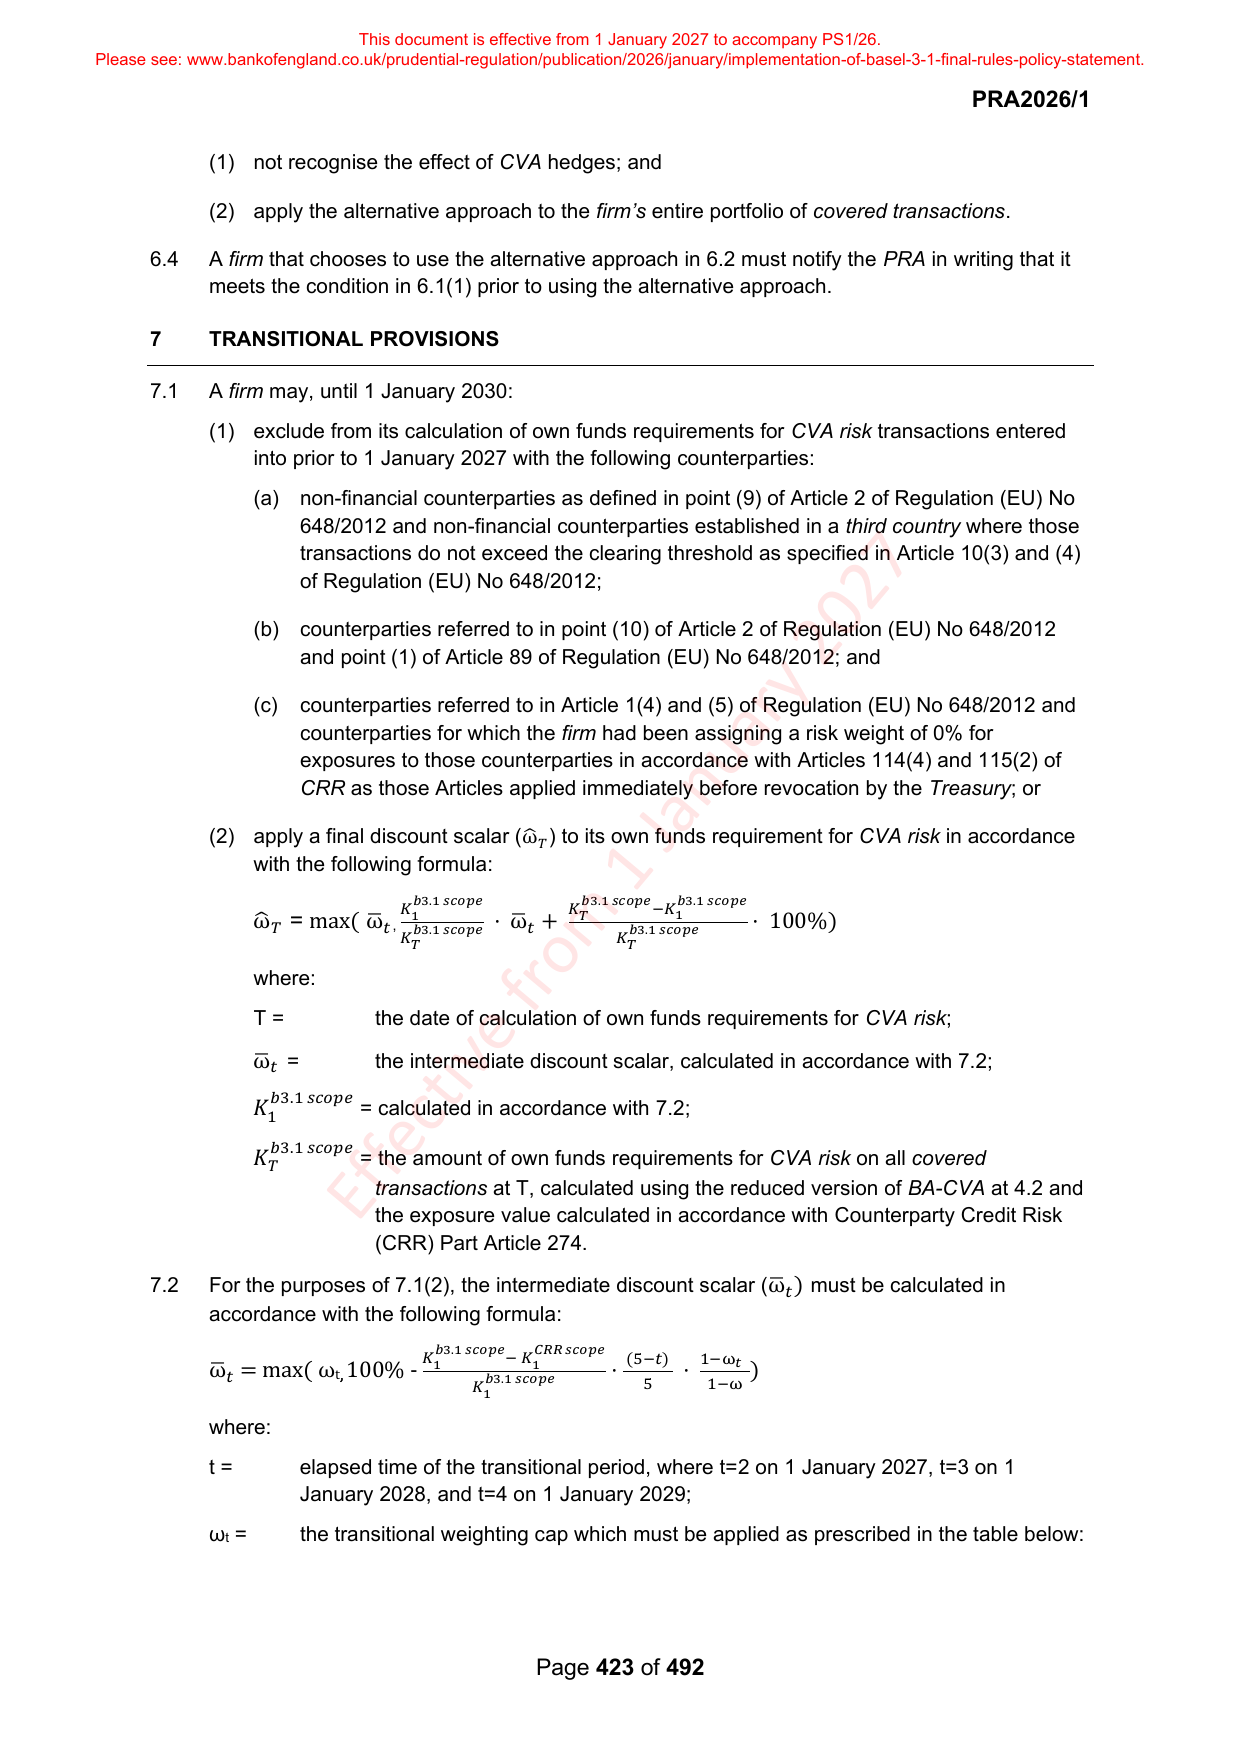
22625 (2) apply a final discount scalar (ω ̂ 𝑇 ) to its own funds requirement for CVA risk in accordance
22626 with the following formula:
22628 𝑏3.1 𝑠𝑐𝑜𝑝𝑒 𝑏3.1 𝑠𝑐𝑜𝑝𝑒 𝑏3.1 𝑠𝑐𝑜𝑝𝑒
22629 𝐾 𝐾 𝑇 −𝐾 1
22630 = 1
22631 ω ̂ 𝑇 max( ω ̅ 𝑡 , 𝑏3.1 𝑠𝑐𝑜𝑝𝑒 · ω ̅ 𝑡 + 𝑏3.1 𝑠𝑐𝑜𝑝𝑒 · 100%)
22632 𝐾 𝐾
22633 𝑇 𝑇
22635 where:
22636 T = the date of calculation of own funds requirements for CVA risk;
22638 ω ̅ 𝑡 = the intermediate discount scalar, calculated in accordance with 7.2;
22639 𝑏3.1 𝑠𝑐𝑜𝑝𝑒
22640 𝐾 = calculated in accordance with 7.2;
22641 1
22643 𝑏3.1 𝑠𝑐𝑜𝑝𝑒
22644 𝐾 = the amount of own funds requirements for CVA risk on all covered
22645 𝑇
22646 transactions at T, calculated using the reduced version of BA-CVA at 4.2 and
22647 the exposure value calculated in accordance with Counterparty Credit Risk
22648 (CRR) Part Article 274.
22650 7.2 For the purposes of 7.1(2), the intermediate discount scalar ( ω ̅ 𝑡 ) must be calculated in
22651 accordance with the following formula:
22653 𝑏3.1 𝑠𝑐𝑜𝑝𝑒 𝐶𝑅𝑅 𝑠𝑐𝑜𝑝𝑒
22654 𝐾 1 − 𝐾 1 (5−𝑡) 1−ω 𝑡
22655 ω ̅ 𝑡 = max( ω t, 100% - 𝑏3.1 𝑠𝑐𝑜𝑝𝑒 · · )
22656 𝐾 5 1−ω
22657 1
22659 where:
22660 t = elapsed time of the transitional period, where t=2 on 1 January 2027, t=3 on 1
22661 January 2028, and t=4 on 1 January 2029;
22662 ω t = the transitional weighting cap which must be applied as prescribed in the table below:
22664 Page 423 of 492