21220 This document is effective from 1 January 2027 to accompany PS1/26.
21221Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
21222 PRA2026/1
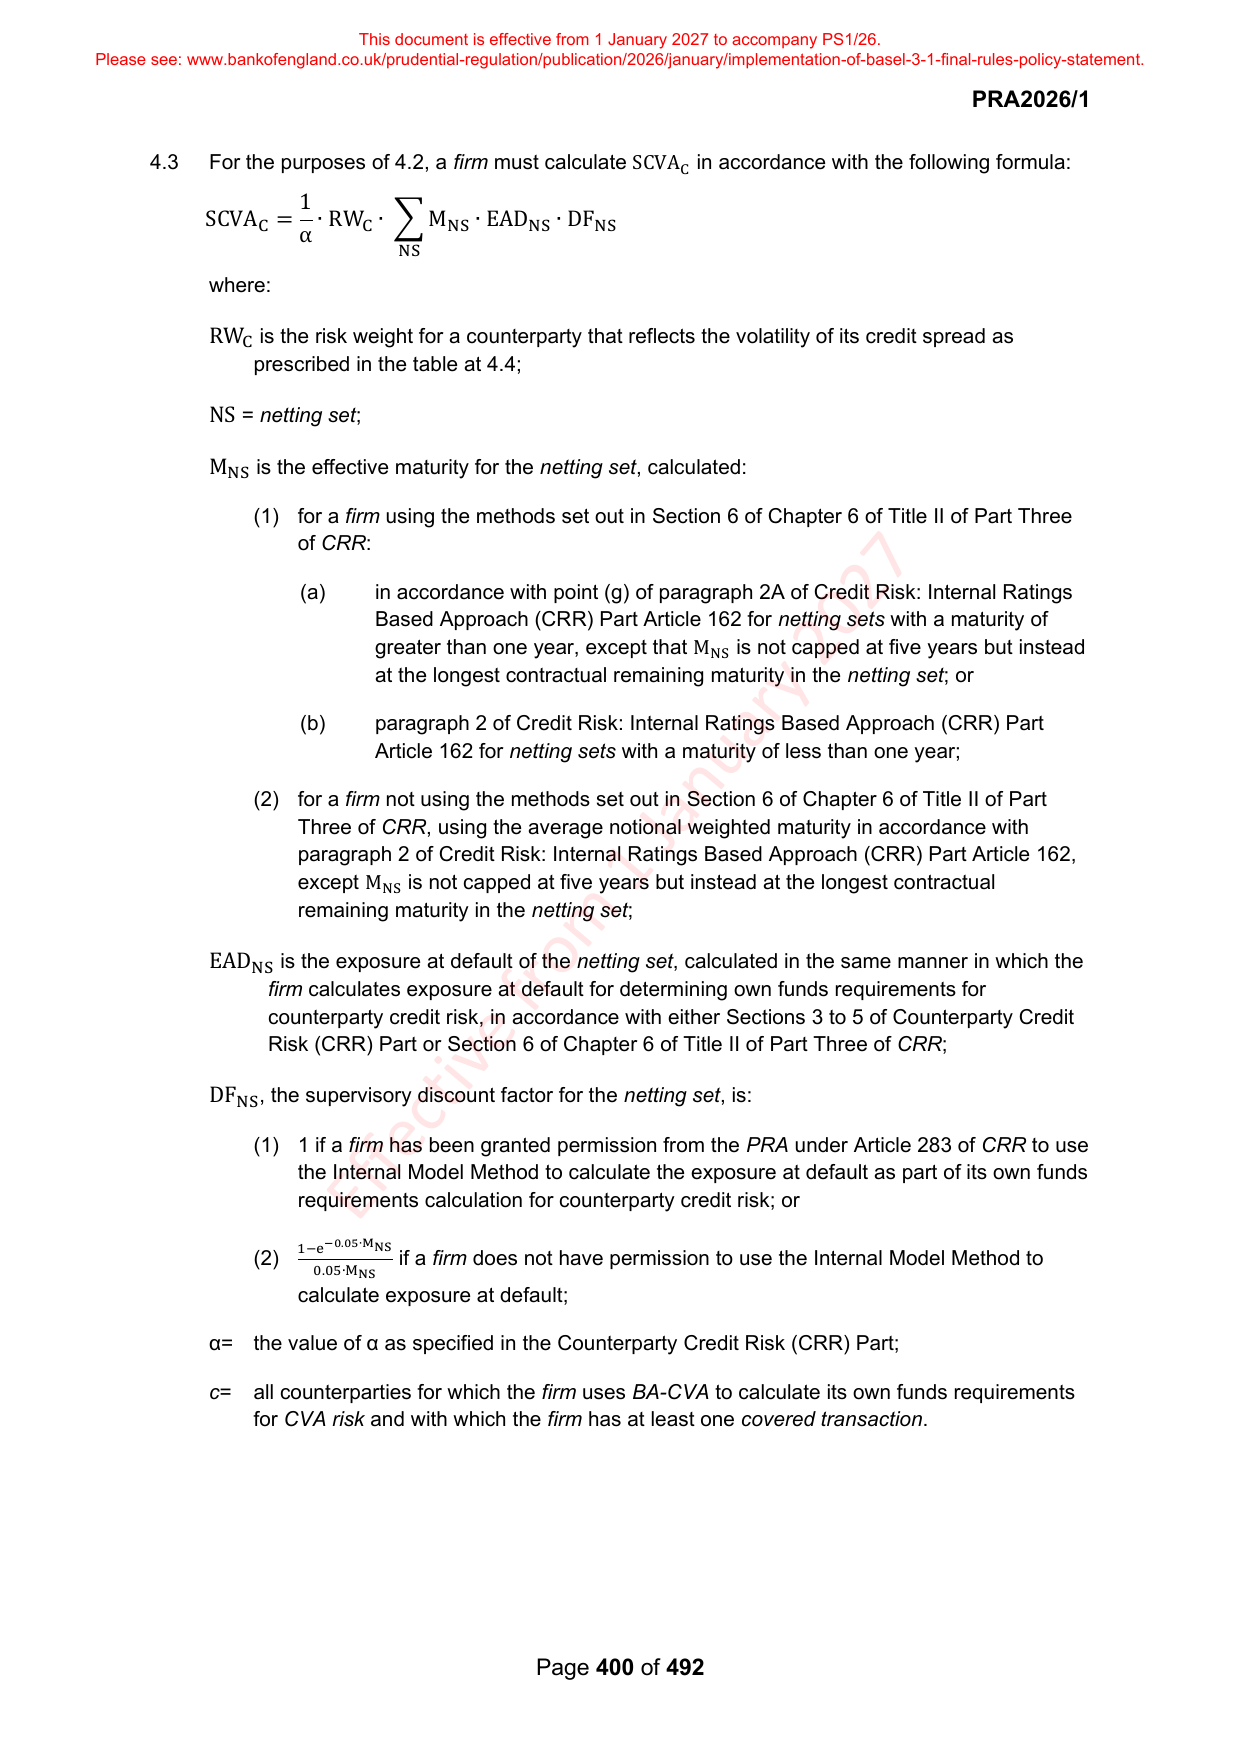
21224 4.3 For the purposes of 4.2, a firm must calculate SCVA C in accordance with the following formula:
21225 1
21226 SCVA C = ∙ RW C ∙ ∑ M NS ∙ EAD NS ∙ DF NS
21227 α
21228 NS
21230 where:
21232 RW C is the risk weight for a counterparty that reflects the volatility of its credit spread as
21233 prescribed in the table at 4.4;
21235 NS = netting set;
21237 M NS is the effective maturity for the netting set, calculated:
21239 (1) for a firm using the methods set out in Section 6 of Chapter 6 of Title II of Part Three
21240 of CRR:
21242 (a) in accordance with point (g) of paragraph 2A of Credit Risk: Internal Ratings
21243 Based Approach (CRR) Part Article 162 for netting sets with a maturity of
21244 greater than one year, except that M NS is not capped at five years but instead
21245 at the longest contractual remaining maturity in the netting set; or
21247 (b) paragraph 2 of Credit Risk: Internal Ratings Based Approach (CRR) Part
21248 Article 162 for netting sets with a maturity of less than one year;
21250 (2) for a firm not using the methods set out in Section 6 of Chapter 6 of Title II of Part
21251 Three of CRR, using the average notional weighted maturity in accordance with
21252 paragraph 2 of Credit Risk: Internal Ratings Based Approach (CRR) Part Article 162,
21253 except M NS is not capped at five years but instead at the longest contractual
21254 remaining maturity in the netting set;
21256 EAD NS is the exposure at default of the netting set, calculated in the same manner in which the
21257 firm calculates exposure at default for determining own funds requirements for
21258 counterparty credit risk, in accordance with either Sections 3 to 5 of Counterparty Credit
21259 Risk (CRR) Part or Section 6 of Chapter 6 of Title II of Part Three of CRR;
21261 DF NS , the supervisory discount factor for the netting set, is:
21263 (1) 1 if a firm has been granted permission from the PRA under Article 283 of CRR to use
21264 the Internal Model Method to calculate the exposure at default as part of its own funds
21265 requirements calculation for counterparty credit risk; or
21267 1−e −0.05∙MNS
21268 (2) if a firm does not have permission to use the Internal Model Method to
21269 0.05∙M NS
21270 calculate exposure at default;
21272 α= the value of α as specified in the Counterparty Credit Risk (CRR) Part;
21274 c= all counterparties for which the firm uses BA-CVA to calculate its own funds requirements
21275 for CVA risk and with which the firm has at least one covered transaction.
21277 Page 400 of 492