21163 This document is effective from 1 January 2027 to accompany PS1/26.
21164Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
21165 PRA2026/1
21167 (3) include external CVA hedges that are not eligible CVA hedges in its trading book
21168 calculation of market risk own funds requirements under the market risk Parts.
21170 3.5 A firm may include an internal CVA hedge that is subject to curvature risk in accordance with
21171 Market Risk: Advanced Standardised Approach (CRR) Part Articles 325e and 325g, default risk
21172 charge in accordance with Market Risk: Advanced Standardised Approach (CRR) Part Articles
21173 325v to 325ad, or residual risk add-on in accordance with Market Risk: Advanced Standardised
21174 Approach (CRR) Part Article 325u, as an eligible CVA hedge only if the trading desk that is the
21175 internal counterparty to the CVA desk enters into a transaction or a set of transactions with one
21176 or more external counterparties that exactly offsets the trading desk’s position with the CVA
21177 desk.
21178 3.6 For the purposes of 4.4, 5.27 and 5.28, where a counterparty is not externally rated, a firm that
21179 has been granted permission from the PRA under the Credit Risk: Internal Ratings Based
21180 Approach (CRR) Part Article 143 to use the internal rating based approach in accordance with
21181 the Credit Risk: Internal Ratings Based Approach (CRR) Part to calculate credit risk own funds
21182 requirements in respect of exposures to the counterparty must map the internal rating to an
21183 external rating and assign a risk weight corresponding to either investment grade or high yield.
21185 4 BASIC APPROACH
21187 4.1 A firm that:
21188 (1) does not have permission from the PRA to use SA-CVA; and
21190 (2) if relevant to the firm, has not chosen to use the alternative approach in Chapter 6;
21192 must calculate its own funds requirements for CVA risk for covered transactions in accordance
21193 with this Chapter.
21194 Reduced version of BA-CVA
21195 4.2 If a firm does not use any eligible BA-CVA hedges to hedge CVA risk it must calculate its own
21196 funds requirement for CVA risk in accordance with the following formula:
21198 DS BA−CVA × K reduced
21199 where:
21201 DS BA−CVA = 0.65 ; and
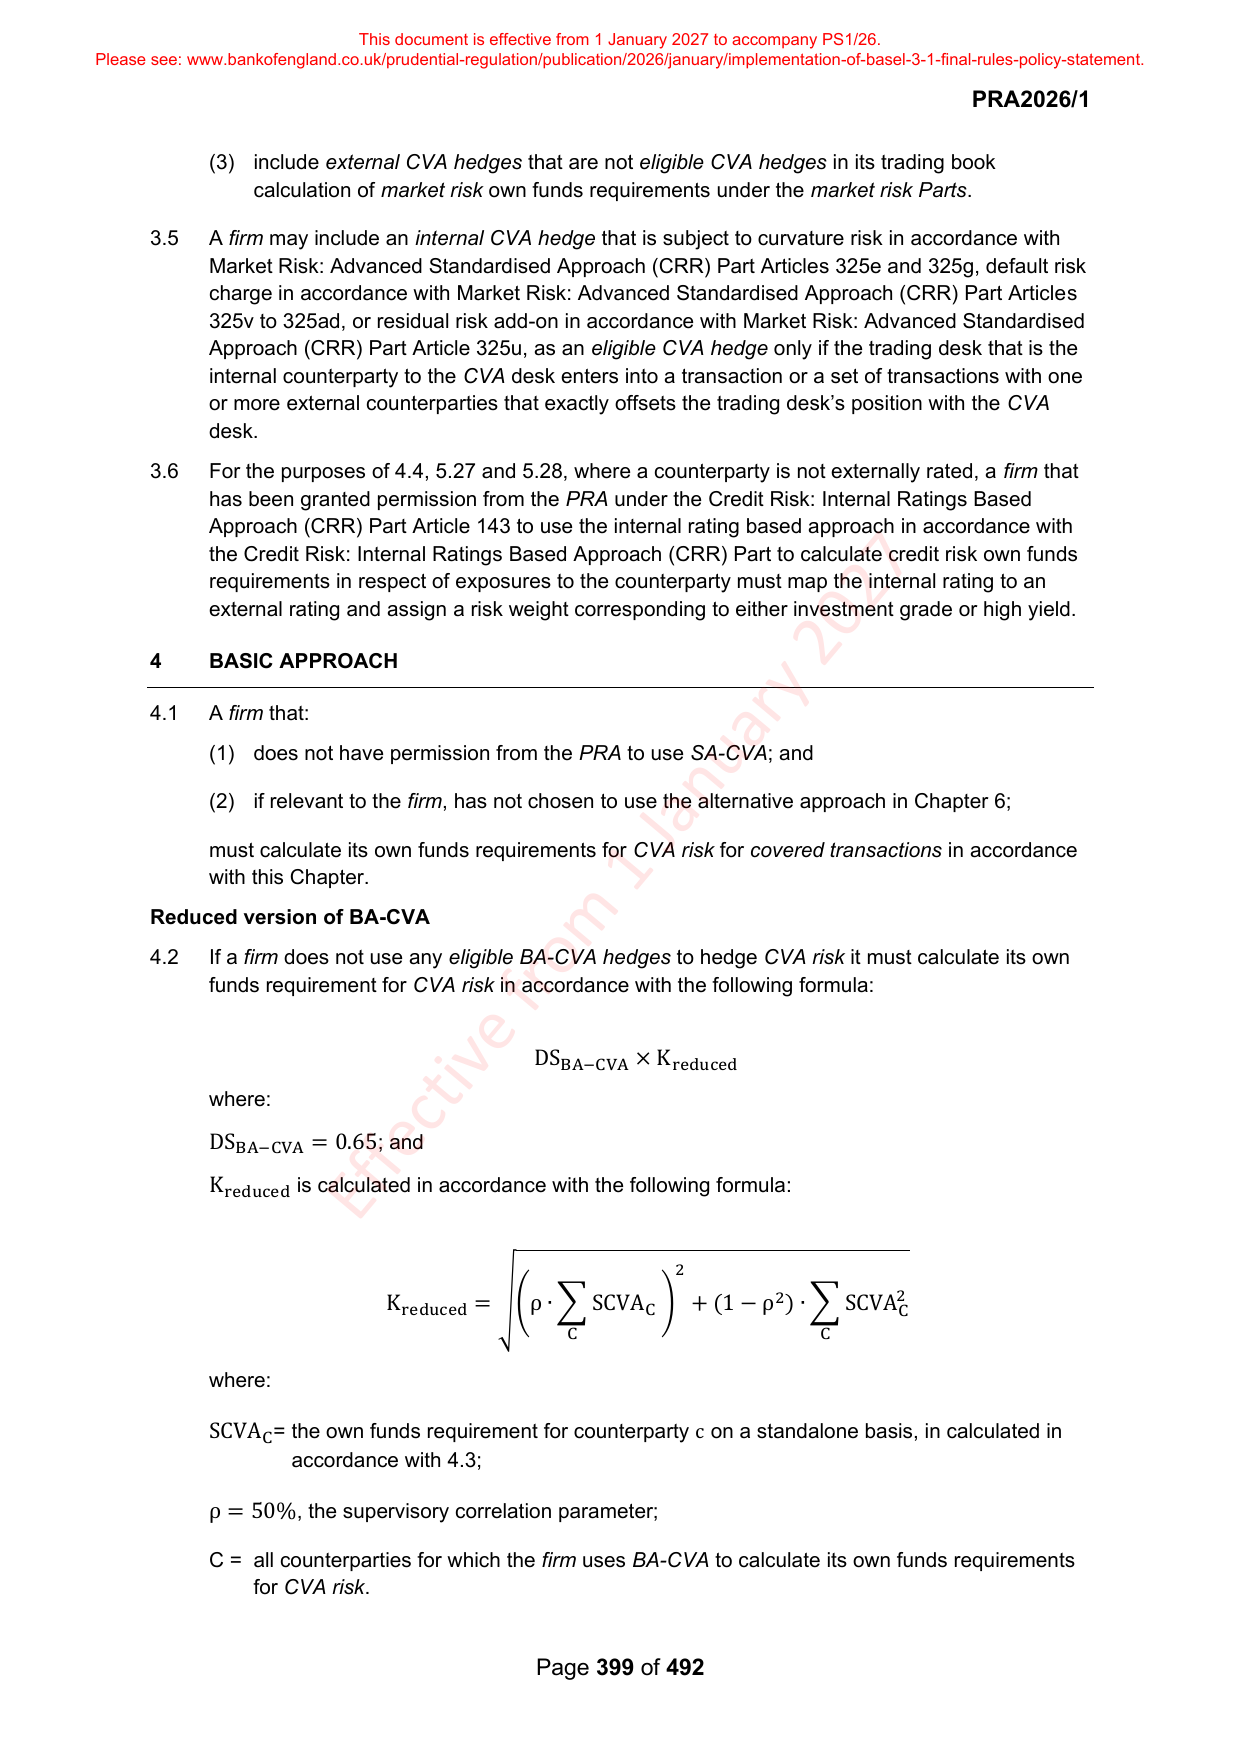
21202 K reduced is calculated in accordance with the following formula:
21204 2
21205 √(ρ 2 2
21206 K reduced = ∙ ∑ SCVA C ) + (1 − ρ ) ∙ ∑ SCVA C
21207 C C
21209 where:
21211 SCVA C = the own funds requirement for counterparty c on a standalone basis, in calculated in
21212 accordance with 4.3;
21214 ρ = 50% , the supervisory correlation parameter;
21216 C = all counterparties for which the firm uses BA-CVA to calculate its own funds requirements
21217 for CVA risk.
21219 Page 399 of 492