19931 This document is effective from 1 January 2027 to accompany PS1/26.
19932Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
19933 PRA2026/1
19935 where:
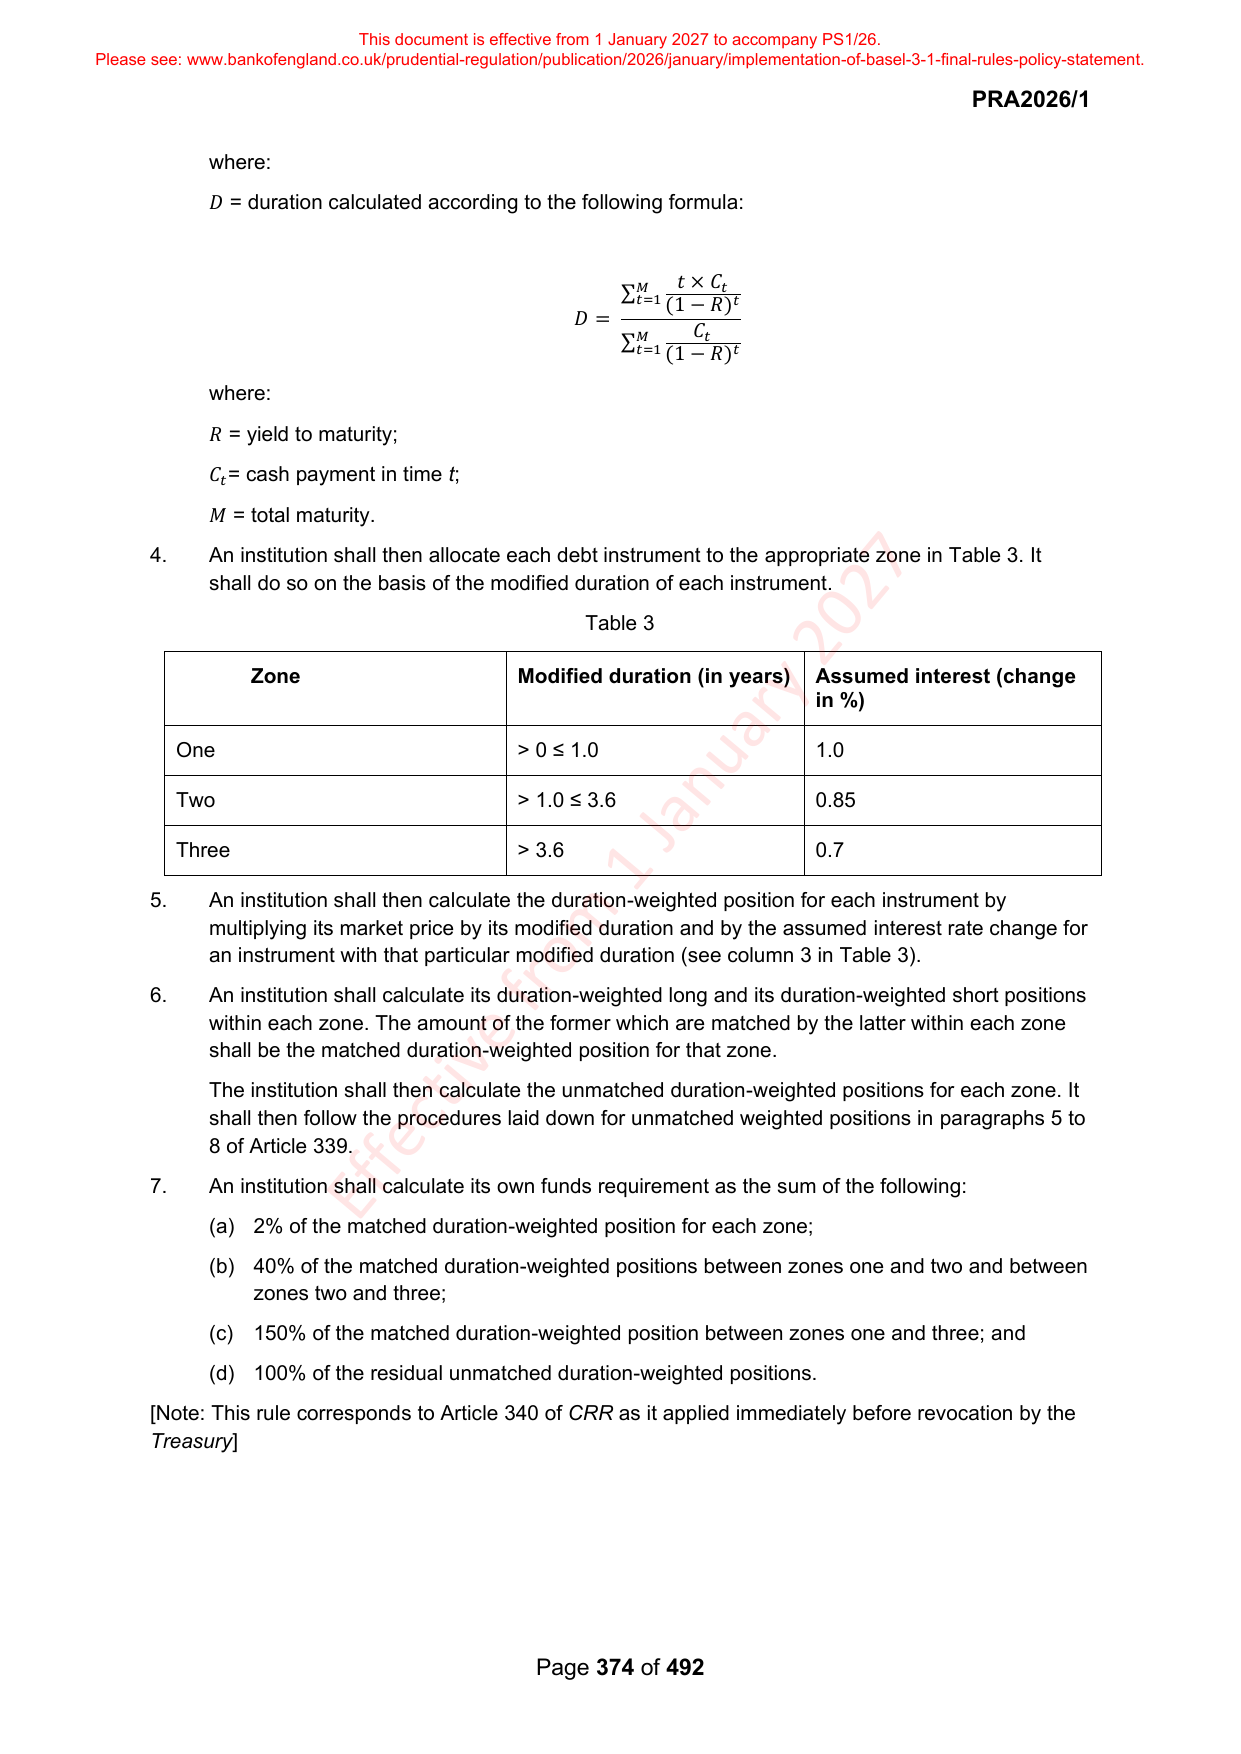
19937 𝐷 = duration calculated according to the following formula:
19939 𝑀 𝑡 × 𝐶 𝑡
19940 ∑ 𝑡=1 𝑡
19941 (1 − 𝑅)
19942 𝐷=
19943 𝑀 𝐶 𝑡
19944 ∑ 𝑡=1 𝑡
19945 (1 − 𝑅)
19946 where:
19948 𝑅 = yield to maturity;
19950 𝐶 𝑡 = cash payment in time t;
19952 𝑀 = total maturity.
19954 4. An institution shall then allocate each debt instrument to the appropriate zone in Table 3. It
19955 shall do so on the basis of the modified duration of each instrument.
19956 Table 3
19958 Zone Modified duration (in years) Assumed interest (change
19959 in %)
19961 One > 0 ≤ 1.0 1.0
19963 Two > 1.0 ≤ 3.6 0.85
19965 Three > 3.6 0.7
19967 5. An institution shall then calculate the duration-weighted position for each instrument by
19968 multiplying its market price by its modified duration and by the assumed interest rate change for
19969 an instrument with that particular modified duration (see column 3 in Table 3).
19970 6. An institution shall calculate its duration-weighted long and its duration-weighted short positions
19971 within each zone. The amount of the former which are matched by the latter within each zone
19972 shall be the matched duration-weighted position for that zone.
19973 The institution shall then calculate the unmatched duration-weighted positions for each zone. It
19974 shall then follow the procedures laid down for unmatched weighted positions in paragraphs 5 to
19975 8 of Article 339.
19976 7. An institution shall calculate its own funds requirement as the sum of the following:
19977 (a) 2% of the matched duration-weighted position for each zone;
19978 (b) 40% of the matched duration-weighted positions between zones one and two and between
19979 zones two and three;
19980 (c) 150% of the matched duration-weighted position between zones one and three; and
19981 (d) 100% of the residual unmatched duration-weighted positions.
19982 [Note: This rule corresponds to Article 340 of CRR as it applied immediately before revocation by the
19983 Treasury]
19985 Page 374 of 492