19878 This document is effective from 1 January 2027 to accompany PS1/26.
19879Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
19880 PRA2026/1
19882 > 20 years > 10.6 ≤ 12.0 years 6.00 0.60
19884 > 12.0 ≤ 20.0 years 8.00 0.60
19886 > 20 years 12.50 0.60
19888 5. The amount of the unmatched weighted long or short position in zone one which is matched by
19889 the unmatched weighted short or long position in zone two shall then be the matched weighted
19890 position between zones one and two. The same calculation shall then be undertaken with
19891 regard to that part of the unmatched weighted position in zone two which is left over and the
19892 unmatched weighted position in zone three in order to calculate the matched weighted position
19893 between zones two and three.
19894 6. An institution may reverse the order in paragraph 5 so as to calculate the matched weighted
19895 position between zones two and three before calculating that position between zones one and
19896 two.
19897 7. The remainder of the unmatched weighted position in zone one shall then be matched with
19898 what remains of that for zone three after the latter's matching with zone two in order to derive
19899 the matched weighted position between zones one and three.
19900 8. Residual positions, following the three separate matching calculations in paragraphs 5, 6 and 7
19901 shall be summed.
19902 9. An institution shall calculate its own funds requirement as the sum of:
19903 (a) 10% of the sum of the matched weighted positions in all maturity bands;
19904 (b) 40% of the matched weighted position in zone one;
19905 (c) 30% of the matched weighted position in zone two;
19906 (d) 30% of the matched weighted position in zone three;
19907 (e) 40% of the matched weighted position between zones one and two and between zones
19908 two and three;
19909 (f) 150% of the matched weighted position between zones one and three; and
19910 (g) 100% of the residual unmatched weighted positions.
19911 [Note: This rule corresponds to Article 339 of CRR as it applied immediately before revocation by the
19912 Treasury]
19914 Article 340 DURATION-BASED CALCULATION OF GENERAL RISK
19916 1. An institution may use an approach for calculating the own funds requirement for the general
19917 risk on debt instruments which reflects duration, instead of the approach set out in Article 339,
19918 provided that the institution does so on a consistent basis.
19919 2. Under the duration-based approach referred to in paragraph 1, an institution shall take the
19920 market value of each fixed-rate debt instrument and hence calculate its yield to maturity, which
19921 is implied discount rate for that instrument. In the case of floating-rate instruments, the
19922 institution shall take the market value of each instrument and hence calculate its yield on the
19923 assumption that the principal is due when the interest rate can next be changed.
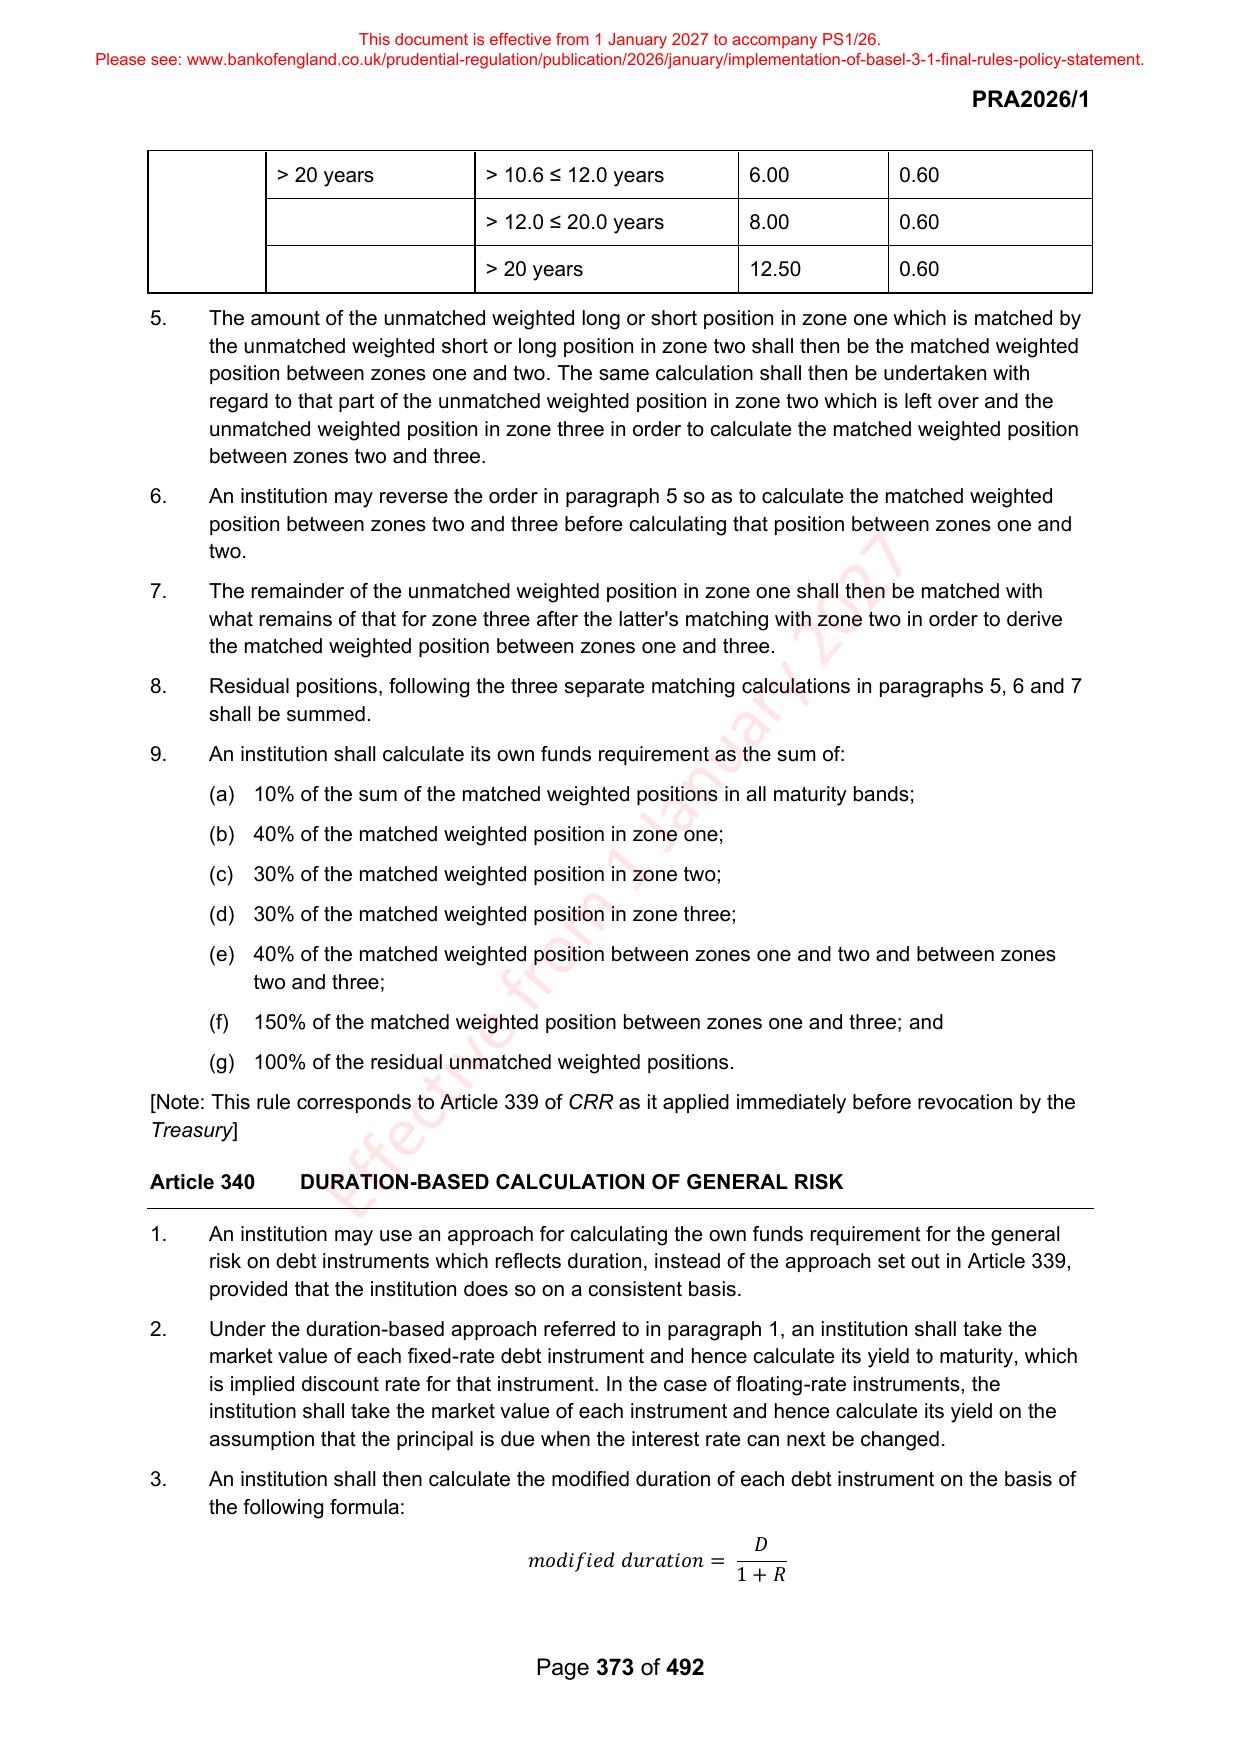
19924 3. An institution shall then calculate the modified duration of each debt instrument on the basis of
19925 the following formula:
19926 𝐷
19927 𝑚𝑜𝑑𝑖𝑓𝑖𝑒𝑑 𝑑𝑢𝑟𝑎𝑡𝑖𝑜𝑛 =
19928 1+𝑅
19930 Page 373 of 492