18780 This document is effective from 1 January 2027 to accompany PS1/26.
18781Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
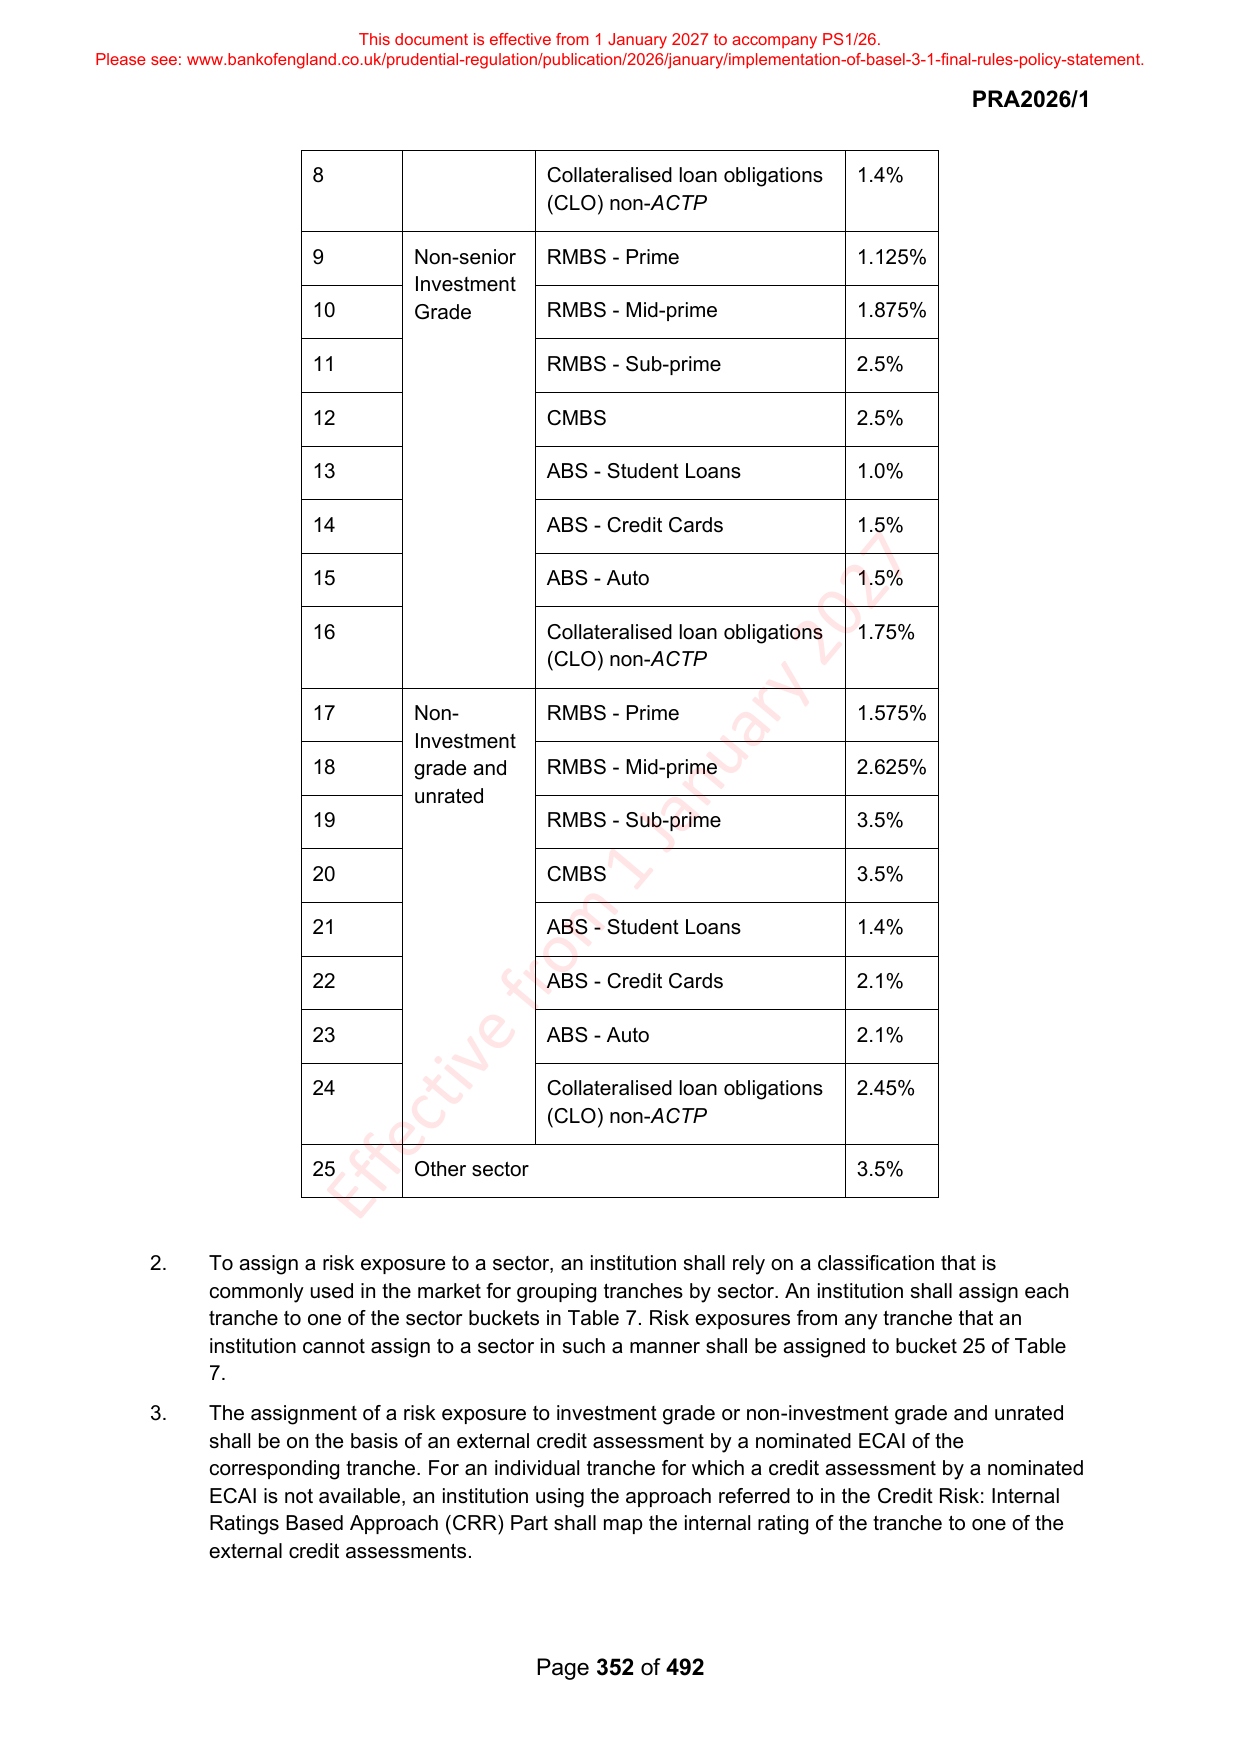
18782 PRA2026/1
18784 8 Collateralised loan obligations 1.4%
18785 (CLO) non-ACTP
18787 9 Non-senior RMBS - Prime 1.125%
18788 Investment
18789 10 Grade RMBS - Mid-prime 1.875%
18791 11 RMBS - Sub-prime 2.5%
18793 12 CMBS 2.5%
18795 13 ABS - Student Loans 1.0%
18797 14 ABS - Credit Cards 1.5%
18799 15 ABS - Auto 1.5%
18801 16 Collateralised loan obligations 1.75%
18802 (CLO) non-ACTP
18804 17 Non- RMBS - Prime 1.575%
18805 Investment
18806 18 grade and RMBS - Mid-prime 2.625%
18807 unrated
18808 19 RMBS - Sub-prime 3.5%
18810 20 CMBS 3.5%
18812 21 ABS - Student Loans 1.4%
18814 22 ABS - Credit Cards 2.1%
18816 23 ABS - Auto 2.1%
18818 24 Collateralised loan obligations 2.45%
18819 (CLO) non-ACTP
18821 25 Other sector 3.5%
18823 2. To assign a risk exposure to a sector, an institution shall rely on a classification that is
18824 commonly used in the market for grouping tranches by sector. An institution shall assign each
18825 tranche to one of the sector buckets in Table 7. Risk exposures from any tranche that an
18826 institution cannot assign to a sector in such a manner shall be assigned to bucket 25 of Table
18827 7.
18828 3. The assignment of a risk exposure to investment grade or non-investment grade and unrated
18829 shall be on the basis of an external credit assessment by a nominated ECAI of the
18830 corresponding tranche. For an individual tranche for which a credit assessment by a nominated
18831 ECAI is not available, an institution using the approach referred to in the Credit Risk: Internal
18832 Ratings Based Approach (CRR) Part shall map the internal rating of the tranche to one of the
18833 external credit assessments.
18835 Page 352 of 492