18724 This document is effective from 1 January 2027 to accompany PS1/26.
18725Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
18726 PRA2026/1
18728 15 Health care, utilities, 12.0%
18729 professional and technical
18730 activities
18732 16 Other Sector 13.0%
18734 2. The assignment of a risk exposure to investment grade or non-investment grade and unrated
18735 shall be on the basis of an external credit assessment by a nominated ECAI of the
18736 corresponding issuer. For an individual issuer for which a credit assessment by a nominated
18737 ECAI is not available, an institution using the approach referred to in the Credit Risk: Internal
18738 Ratings Based Approach (CRR) Part shall map the internal rating of the issuer to one of the
18739 external credit assessments.
18740 [Note: This rule corresponds to Article 325ak of CRR as it applied immediately before revocation by
18741 the Treasury]
18743 Article 325al CORRELATIONS FOR CREDIT SPREAD RISK FOR SECURITISATIONS
18744 INCLUDED IN THE ACTP
18745 1. An institution shall derive the delta risk correlation 𝜌 𝑘𝑙 in accordance with Article 325ai, except
18746 that, for the purposes of this paragraph, (𝑏𝑎𝑠𝑖𝑠) shall be equal to 1 where the two sensitivities
18747 𝜌 𝑘𝑙
18748 are related to the same curves, otherwise it shall be equal to 99.00%.
18749 2. An institution shall derive 𝛾 𝑏𝑐 in accordance with Article 325aj.
18750 [Note: This rule corresponds to Article 325al of CRR as it applied immediately before revocation by
18751 the Treasury]
18753 Article 325am RISK WEIGHTS FOR CREDIT SPREAD RISK FOR SECURITISATIONS
18754 NOT INCLUDED IN THE ACTP
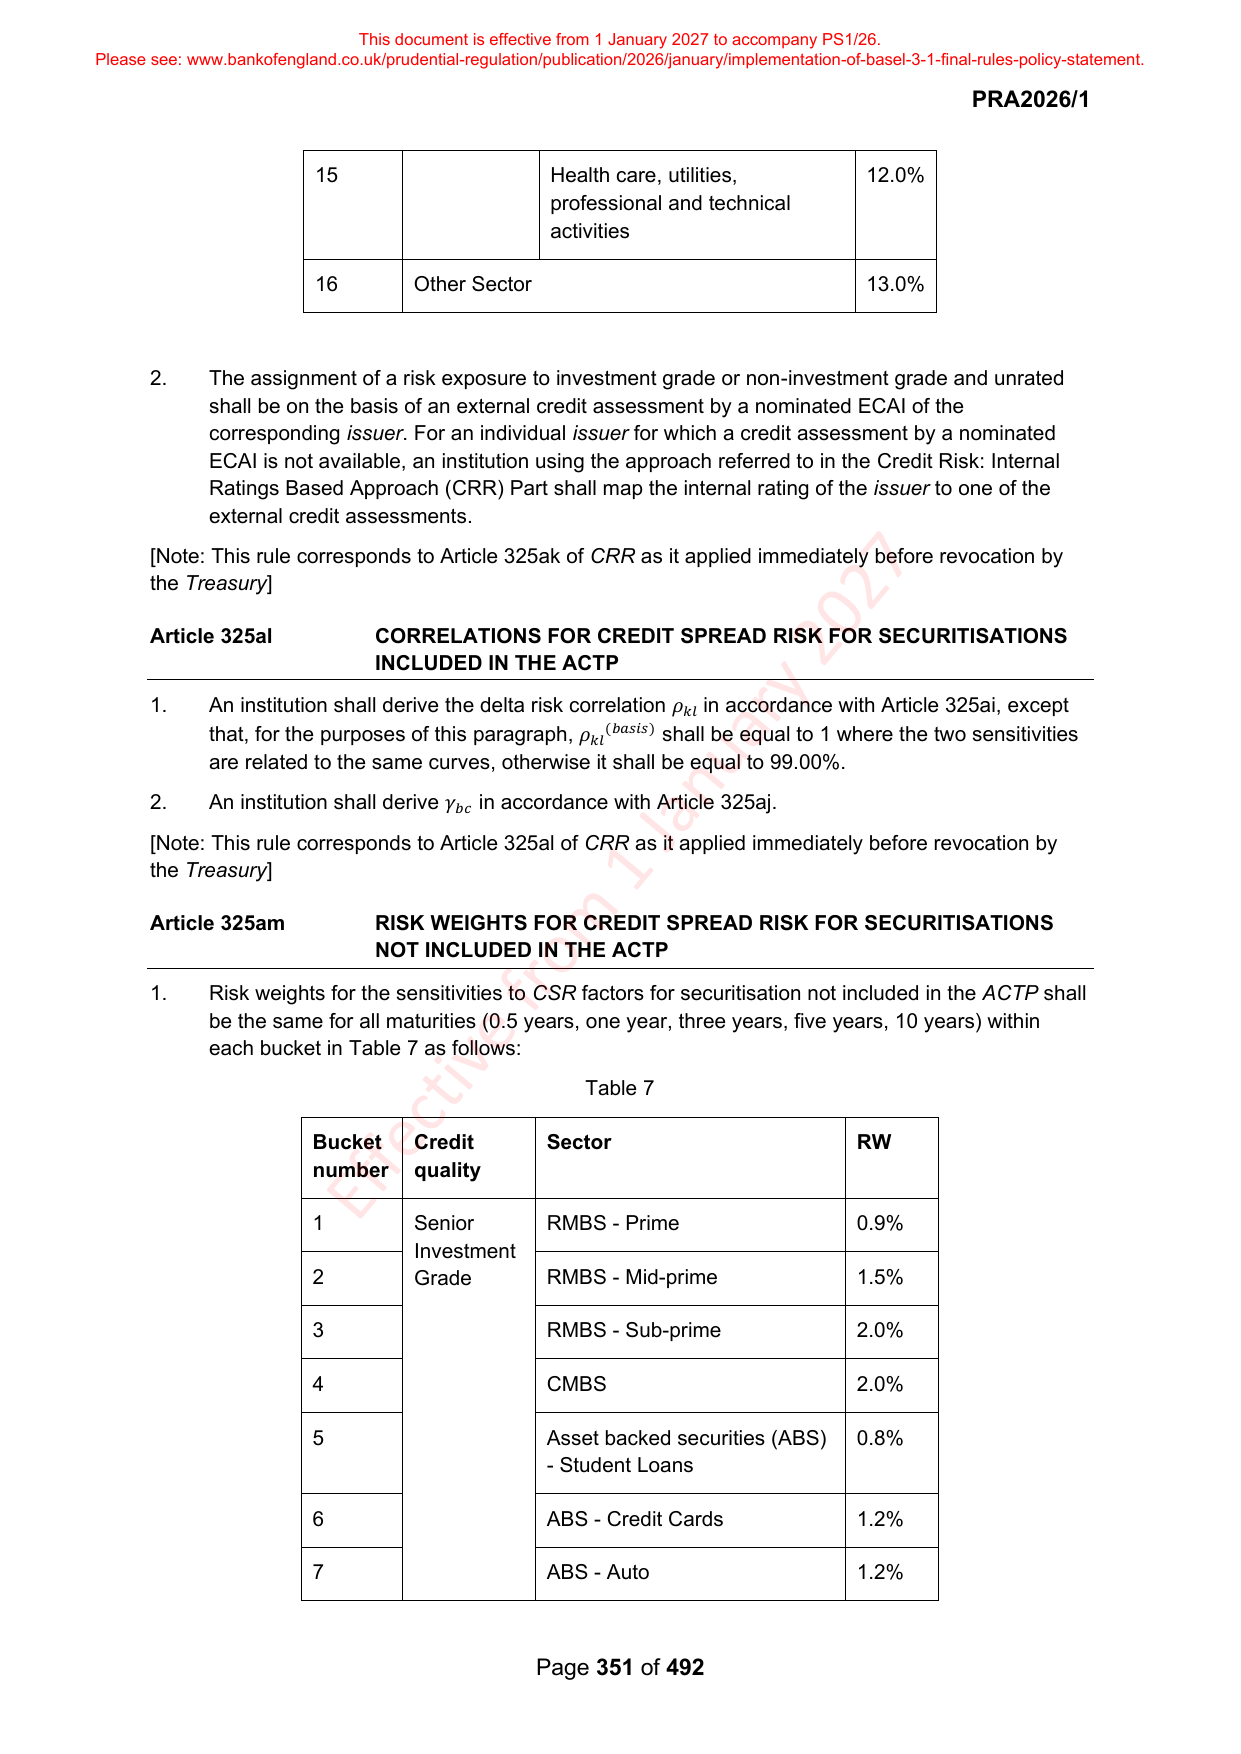
18756 1. Risk weights for the sensitivities to CSR factors for securitisation not included in the ACTP shall
18757 be the same for all maturities (0.5 years, one year, three years, five years, 10 years) within
18758 each bucket in Table 7 as follows:
18759 Table 7
18761 Bucket Credit Sector RW
18762 number quality
18764 1 Senior RMBS - Prime 0.9%
18765 Investment
18766 2 Grade RMBS - Mid-prime 1.5%
18768 3 RMBS - Sub-prime 2.0%
18770 4 CMBS 2.0%
18772 5 Asset backed securities (ABS) 0.8%
18773 - Student Loans
18775 6 ABS - Credit Cards 1.2%
18777 7 ABS - Auto 1.2%
18779 Page 351 of 492