18375 This document is effective from 1 January 2027 to accompany PS1/26.
18376Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
18377 PRA2026/1
18379 correlation 𝜌 𝑘𝑙 as equal to the correlation parameter specified in paragraph 2, multiplied by
18380 99.90%.
18381 4. Between any given weighted sensitivity of GIRR factors 𝑊𝑆 𝑘 and any given weighted sensitivity
18382 of inflation risk factors 𝑊𝑆 𝑙 , an institution shall set the correlation at 40%.
18383 5. Between any given weighted sensitivity of cross-currency basis risk factors 𝑊𝑆 𝑘 and any given
18384 weighted sensitivity of GIRR factors 𝑊𝑆 𝑙 , including another cross-currency basis risk factor, the
18385 correlation shall be set at 0%.
18386 6. Between any given weighted sensitivity of inflation risk factor 𝑊𝑆 𝑘 and any given weighted
18387 sensitivity of a different inflation risk factor in the same currency 𝑊𝑆 𝑙 , an institution shall set the
18388 correlation at 99.90%.
18389 [Note: Paragraphs 1 to 5 of this rule correspond to paragraphs 1 to 5 of Article 325af of CRR as
18390 applied immediately before revocation by the Treasury]
18392 Article 325ag CORRELATIONS ACROSS BUCKETS FOR GENERAL INTEREST RATE
18393 RISK
18394 1. An institution shall use the parameter 𝛾 𝑏𝑐 = 50% to aggregate risk factors belonging to different
18395 buckets.
18396 2. [Note: Provision left blank]
18397 [Note: Paragraph 1 of this rule corresponds to paragraph 1 of Article 325ag of CRR as it applied
18398 immediately before revocation by the Treasury]
18400 Article 325ah RISK WEIGHTS FOR CREDIT SPREAD RISK FOR NON-
18401 SECURITISATIONS
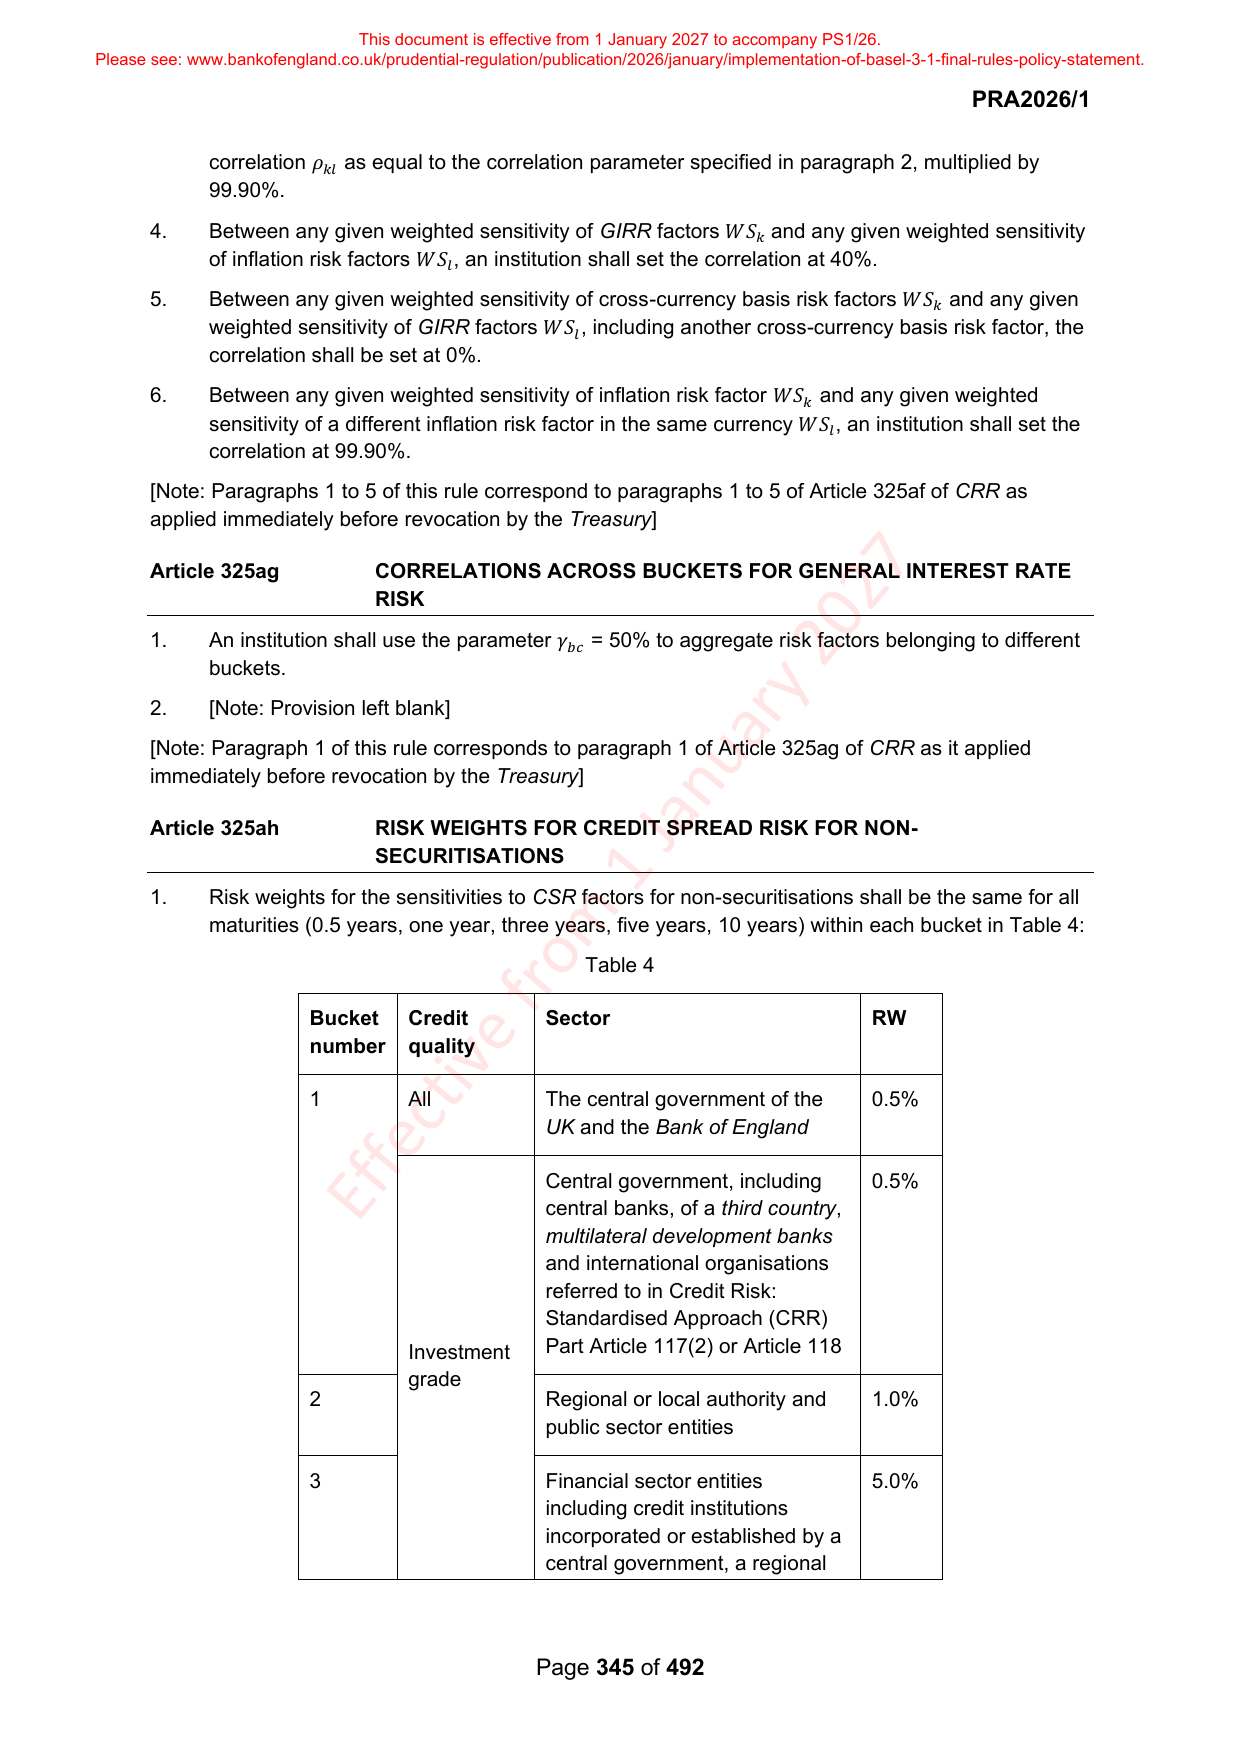
18402 1. Risk weights for the sensitivities to CSR factors for non-securitisations shall be the same for all
18403 maturities (0.5 years, one year, three years, five years, 10 years) within each bucket in Table 4:
18404 Table 4
18406 Bucket Credit Sector RW
18407 number quality
18409 1 All The central government of the 0.5%
18410 UK and the Bank of England
18412 Central government, including 0.5%
18413 central banks, of a third country,
18414 multilateral development banks
18415 and international organisations
18416 referred to in Credit Risk:
18417 Standardised Approach (CRR)
18418 Investment Part Article 117(2) or Article 118
18419 grade
18420 2 Regional or local authority and 1.0%
18421 public sector entities
18423 3 Financial sector entities 5.0%
18424 including credit institutions
18425 incorporated or established by a
18426 central government, a regional
18428 Page 345 of 492