18317 This document is effective from 1 January 2027 to accompany PS1/26.
18318Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
18319 PRA2026/1
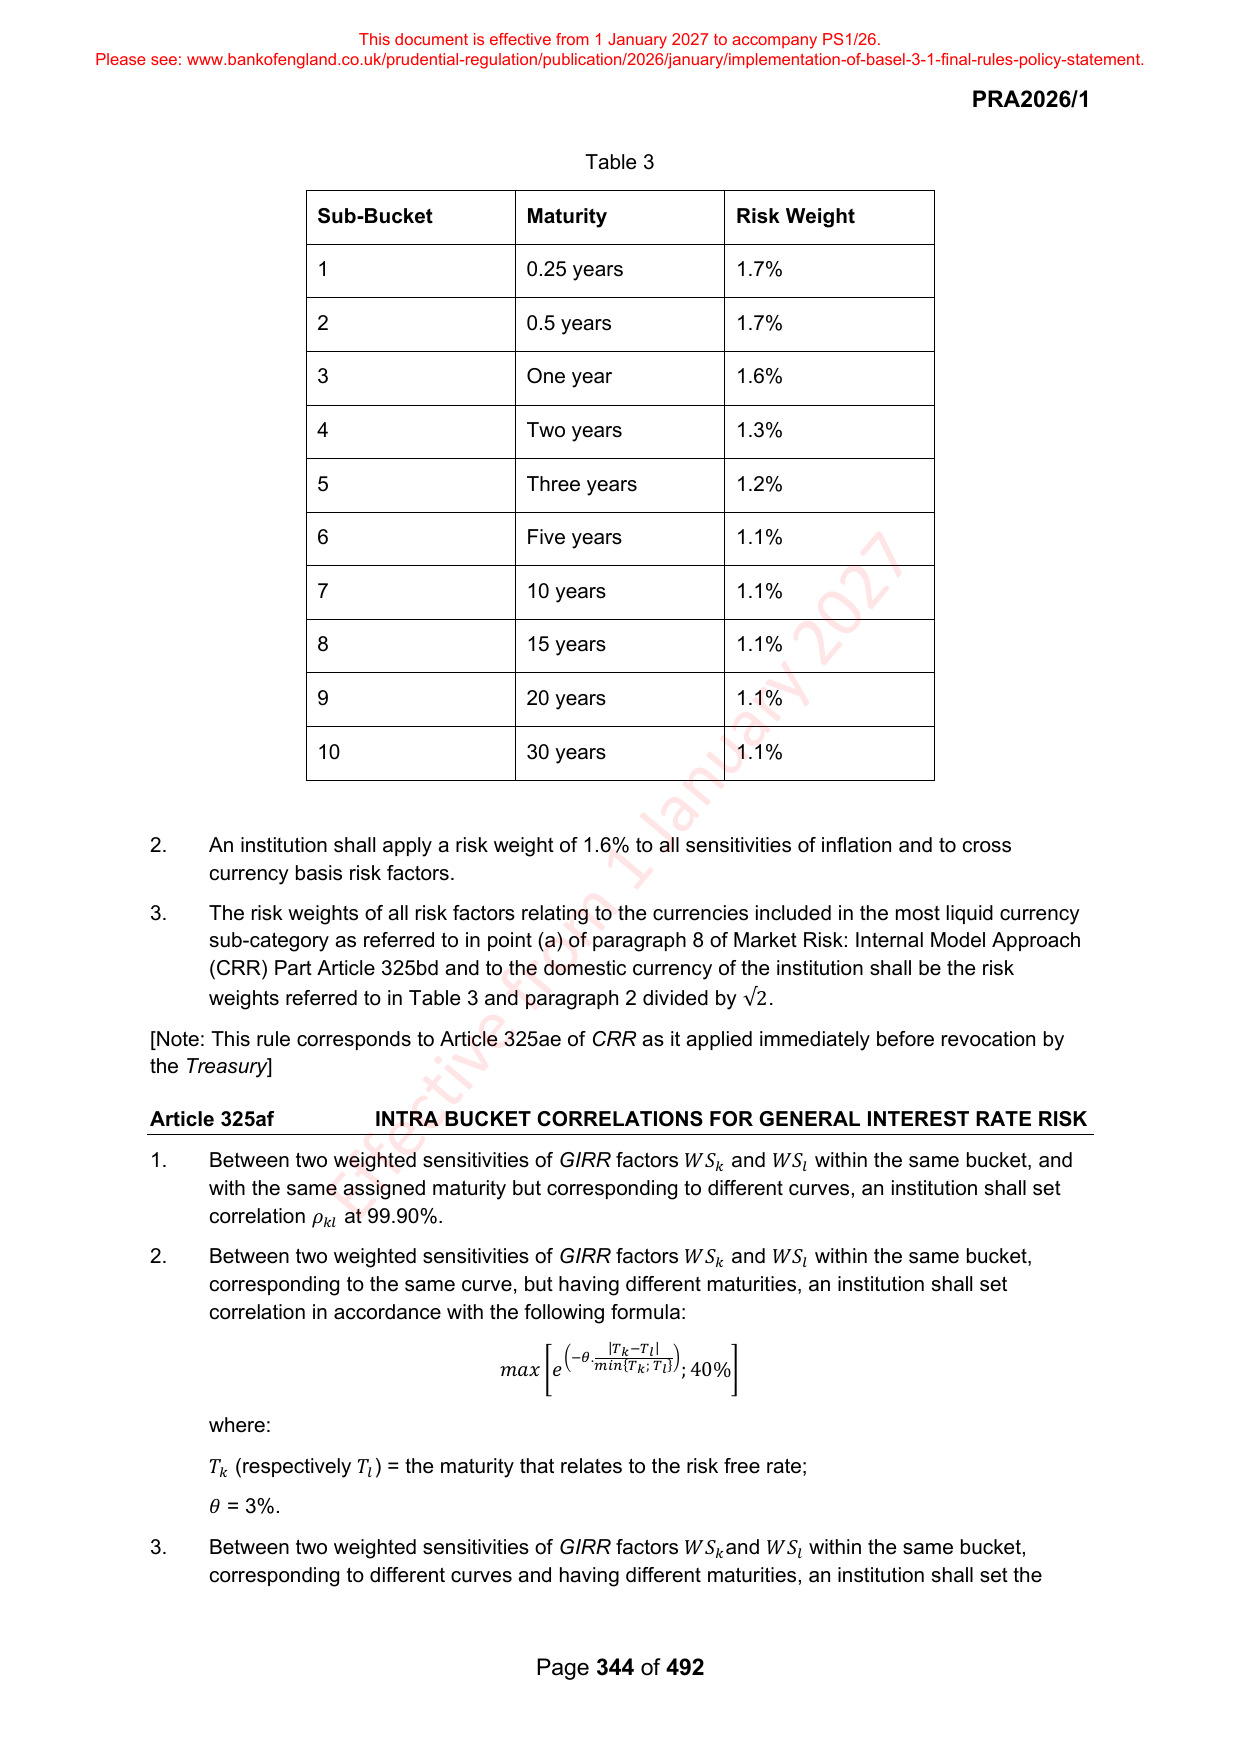
18321 Table 3
18323 Sub-Bucket Maturity Risk Weight
18325 1 0.25 years 1.7%
18327 2 0.5 years 1.7%
18329 3 One year 1.6%
18331 4 Two years 1.3%
18333 5 Three years 1.2%
18335 6 Five years 1.1%
18337 7 10 years 1.1%
18339 8 15 years 1.1%
18341 9 20 years 1.1%
18343 10 30 years 1.1%
18345 2. An institution shall apply a risk weight of 1.6% to all sensitivities of inflation and to cross
18346 currency basis risk factors.
18347 3. The risk weights of all risk factors relating to the currencies included in the most liquid currency
18348 sub-category as referred to in point (a) of paragraph 8 of Market Risk: Internal Model Approach
18349 (CRR) Part Article 325bd and to the domestic currency of the institution shall be the risk
18350 weights referred to in Table 3 and paragraph 2 divided by √2.
18351 [Note: This rule corresponds to Article 325ae of CRR as it applied immediately before revocation by
18352 the Treasury]
18354 Article 325af INTRA BUCKET CORRELATIONS FOR GENERAL INTEREST RATE RISK
18355 1. Between two weighted sensitivities of GIRR factors 𝑊𝑆 𝑘 and 𝑊𝑆 𝑙 within the same bucket, and
18356 with the same assigned maturity but corresponding to different curves, an institution shall set
18357 correlation 𝜌 𝑘𝑙 at 99.90%.
18358 2. Between two weighted sensitivities of GIRR factors 𝑊𝑆 𝑘 and 𝑊𝑆 𝑙 within the same bucket,
18359 corresponding to the same curve, but having different maturities, an institution shall set
18360 correlation in accordance with the following formula:
18361 |𝑇 𝑘 −𝑇 𝑙 |
18362 (−𝜃. )
18363 𝑚𝑎𝑥 [𝑒 𝑚𝑖𝑛{𝑇 𝑘 ; 𝑇 𝑙 } ; 40%]
18365 where:
18367 𝑇 𝑘 (respectively 𝑇 𝑙 ) = the maturity that relates to the risk free rate;
18369 𝜃 = 3%.
18371 3. Between two weighted sensitivities of GIRR factors 𝑊𝑆 𝑘 and 𝑊𝑆 𝑙 within the same bucket,
18372 corresponding to different curves and having different maturities, an institution shall set the
18374 Page 344 of 492