16770 This document is effective from 1 January 2027 to accompany PS1/26.
16771Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
16772 PRA2026/1
16774 𝑅𝑊 𝑘𝐶𝑢𝑟𝑣𝑎𝑡𝑢𝑟𝑒 = the risk weight applicable to risk factor 𝑘 determined in accordance with Section
16775 6;
16777 𝑠 𝑖𝑘 = the delta sensitivity of instrument 𝑖 with respect to risk factor 𝑘, calculated in accordance
16778 with Article 325r.
16779 3. By way of derogation from paragraph 2, for curves of risk factors that belong to the GIRR, CSR
16780 and commodity risk classes, an institution shall perform the calculations laid down in paragraph
16781 6 at the level of the entire curve instead of at the level of each risk factor that belongs to the
16782 curve.
16783 For the purposes of the calculation referred to in paragraph 2, where 𝑥 𝑘 is a curve of risk
16784 factors allocated to the GIRR, CSR and commodity risk classes, 𝑠 𝑖𝑘 shall be the sum of the
16785 delta sensitivities to the risk factor of the curve across all tenors of the curve.
16786 4. In order to determine a bucket-level own funds requirement for curvature risk, an institution
16787 shall aggregate, in accordance with the following formula the upward and downward net
16788 curvature risk positions, calculated in accordance with paragraph 2, of all the risk factors
16789 assigned to that bucket in accordance with Sub-section 1 of Section 3:
16791 max(𝐾 𝑏+ , 𝐾 𝑏− ) ; where 𝐾 𝑏+ ≠ 𝐾 𝑏−
16792 𝐾 𝑏 = { 𝐾 𝑏+ ; where 𝐾 𝑏+ = 𝐾 𝑏− and ∑ 𝐶𝑉𝑅 𝑘+ > ∑ 𝐶𝑉𝑅 𝑘−
16793 𝑘 𝑘
16794 𝐾 𝑏− ; otherwise
16795 where:
16797 𝑏 = the index that denotes a bucket of a given risk class;
16799 𝐾 𝑏 = the own funds requirement for curvature risk for bucket 𝑏;
16801 𝐾 𝑏+ = √max(0, ∑ max(𝐶𝑉𝑅 𝑘+ , 0) 2 + ∑ ∑ 𝜌 𝐶𝑉𝑅 𝑘+ 𝐶𝑉𝑅 𝑙+ 𝜓(𝐶𝑉𝑅 𝑘+ , 𝐶𝑉𝑅 𝑙+ ) );
16802 𝑘 𝑙≠𝑘 𝑘 𝑘𝑙
16804 𝐾 𝑏− = √max(0, ∑ max(𝐶𝑉𝑅 𝑘− , 0) 2 + ∑ ∑ 𝜌 𝐶𝑉𝑅 𝑘− 𝐶𝑉𝑅 𝑙− 𝜓(𝐶𝑉𝑅 𝑘− , 𝐶𝑉𝑅 𝑙− ) );
16805 𝑘 𝑙≠𝑘 𝑘 𝑘𝑙
16807 0; where 𝑥 < 0 and 𝑦 < 0
16808 𝜓(𝑥, 𝑦) = { ;
16809 1; otherwise
16811 𝜌 𝑘𝑙 = the intra-bucket correlations between risk factors 𝑘 and 𝑙 as prescribed in Section 6;
16813 𝑘, 𝑙 = the indices that denote all the risk factors 𝑘 and 𝑙 as included in one or more instruments
16814 referred to in paragraph 1;
16816 𝐶𝑉𝑅 𝑘+ = the upward net curvature risk position;
16818 𝐶𝑉𝑅 𝑘− = the downward net curvature risk position.
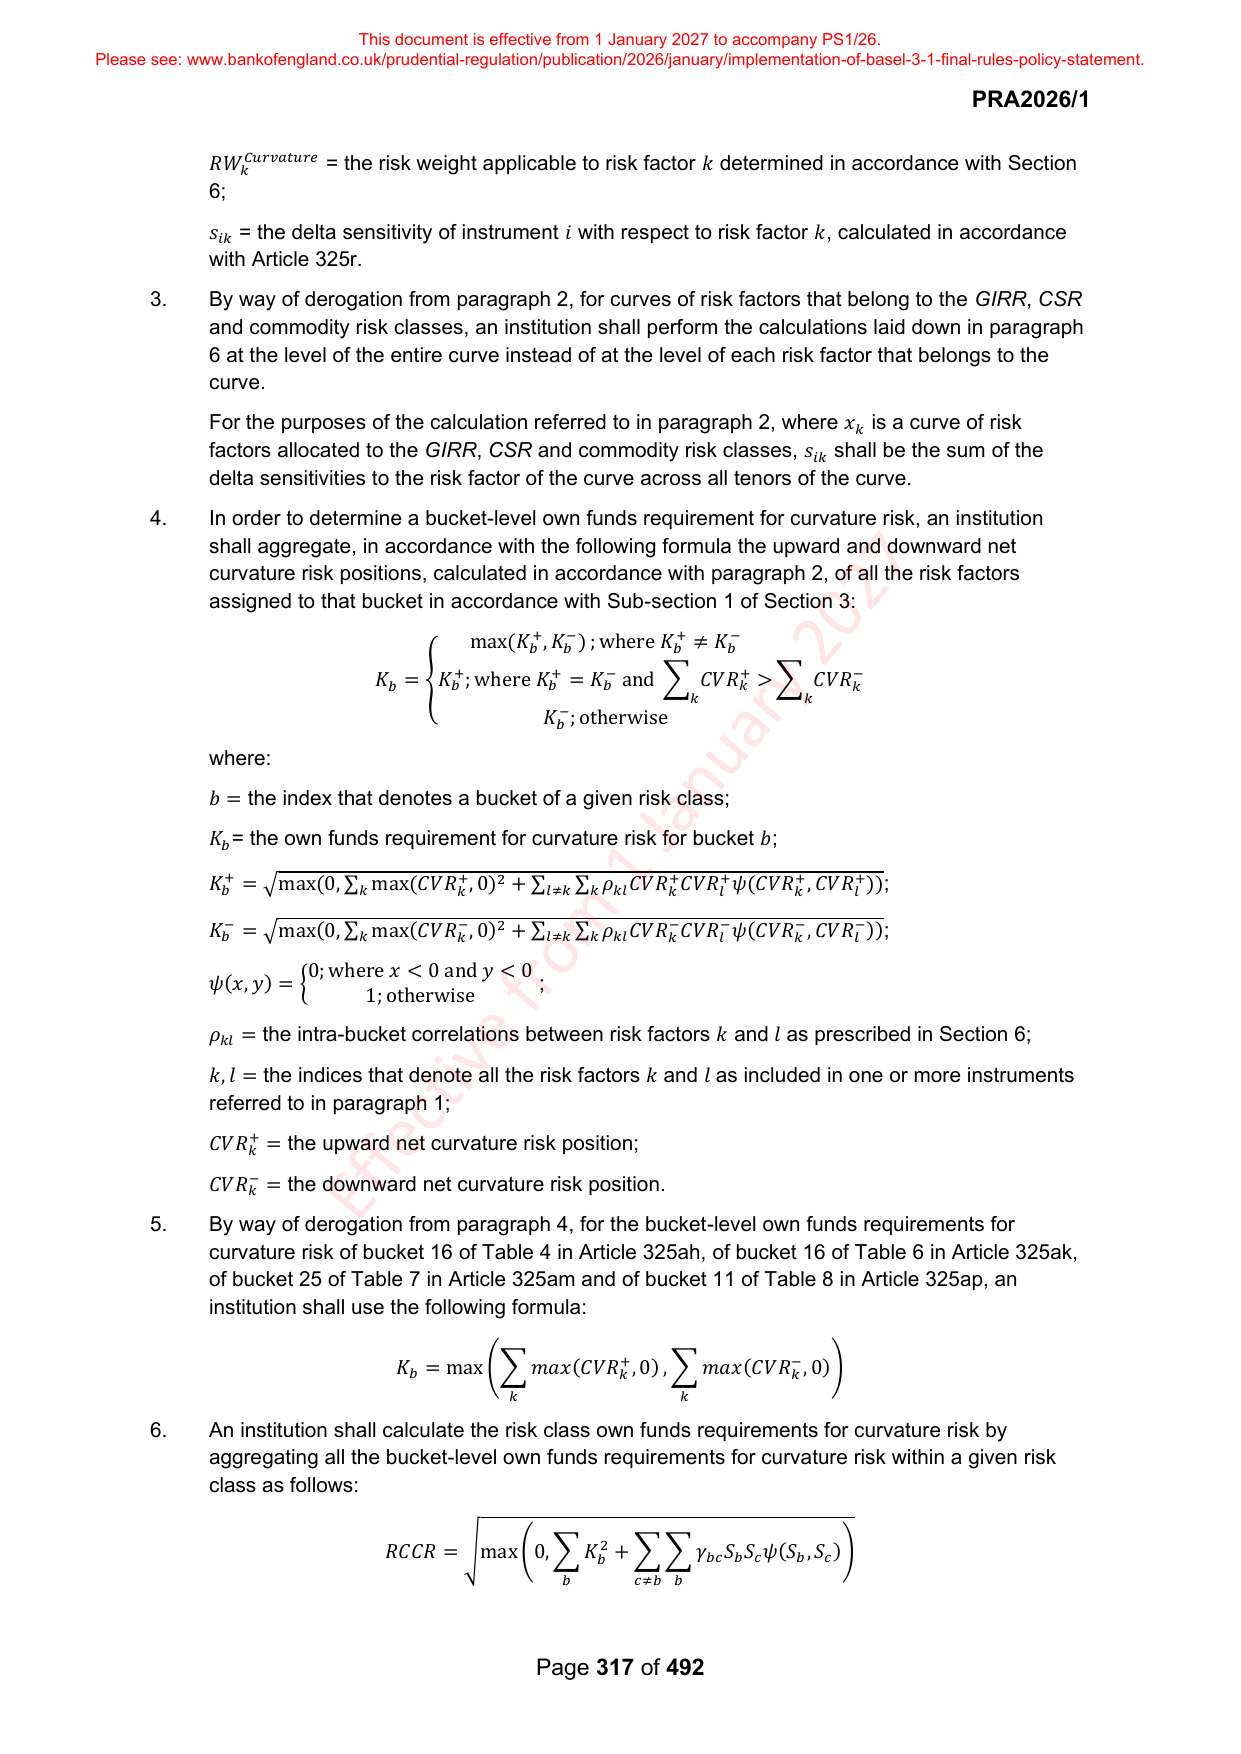
16819 5. By way of derogation from paragraph 4, for the bucket-level own funds requirements for
16820 curvature risk of bucket 16 of Table 4 in Article 325ah, of bucket 16 of Table 6 in Article 325ak,
16821 of bucket 25 of Table 7 in Article 325am and of bucket 11 of Table 8 in Article 325ap, an
16822 institution shall use the following formula:
16824 𝐾 𝑏 = max (∑ 𝑚𝑎𝑥(𝐶𝑉𝑅 𝑘+ , 0) , ∑ 𝑚𝑎𝑥(𝐶𝑉𝑅 𝑘− , 0) )
16825 𝑘 𝑘
16827 6. An institution shall calculate the risk class own funds requirements for curvature risk by
16828 aggregating all the bucket-level own funds requirements for curvature risk within a given risk
16829 class as follows:
16831 𝑅𝐶𝐶𝑅 = √max (0, ∑ 𝐾 𝑏2 + ∑ ∑ 𝛾 𝑏𝑐 𝑆 𝑏 𝑆 𝑐 𝜓(𝑆 𝑏 , 𝑆 𝑐 ) )
16832 𝑏 𝑐≠𝑏 𝑏
16834 Page 317 of 492