16704 This document is effective from 1 January 2027 to accompany PS1/26.
16705Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
16706 PRA2026/1
16708 where:
16710 𝑆 𝑏 = ∑ 𝑘 𝑊𝑆 𝑘 for all risk factors in bucket b and 𝑆 𝑐 = ∑ 𝑘 𝑊𝑆 𝑘 in bucket c; where those values for
16711 𝑆 𝑏 and 𝑆 𝑐 produce a negative number for the overall sum of ∑ 𝑏 𝐾 𝑏2 + ∑ 𝑏 ∑ 𝑐≠𝑏 𝛾 𝑏𝑐 𝑆 𝑏 𝑆 𝑐 the
16712 institution shall calculate the risk class-specific own funds requirements for delta or vega risk
16713 using an alternative specification whereby:
16715 𝑆 𝑏 = max [min (∑ 𝑊𝑆 𝑘 , 𝐾 𝑏 ), −𝐾 𝑏 ]
16716 𝑘
16718 𝑆 𝑐 = max [min (∑ 𝑊𝑆 𝑘 , 𝐾 𝑐 ), −𝐾 𝑐 ]
16719 𝑘
16721 The risk class-specific own funds requirements for delta or vega risk shall be calculated for
16722 each risk class in accordance with paragraphs 1 to 8.
16723 [Note: This rule corresponds to Article 325f of CRR as it applied immediately before revocation by the
16724 Treasury]
16726 Article 325g OWN FUNDS REQUIREMENTS FOR CURVATURE RISK
16728 1. An institution shall perform the calculations laid down in paragraph 2 for each risk factor of the
16729 instruments subject to the own funds requirement for curvature risk, except for the risk factors
16730 referred to in paragraph 3.
16731 For a given risk factor, an institution shall perform those calculations on a net basis across all
16732 the positions of the instruments subject to the own funds requirement for curvature risk that
16733 contain that risk factor.
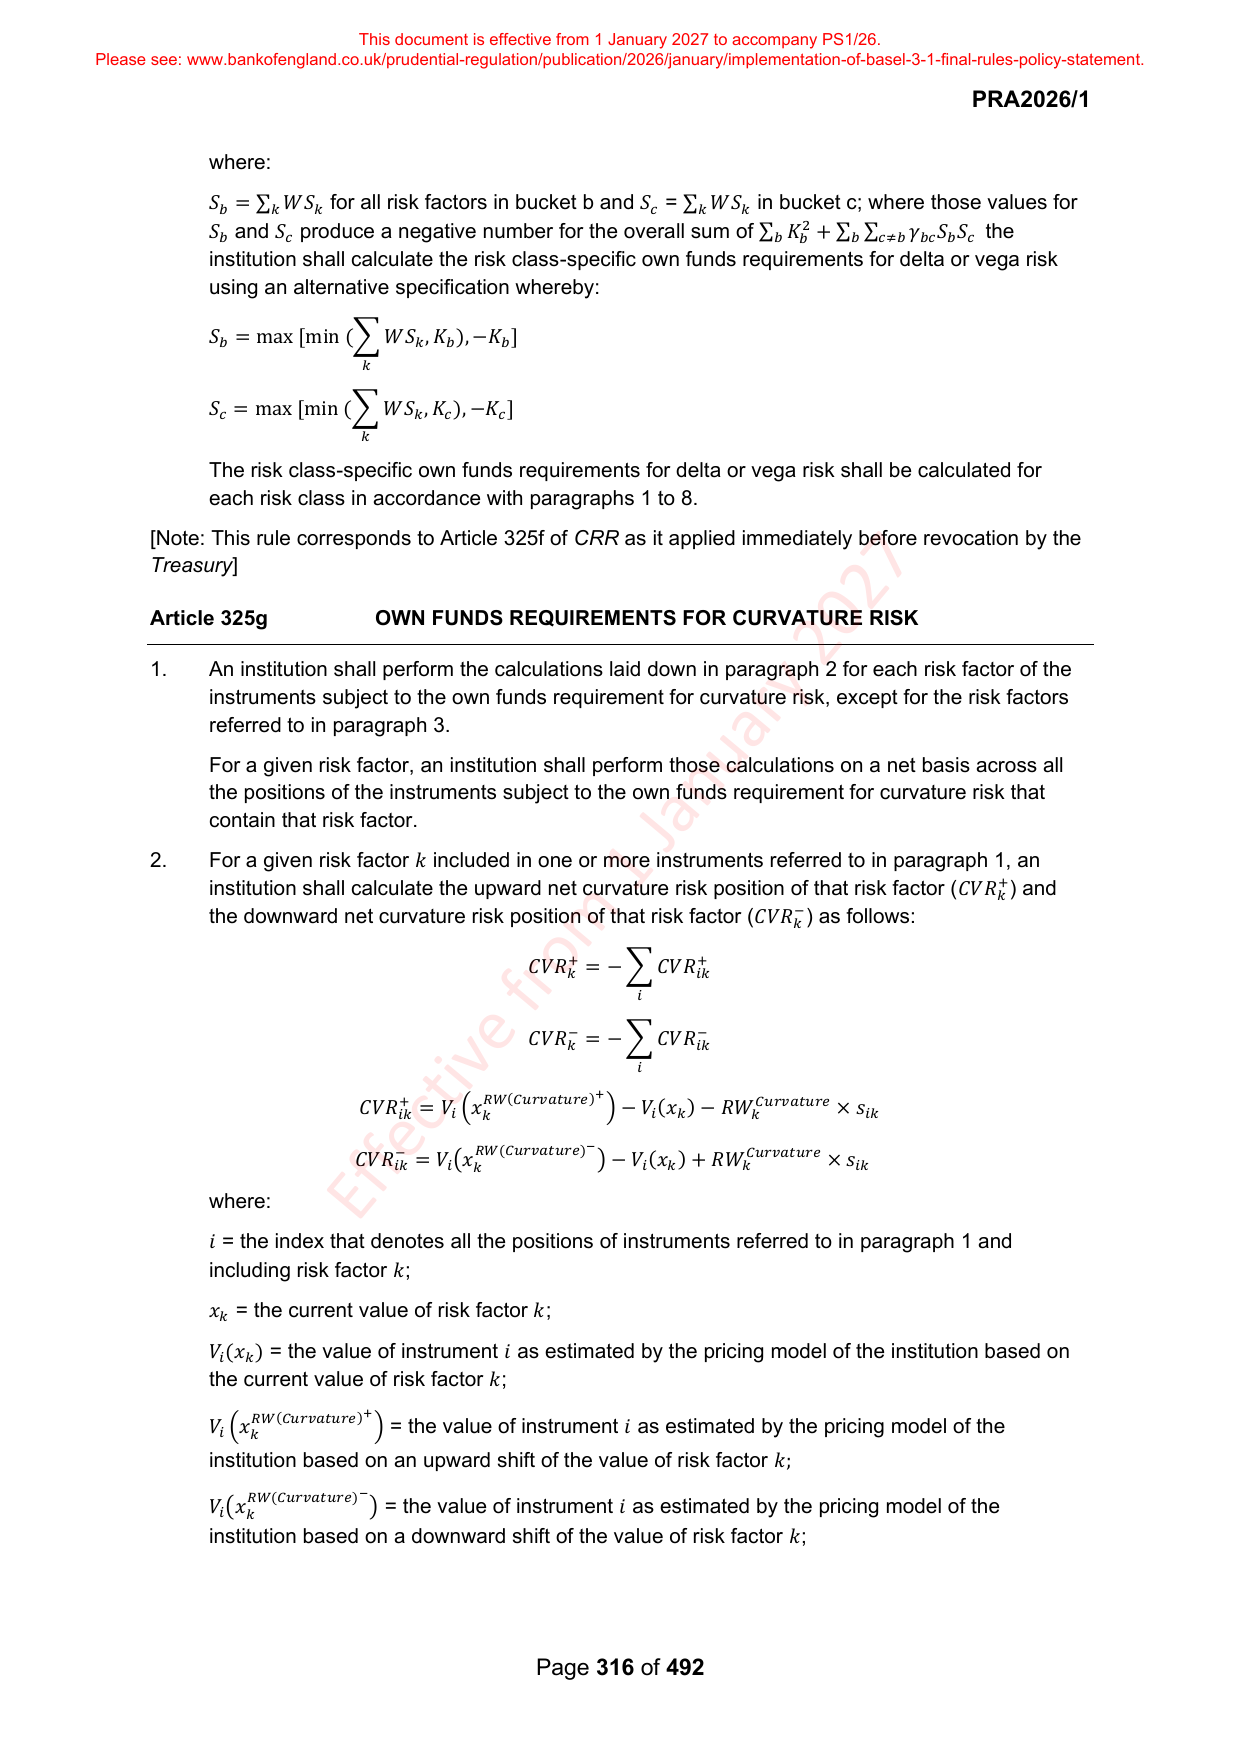
16734 2. For a given risk factor 𝑘 included in one or more instruments referred to in paragraph 1, an
16735 institution shall calculate the upward net curvature risk position of that risk factor (𝐶𝑉𝑅 𝑘+ ) and
16736 the downward net curvature risk position of that risk factor (𝐶𝑉𝑅 𝑘− ) as follows:
16738 +
16739 𝐶𝑉𝑅 𝑘+ = − ∑ 𝐶𝑉𝑅 𝑖𝑘
16740 𝑖
16742 −
16743 𝐶𝑉𝑅 𝑘− = − ∑ 𝐶𝑉𝑅 𝑖𝑘
16744 𝑖
16746 𝑅𝑊(𝐶𝑢𝑟𝑣𝑎𝑡𝑢𝑟𝑒) +
16747 + (𝑥 )
16748 𝐶𝑉𝑅 𝑖𝑘 = 𝑉 𝑖 (𝑥 𝑘 ) − 𝑉 𝑖 𝑘 − 𝑅𝑊 𝑘𝐶𝑢𝑟𝑣𝑎𝑡𝑢𝑟𝑒 × 𝑠 𝑖𝑘
16750 −
16751 − (𝑥 )
16752 𝐶𝑉𝑅 𝑖𝑘 = 𝑉 𝑖 (𝑥 𝑘𝑅𝑊(𝐶𝑢𝑟𝑣𝑎𝑡𝑢𝑟𝑒) ) − 𝑉 𝑖 𝑘 + 𝑅𝑊 𝑘𝐶𝑢𝑟𝑣𝑎𝑡𝑢𝑟𝑒 × 𝑠 𝑖𝑘
16753 where:
16755 𝑖 = the index that denotes all the positions of instruments referred to in paragraph 1 and
16756 including risk factor 𝑘;
16758 𝑥 𝑘 = the current value of risk factor 𝑘;
16760 𝑉 𝑖 (𝑥 𝑘 ) = the value of instrument 𝑖 as estimated by the pricing model of the institution based on
16761 the current value of risk factor 𝑘;
16762 +
16763 𝑉 𝑖 (𝑥 𝑘𝑅𝑊(𝐶𝑢𝑟𝑣𝑎𝑡𝑢𝑟𝑒) ) = the value of instrument 𝑖 as estimated by the pricing model of the
16764 institution based on an upward shift of the value of risk factor 𝑘;
16765 −
16766 𝑉 𝑖 (𝑥 𝑘𝑅𝑊(𝐶𝑢𝑟𝑣𝑎𝑡𝑢𝑟𝑒) ) = the value of instrument 𝑖 as estimated by the pricing model of the
16767 institution based on a downward shift of the value of risk factor 𝑘;
16769 Page 316 of 492