5171 This document is effective from 1 January 2027 to accompany PS1/26.
5172Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
5173 PRA2026/1
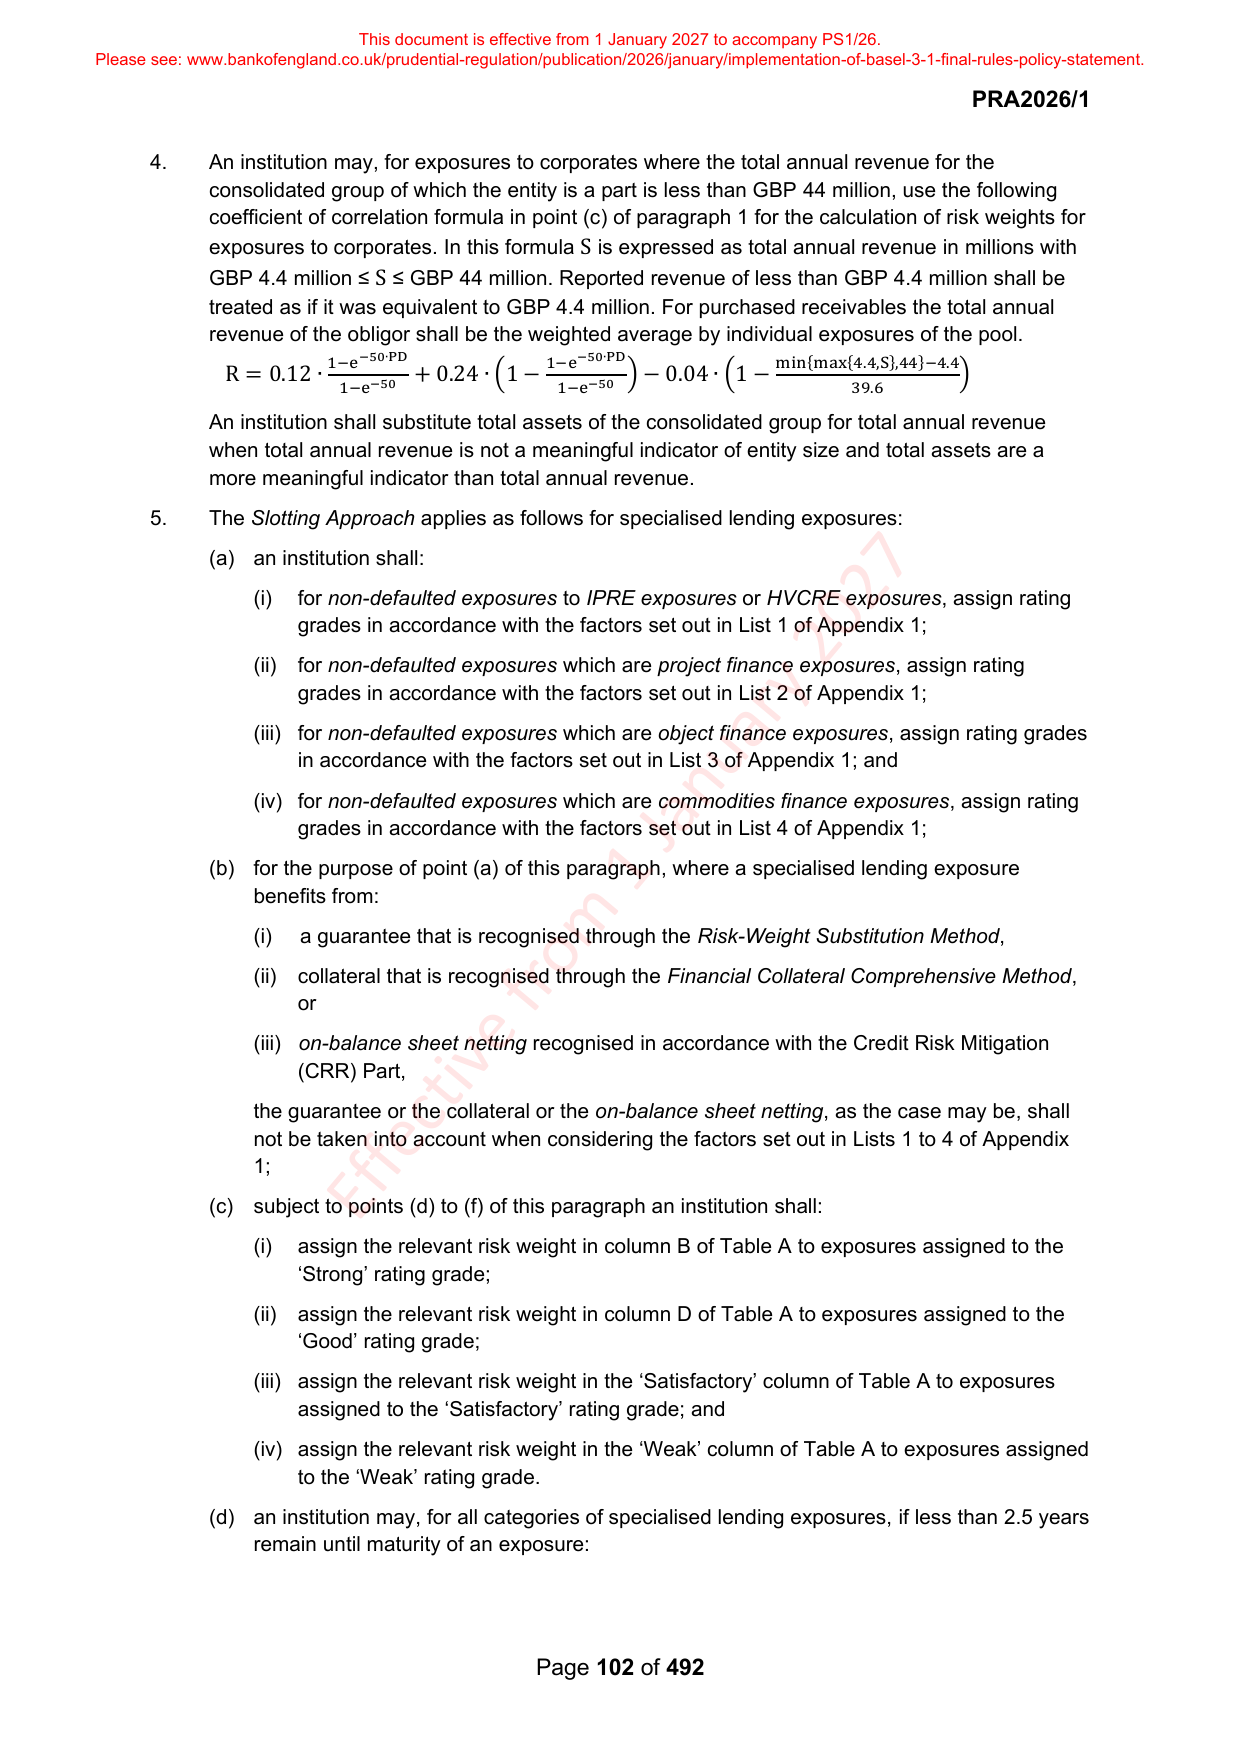
5175 4. An institution may, for exposures to corporates where the total annual revenue for the
5176 consolidated group of which the entity is a part is less than GBP 44 million, use the following
5177 coefficient of correlation formula in point (c) of paragraph 1 for the calculation of risk weights for
5178 exposures to corporates. In this formula S is expressed as total annual revenue in millions with
5179 GBP 4.4 million ≤ S ≤ GBP 44 million. Reported revenue of less than GBP 4.4 million shall be
5180 treated as if it was equivalent to GBP 4.4 million. For purchased receivables the total annual
5181 revenue of the obligor shall be the weighted average by individual exposures of the pool.
5182 1−e −50∙PD 1−e −50∙PD min{max{4.4,S},44}−4.4
5183 R = 0.12 ∙ −50 + 0.24 ∙ (1 − −50 ) − 0.04 ∙ (1 − )
5184 1−e 1−e 39.6
5186 An institution shall substitute total assets of the consolidated group for total annual revenue
5187 when total annual revenue is not a meaningful indicator of entity size and total assets are a
5188 more meaningful indicator than total annual revenue.
5189 5. The Slotting Approach applies as follows for specialised lending exposures:
5190 (a) an institution shall:
5191 (i) for non-defaulted exposures to IPRE exposures or HVCRE exposures, assign rating
5192 grades in accordance with the factors set out in List 1 of Appendix 1;
5193 (ii) for non-defaulted exposures which are project finance exposures, assign rating
5194 grades in accordance with the factors set out in List 2 of Appendix 1;
5195 (iii) for non-defaulted exposures which are object finance exposures, assign rating grades
5196 in accordance with the factors set out in List 3 of Appendix 1; and
5197 (iv) for non-defaulted exposures which are commodities finance exposures, assign rating
5198 grades in accordance with the factors set out in List 4 of Appendix 1;
5199 (b) for the purpose of point (a) of this paragraph, where a specialised lending exposure
5200 benefits from:
5201 (i) a guarantee that is recognised through the Risk-Weight Substitution Method,
5202 (ii) collateral that is recognised through the Financial Collateral Comprehensive Method,
5203 or
5204 (iii) on-balance sheet netting recognised in accordance with the Credit Risk Mitigation
5205 (CRR) Part,
5206 the guarantee or the collateral or the on-balance sheet netting, as the case may be, shall
5207 not be taken into account when considering the factors set out in Lists 1 to 4 of Appendix
5208 1;
5209 (c) subject to points (d) to (f) of this paragraph an institution shall:
5210 (i) assign the relevant risk weight in column B of Table A to exposures assigned to the
5211 ‘Strong’ rating grade;
5212 (ii) assign the relevant risk weight in column D of Table A to exposures assigned to the
5213 ‘Good’ rating grade;
5214 (iii) assign the relevant risk weight in the ‘Satisfactory’ column of Table A to exposures
5215 assigned to the ‘Satisfactory’ rating grade; and
5216 (iv) assign the relevant risk weight in the ‘Weak’ column of Table A to exposures assigned
5217 to the ‘Weak’ rating grade.
5218 (d) an institution may, for all categories of specialised lending exposures, if less than 2.5 years
5219 remain until maturity of an exposure:
5221 Page 102 of 492