5111 This document is effective from 1 January 2027 to accompany PS1/26.
5112Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
5113 PRA2026/1
5115 SUB-SECTION 2 CALCULATION OF RISK-WEIGHTED EXPOSURE AMOUNTS FOR
5116 CREDIT RISK
5117 Article 153 RISK-WEIGHTED EXPOSURE AMOUNTS FOR EXPOSURES TO CORPORATES
5118 AND INSTITUTIONS
5120 1. An institution shall, subject to the application of the specific treatments laid down in paragraphs
5121 2, 4, 5 and 5A, calculate the risk-weighted exposure amounts for exposures to corporates and
5122 institutions according to the following formulae:
5124 Risk-weighted exposure amount = RW ∙ exposure value
5125 where the risk weight (RW) is defined as:
5126 (a) [Note: Provision left blank]
5127 (b) if PD = 1, i.e., for defaulted exposures:
5128 — where an institution uses the Foundation IRB Approach, RW shall be 0;
5129 — where an institution uses the Advanced IRB Approach, RW shall be:
5131 RW = max (0, 12.5 ∙ (LGD − BEEL))
5133 where BEEL is the best estimate of expected loss (BEEL);
5134 (c) if PD < 1:
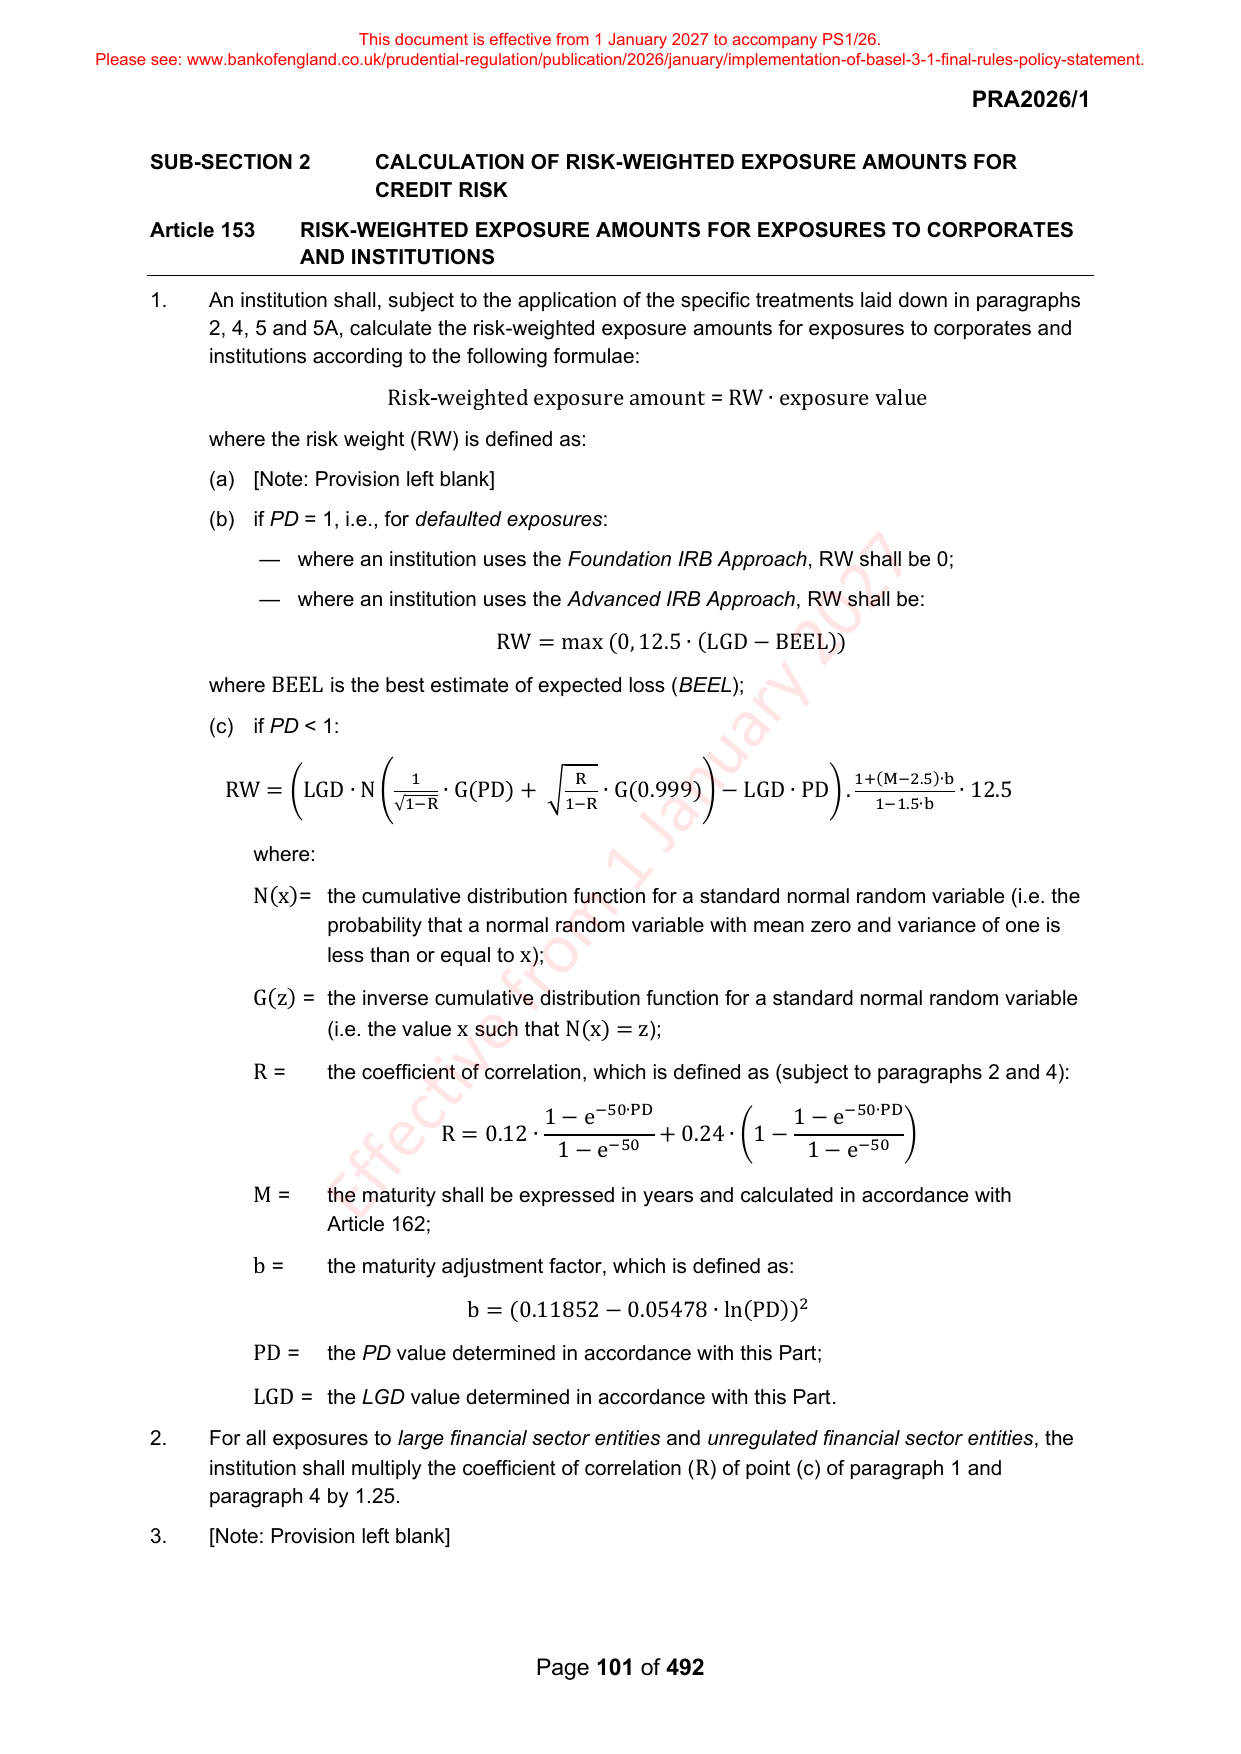
5136 1 R 1+(M−2.5)∙b
5137 RW = (LGD ∙ N ( ∙ G(PD) + √ ∙ G(0.999)) − LGD ∙ PD) . ∙ 12.5
5138 √1−R 1−R 1−1.5∙b
5140 where:
5142 N(x) = the cumulative distribution function for a standard normal random variable (i.e. the
5143 probability that a normal random variable with mean zero and variance of one is
5144 less than or equal to x );
5146 G(z) = the inverse cumulative distribution function for a standard normal random variable
5147 (i.e. the value x such that N(x) = z );
5149 R = the coefficient of correlation, which is defined as (subject to paragraphs 2 and 4):
5150 −50∙PD −50∙PD
5151 1 − e 1 − e
5152 R = 0.12 ∙ + 0.24 ∙ (1 − )
5153 1 − e −50 1 − e −50
5155 M = the maturity shall be expressed in years and calculated in accordance with
5156 Article 162;
5158 b = the maturity adjustment factor, which is defined as:
5159 2
5160 b = (0.11852 − 0.05478 ∙ ln(PD))
5162 PD = the PD value determined in accordance with this Part;
5164 LGD = the LGD value determined in accordance with this Part.
5165 2. For all exposures to large financial sector entities and unregulated financial sector entities, the
5166 institution shall multiply the coefficient of correlation ( R ) of point (c) of paragraph 1 and
5167 paragraph 4 by 1.25.
5168 3. [Note: Provision left blank]
5170 Page 101 of 492