22853 This document is effective from 1 January 2027 to accompany PS1/26.
22854Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
22855 PRA2026/1
22857 Component Formula
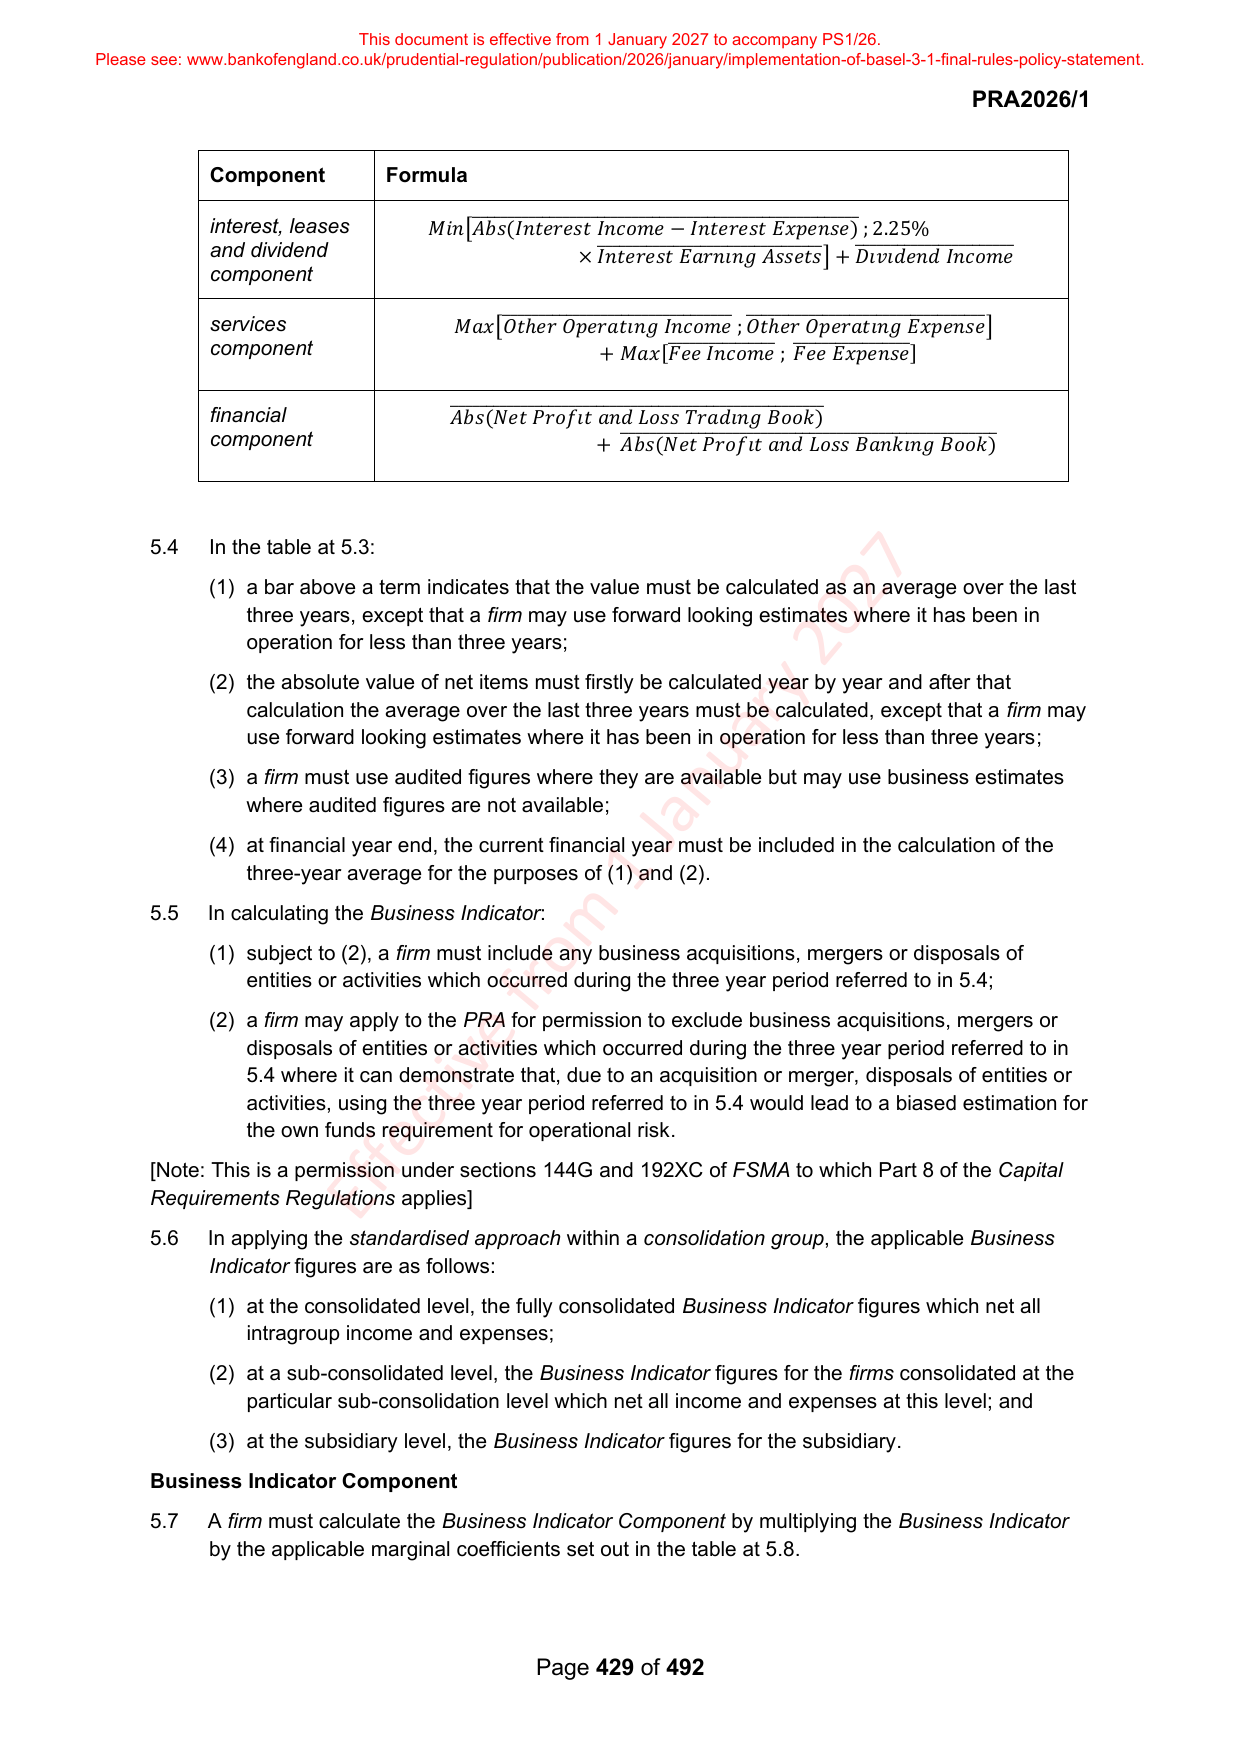
22859 interest, leases 𝑀𝑖𝑛[𝐴𝑏𝑠(𝐼𝑛𝑡𝑒𝑟𝑒𝑠𝑡 ̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅ 𝐼𝑛𝑐𝑜𝑚𝑒 − 𝐼𝑛𝑡𝑒𝑟𝑒𝑠𝑡 𝐸𝑥𝑝𝑒𝑛𝑠𝑒) ; 2.25%
22860 and dividend × ̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅ 𝐼𝑛𝑡𝑒𝑟𝑒𝑠𝑡 𝐸𝑎𝑟𝑛𝑖𝑛𝑔 𝐴𝑠𝑠𝑒𝑡𝑠 ] + ̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅ 𝐷𝑖𝑣𝑖𝑑𝑒𝑛𝑑 𝐼𝑛𝑐𝑜𝑚𝑒
22861 component
22863 services 𝑀𝑎𝑥[𝑂𝑡ℎ𝑒𝑟 ̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅ 𝑂𝑝𝑒𝑟𝑎𝑡𝑖𝑛𝑔 𝐼𝑛𝑐𝑜𝑚𝑒 ; ̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅ 𝑂𝑡ℎ𝑒𝑟 𝑂𝑝𝑒𝑟𝑎𝑡𝑖𝑛𝑔 𝐸𝑥𝑝𝑒𝑛𝑠𝑒 ]
22864 component + 𝑀𝑎𝑥[𝐹𝑒𝑒 ̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅ 𝐼𝑛𝑐𝑜𝑚𝑒 ; ̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅ 𝐹𝑒𝑒 𝐸𝑥𝑝𝑒𝑛𝑠𝑒 ]
22866 financial ̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅ 𝐴𝑏𝑠(𝑁𝑒𝑡 𝑃𝑟𝑜𝑓𝑖𝑡 𝑎𝑛𝑑 𝐿𝑜𝑠𝑠 𝑇𝑟𝑎𝑑𝑖𝑛𝑔 𝐵𝑜𝑜𝑘)
22867 component + ̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅̅ 𝐴𝑏𝑠(𝑁𝑒𝑡 𝑃𝑟𝑜𝑓𝑖𝑡 𝑎𝑛𝑑 𝐿𝑜𝑠𝑠 𝐵𝑎𝑛𝑘𝑖𝑛𝑔 𝐵𝑜𝑜𝑘)
22869 5.4 In the table at 5.3:
22870 (1) a bar above a term indicates that the value must be calculated as an average over the last
22871 three years, except that a firm may use forward looking estimates where it has been in
22872 operation for less than three years;
22873 (2) the absolute value of net items must firstly be calculated year by year and after that
22874 calculation the average over the last three years must be calculated, except that a firm may
22875 use forward looking estimates where it has been in operation for less than three years;
22876 (3) a firm must use audited figures where they are available but may use business estimates
22877 where audited figures are not available;
22878 (4) at financial year end, the current financial year must be included in the calculation of the
22879 three-year average for the purposes of (1) and (2).
22880 5.5 In calculating the Business Indicator:
22881 (1) subject to (2), a firm must include any business acquisitions, mergers or disposals of
22882 entities or activities which occurred during the three year period referred to in 5.4;
22883 (2) a firm may apply to the PRA for permission to exclude business acquisitions, mergers or
22884 disposals of entities or activities which occurred during the three year period referred to in
22885 5.4 where it can demonstrate that, due to an acquisition or merger, disposals of entities or
22886 activities, using the three year period referred to in 5.4 would lead to a biased estimation for
22887 the own funds requirement for operational risk.
22888 [Note: This is a permission under sections 144G and 192XC of FSMA to which Part 8 of the Capital
22889 Requirements Regulations applies]
22890 5.6 In applying the standardised approach within a consolidation group, the applicable Business
22891 Indicator figures are as follows:
22892 (1) at the consolidated level, the fully consolidated Business Indicator figures which net all
22893 intragroup income and expenses;
22894 (2) at a sub-consolidated level, the Business Indicator figures for the firms consolidated at the
22895 particular sub-consolidation level which net all income and expenses at this level; and
22896 (3) at the subsidiary level, the Business Indicator figures for the subsidiary.
22897 Business Indicator Component
22898 5.7 A firm must calculate the Business Indicator Component by multiplying the Business Indicator
22899 by the applicable marginal coefficients set out in the table at 5.8.
22901 Page 429 of 492