22415 This document is effective from 1 January 2027 to accompany PS1/26.
22416Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
22417 PRA2026/1
22419 current values and dividing the resulting change in the aggregate CVA, and the value of
22420 eligible SA-CVA hedges, by 0.01;
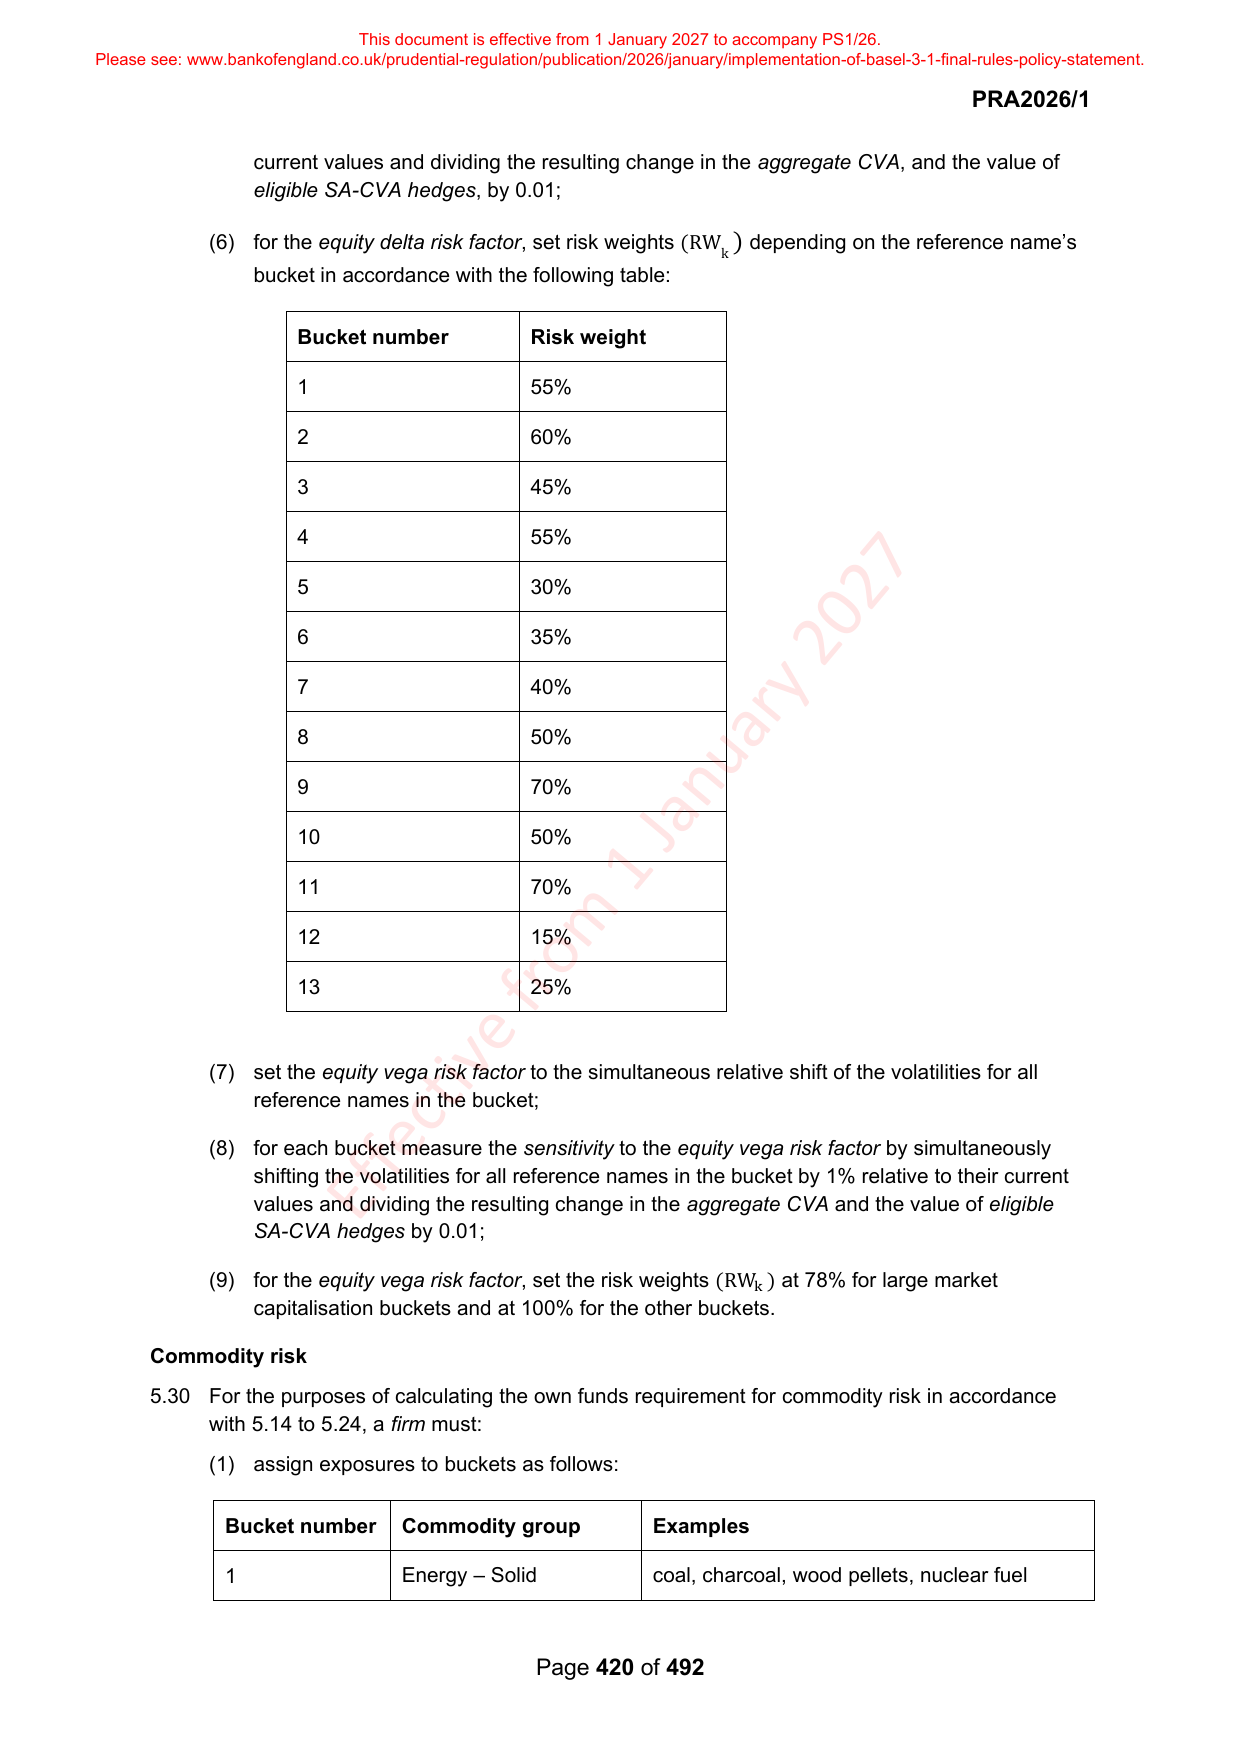
22422 (6) for the equity delta risk factor, set risk weights (RW ) depending on the reference name’s
22423 k
22424 bucket in accordance with the following table:
22426 Bucket number Risk weight
22428 1 55%
22430 2 60%
22432 3 45%
22434 4 55%
22436 5 30%
22438 6 35%
22440 7 40%
22442 8 50%
22444 9 70%
22446 10 50%
22448 11 70%
22450 12 15%
22452 13 25%
22454 (7) set the equity vega risk factor to the simultaneous relative shift of the volatilities for all
22455 reference names in the bucket;
22457 (8) for each bucket measure the sensitivity to the equity vega risk factor by simultaneously
22458 shifting the volatilities for all reference names in the bucket by 1% relative to their current
22459 values and dividing the resulting change in the aggregate CVA and the value of eligible
22460 SA-CVA hedges by 0.01;
22462 (9) for the equity vega risk factor, set the risk weights (RW k ) at 78% for large market
22463 capitalisation buckets and at 100% for the other buckets.
22465 Commodity risk
22466 5.30 For the purposes of calculating the own funds requirement for commodity risk in accordance
22467 with 5.14 to 5.24, a firm must:
22468 (1) assign exposures to buckets as follows:
22470 Bucket number Commodity group Examples
22472 1 Energy – Solid coal, charcoal, wood pellets, nuclear fuel
22474 Page 420 of 492