22230 This document is effective from 1 January 2027 to accompany PS1/26.
22231Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
22232 PRA2026/1
22234 (2) for reference credit spread delta risk and vega risk set the cross-bucket correlations (γ )
22235 bc
22236 for buckets (b, c):
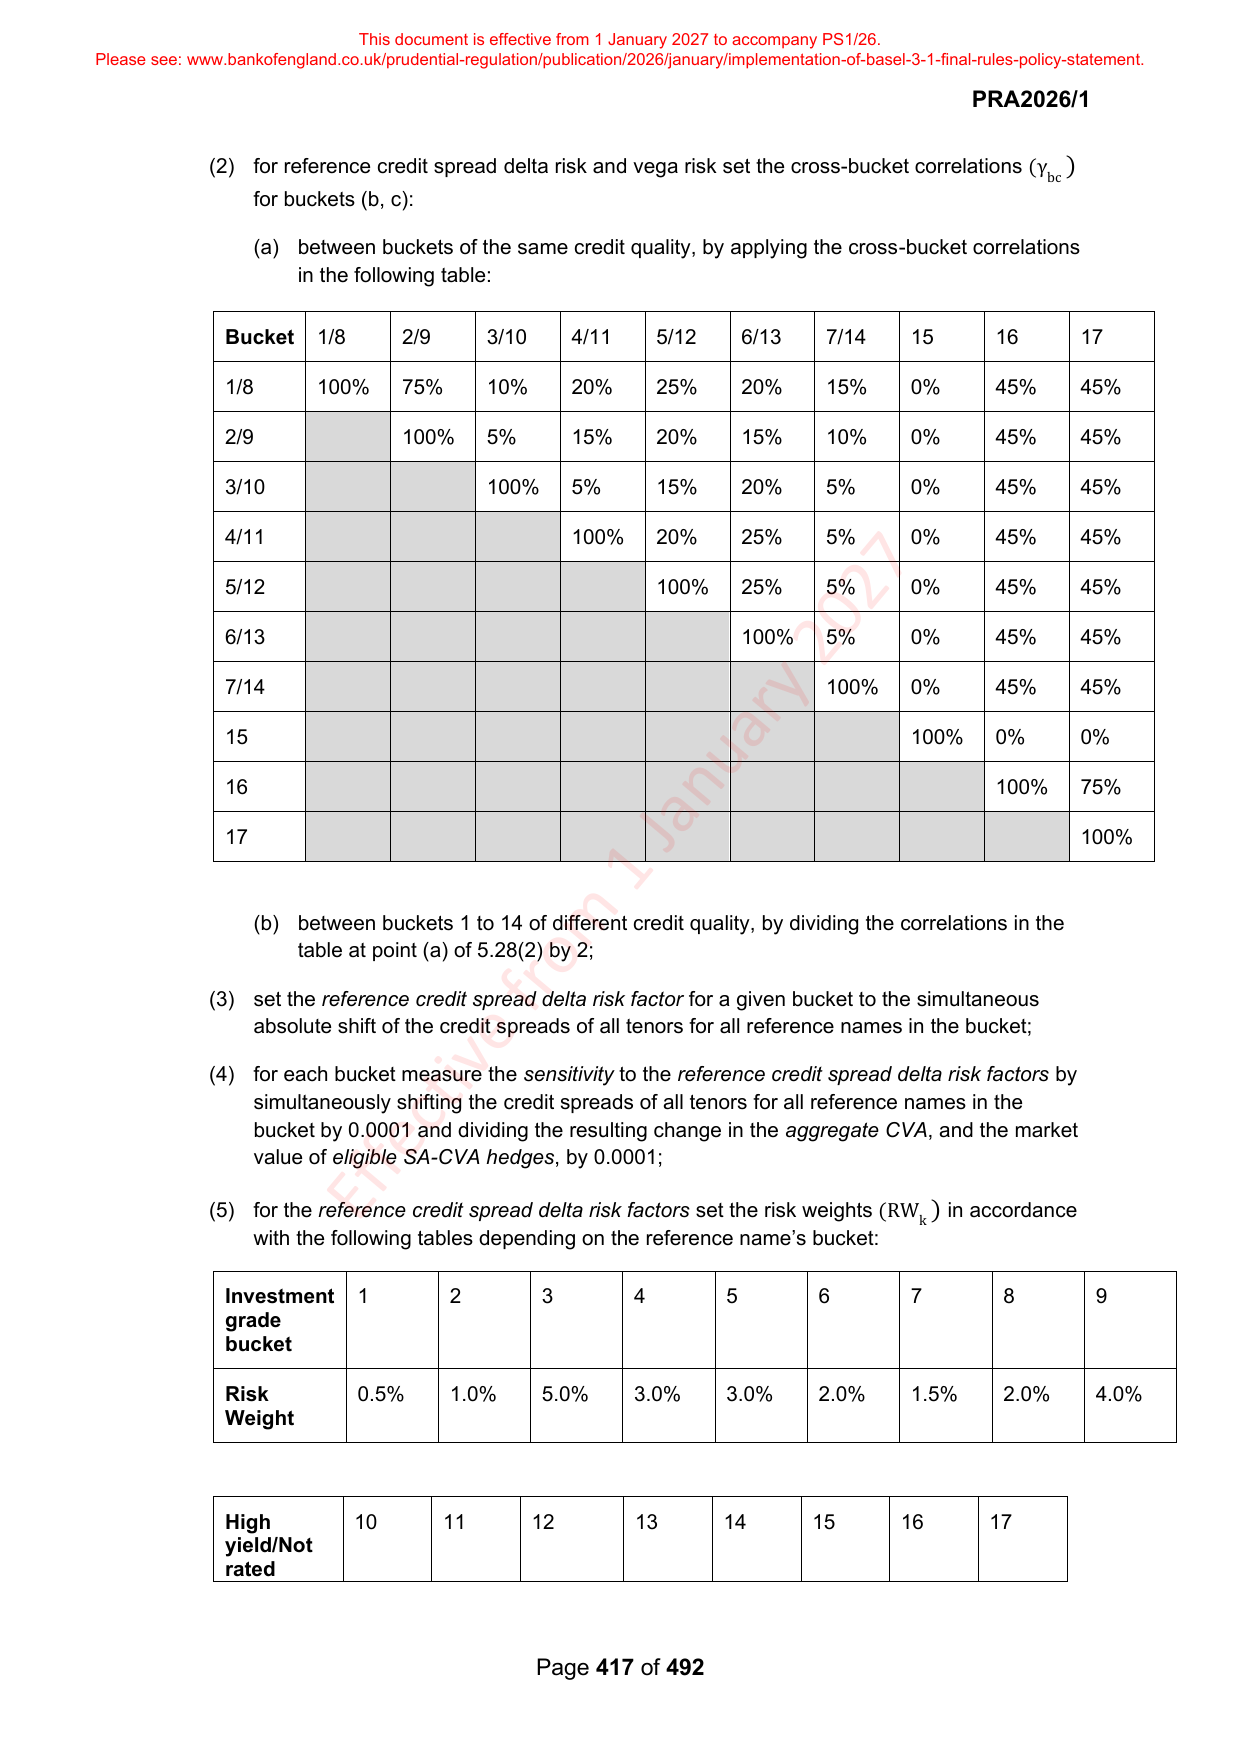
22238 (a) between buckets of the same credit quality, by applying the cross-bucket correlations
22239 in the following table:
22241 Bucket 1/8 2/9 3/10 4/11 5/12 6/13 7/14 15 16 17
22243 1/8 100% 75% 10% 20% 25% 20% 15% 0% 45% 45%
22245 2/9 100% 5% 15% 20% 15% 10% 0% 45% 45%
22247 3/10 100% 5% 15% 20% 5% 0% 45% 45%
22249 4/11 100% 20% 25% 5% 0% 45% 45%
22251 5/12 100% 25% 5% 0% 45% 45%
22253 6/13 100% 5% 0% 45% 45%
22255 7/14 100% 0% 45% 45%
22257 15 100% 0% 0%
22259 16 100% 75%
22261 17 100%
22263 (b) between buckets 1 to 14 of different credit quality, by dividing the correlations in the
22264 table at point (a) of 5.28(2) by 2;
22266 (3) set the reference credit spread delta risk factor for a given bucket to the simultaneous
22267 absolute shift of the credit spreads of all tenors for all reference names in the bucket;
22269 (4) for each bucket measure the sensitivity to the reference credit spread delta risk factors by
22270 simultaneously shifting the credit spreads of all tenors for all reference names in the
22271 bucket by 0.0001 and dividing the resulting change in the aggregate CVA, and the market
22272 value of eligible SA-CVA hedges, by 0.0001;
22274 (5) for the reference credit spread delta risk factors set the risk weights (RW ) in accordance
22275 k
22276 with the following tables depending on the reference name’s bucket:
22278 Investment 1 2 3 4 5 6 7 8 9
22279 grade
22280 bucket
22282 Risk 0.5% 1.0% 5.0% 3.0% 3.0% 2.0% 1.5% 2.0% 4.0%
22283 Weight
22285 High 10 11 12 13 14 15 16 17
22286 yield/Not
22287 rated
22289 Page 417 of 492