21402 This document is effective from 1 January 2027 to accompany PS1/26.
21403Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
21404 PRA2026/1
21406 RW iind is the supervisory risk weight of the index eligible BA-CVA hedge, as specified in the
21407 table at 4.4 but adjusted as follows:
21408 (1) for an index where all index constituents belong to the same sector and are of the same
21409 credit quality, the firm must multiply the relevant value in the table at 4.4 by 0.7;
21411 (2) for an index spanning multiple sectors or with a mixture of investment grade constituents
21412 and other grade constituents, the firm must calculate the name-weighted average of the
21413 risk weights from the table at 4.4 and then multiply by 0.7;
21415 i= the index that denotes all index hedges that the firm has taken out to hedge CVA risk.
21417 4.9 For the purposes of 4.6, a firm must calculate HMA C in accordance with the following formula:
21419 ∑ 2 2
21420 HMA C = h∊C (1 − r hc ) ∙ (RW h ∙ M hSN ∙ B hSN ∙ DF hSN )
21421 where:
21423 r hc , M hSN , B hSN , DF hSN , and RW h are as set out in 4.7.
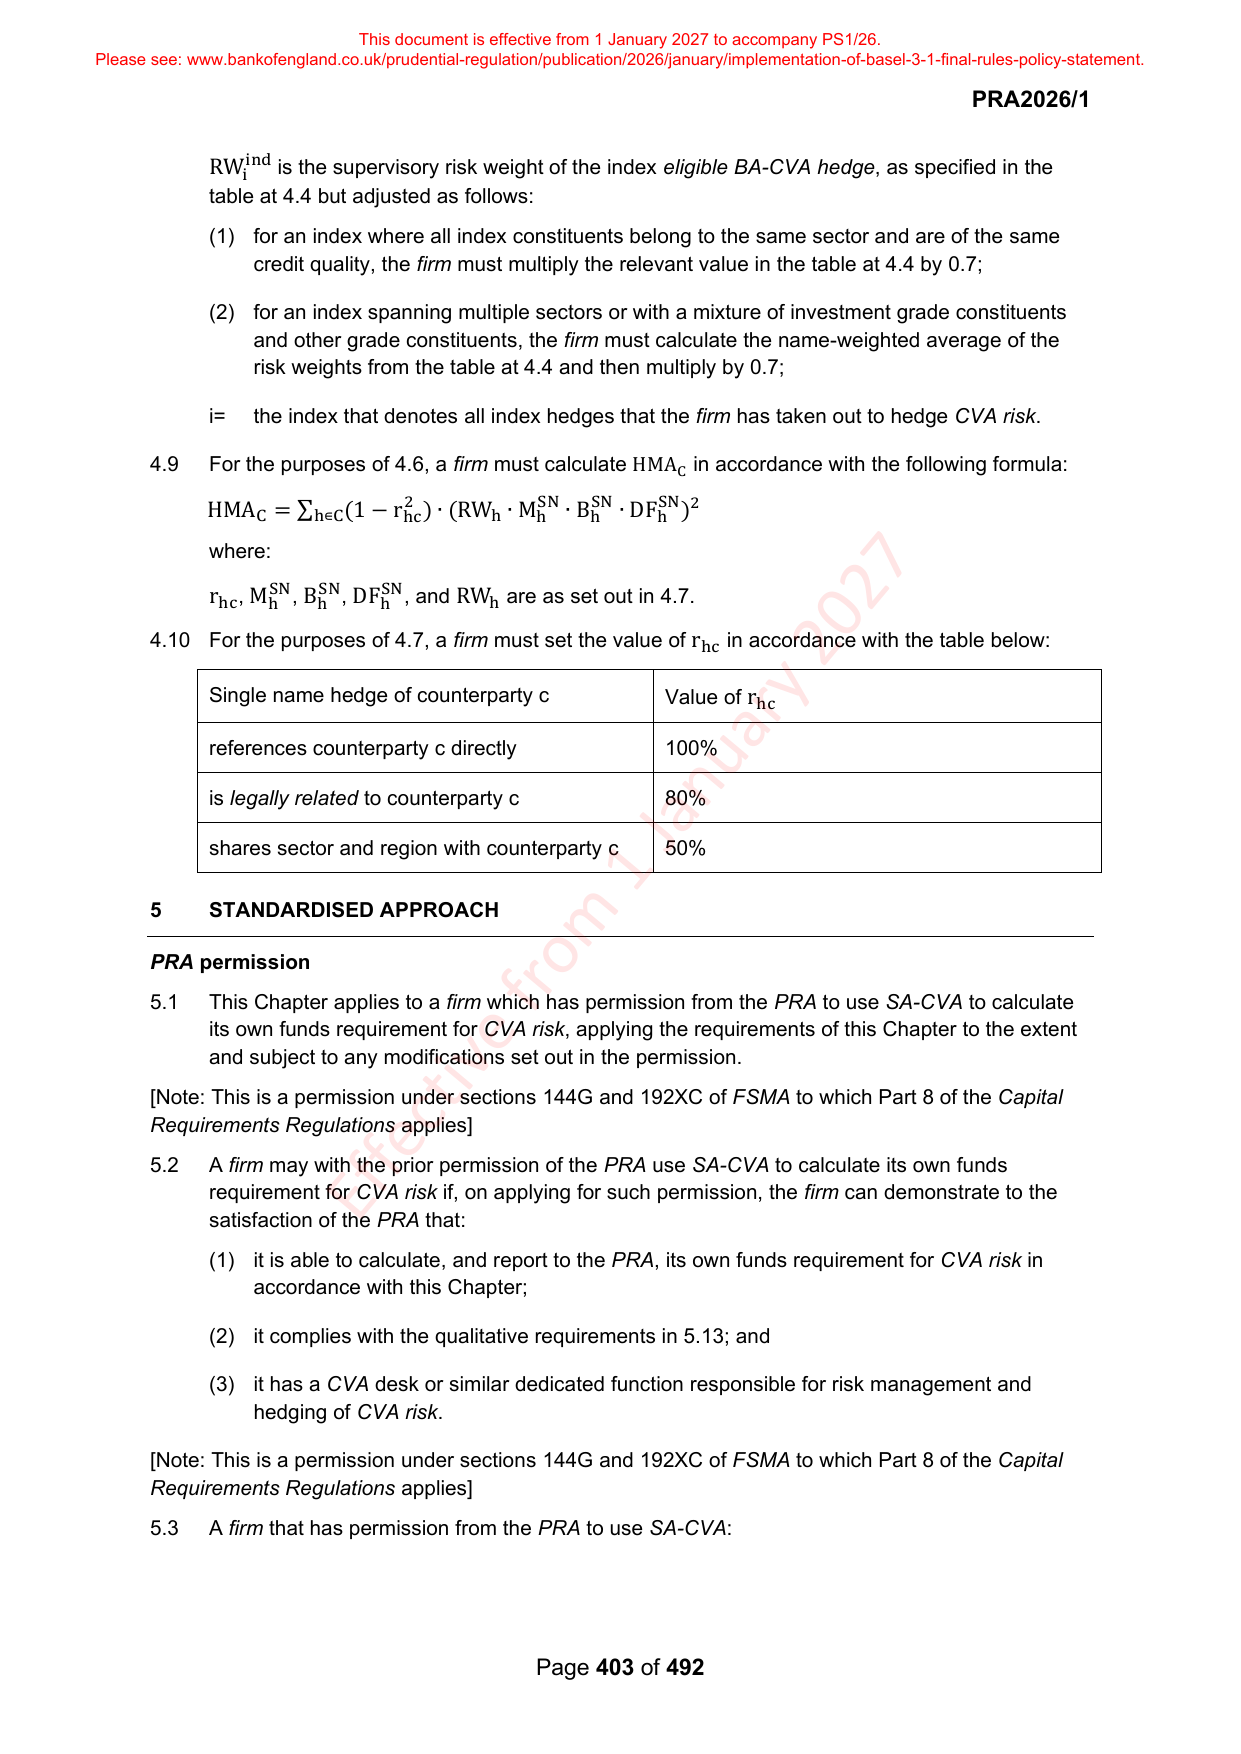
21424 4.10 For the purposes of 4.7, a firm must set the value of r hc in accordance with the table below:
21426 Single name hedge of counterparty c Value of r
21427 hc
21429 references counterparty c directly 100%
21431 is legally related to counterparty c 80%
21433 shares sector and region with counterparty c 50%
21435 5 STANDARDISED APPROACH
21437 PRA permission
21438 5.1 This Chapter applies to a firm which has permission from the PRA to use SA-CVA to calculate
21439 its own funds requirement for CVA risk, applying the requirements of this Chapter to the extent
21440 and subject to any modifications set out in the permission.
21441 [Note: This is a permission under sections 144G and 192XC of FSMA to which Part 8 of the Capital
21442 Requirements Regulations applies]
21443 5.2 A firm may with the prior permission of the PRA use SA-CVA to calculate its own funds
21444 requirement for CVA risk if, on applying for such permission, the firm can demonstrate to the
21445 satisfaction of the PRA that:
21446 (1) it is able to calculate, and report to the PRA, its own funds requirement for CVA risk in
21447 accordance with this Chapter;
21449 (2) it complies with the qualitative requirements in 5.13; and
21451 (3) it has a CVA desk or similar dedicated function responsible for risk management and
21452 hedging of CVA risk.
21454 [Note: This is a permission under sections 144G and 192XC of FSMA to which Part 8 of the Capital
21455 Requirements Regulations applies]
21456 5.3 A firm that has permission from the PRA to use SA-CVA:
21458 Page 403 of 492