20647 This document is effective from 1 January 2027 to accompany PS1/26.
20648Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
20649 PRA2026/1
20651 Article 354 CLOSELY CORRELATED CURRENCIES
20653 1. An institution may provide lower own funds requirements against positions in relevant closely
20654 correlated currencies. A pair of currencies is deemed to be closely correlated only if the
20655 likelihood of a loss, calculated on the basis of daily exchange-rate data for the preceding three
20656 or five years, occurring on equal and opposite positions in such currencies over the following 10
20657 working days, which is 4% or less of the value of the matched position in question (valued in
20658 terms of the reporting currency) has a probability of at least 99%, when an observation period
20659 of three years is used, and 95%, when an observation period of five years is used. The own-
20660 funds requirement on the matched position in two closely correlated currencies shall be 4%
20661 multiplied by the value of the matched position.
20662 2. In calculating the requirements of Articles 351 to 354, an institution may disregard positions in
20663 currencies, which are subject to a legally binding intergovernmental agreement to limit its
20664 variation relative to other currencies covered by the same agreement. It shall calculate the
20665 matched positions in such currencies and subject them to an own funds requirement no lower
20666 than half of the maximum permissible variation laid down in the intergovernmental agreement in
20667 question in respect of the currencies concerned.
20668 3. An institution may determine the list of currencies for which the treatment set out in paragraph 1
20669 is available, based on the following criteria:
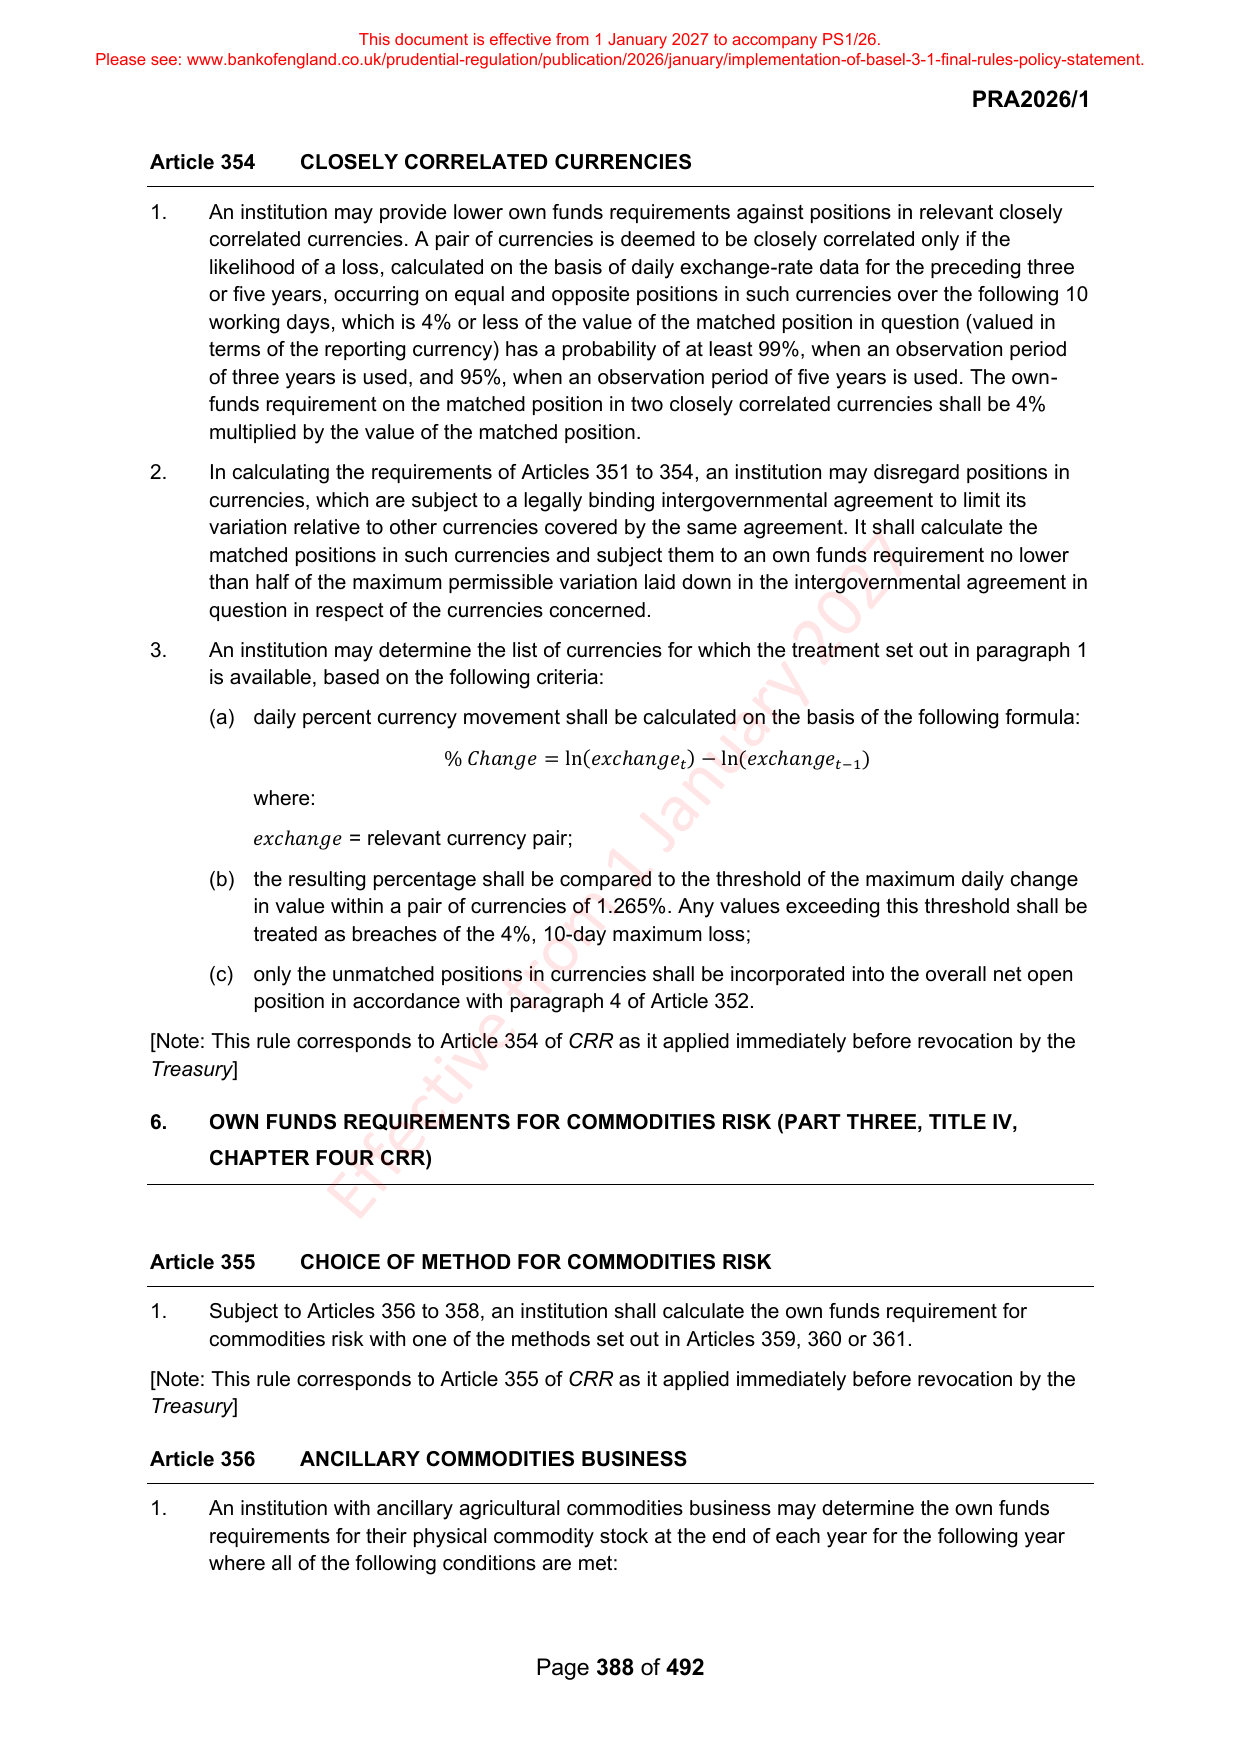
20670 (a) daily percent currency movement shall be calculated on the basis of the following formula:
20672 % 𝐶ℎ𝑎𝑛𝑔𝑒 = ln(𝑒𝑥𝑐ℎ𝑎𝑛𝑔𝑒 𝑡 ) − ln(𝑒𝑥𝑐ℎ𝑎𝑛𝑔𝑒 𝑡−1 )
20673 where:
20675 𝑒𝑥𝑐ℎ𝑎𝑛𝑔𝑒 = relevant currency pair;
20677 (b) the resulting percentage shall be compared to the threshold of the maximum daily change
20678 in value within a pair of currencies of 1.265%. Any values exceeding this threshold shall be
20679 treated as breaches of the 4%, 10-day maximum loss;
20680 (c) only the unmatched positions in currencies shall be incorporated into the overall net open
20681 position in accordance with paragraph 4 of Article 352.
20682 [Note: This rule corresponds to Article 354 of CRR as it applied immediately before revocation by the
20683 Treasury]
20685 6. OWN FUNDS REQUIREMENTS FOR COMMODITIES RISK (PART THREE, TITLE IV,
20686 CHAPTER FOUR CRR)
20688 Article 355 CHOICE OF METHOD FOR COMMODITIES RISK
20690 1. Subject to Articles 356 to 358, an institution shall calculate the own funds requirement for
20691 commodities risk with one of the methods set out in Articles 359, 360 or 361.
20692 [Note: This rule corresponds to Article 355 of CRR as it applied immediately before revocation by the
20693 Treasury]
20695 Article 356 ANCILLARY COMMODITIES BUSINESS
20697 1. An institution with ancillary agricultural commodities business may determine the own funds
20698 requirements for their physical commodity stock at the end of each year for the following year
20699 where all of the following conditions are met:
20701 Page 388 of 492