20444 This document is effective from 1 January 2027 to accompany PS1/26.
20445Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
20446 PRA2026/1
20448 market value, where ‘market value’ is understood in the manner described in point (d) of
20449 paragraph 5; and
20450 (c) the own funds requirements for non-delta risks related to non-continuous options or
20451 warrants shall be determined as follows:
20452 (i) where the options or warrants have been bought, as the maximum amount between
20453 zero and the difference between the following values:
20454 (1) the market value of the option or warrant, understood in the manner described in
20455 point (d) of paragraph 5; and
20456 (2) the risk-weighted delta equivalent amount, understood in the manner described
20457 in point (a)(ii) of paragraph 5;
20458 (ii) where the options or warrants have been sold, as the maximum between zero and the
20459 difference between the following amounts:
20460 (1) the relevant market value of the underlying asset, which shall be taken to be
20461 either the maximum possible payment at expiry date, if it is contractually fixed, or
20462 the market value of the underlying asset or the effective notional value if no
20463 maximum possible payment is contractually fixed; and
20464 (2) the risk-weighted delta equivalent amount, understood in the manner described
20465 in point (a)(ii) of paragraph 5; and
20466 (d) the value for gamma and vega used in the calculation of own funds requirements shall be
20467 calculated using an appropriate pricing model as referred to in Article 329(1), Article 352(1)
20468 and Article 358(3). Where either gamma or vega cannot be calculated in accordance with
20469 this point (d), the capital requirement on non-delta risks shall be calculated according to
20470 point (c) of this paragraph.
20471 The Delta-plus approach: gamma risk
20472 7. An institution shall determine own funds requirements for gamma risk under the Delta-plus
20473 approach in accordance with the following:
20474 (a) for the purposes of point (a)(i) of paragraph 6, an institution shall calculate the own funds
20475 requirements for gamma risk by a process consisting of the following sequence of steps:
20476 (i) for each individual option or warrant a gamma impact shall be calculated;
20477 (ii) the gamma impacts of individual options or warrants which refer to the same distinct
20478 underlying type shall be summed up; and
20479 (iii) the absolute value of the sum of all of the negative values resulting from step (ii) shall
20480 provide the own funds requirements for gamma risk. Positive values resulting from
20481 step (ii) shall be disregarded;
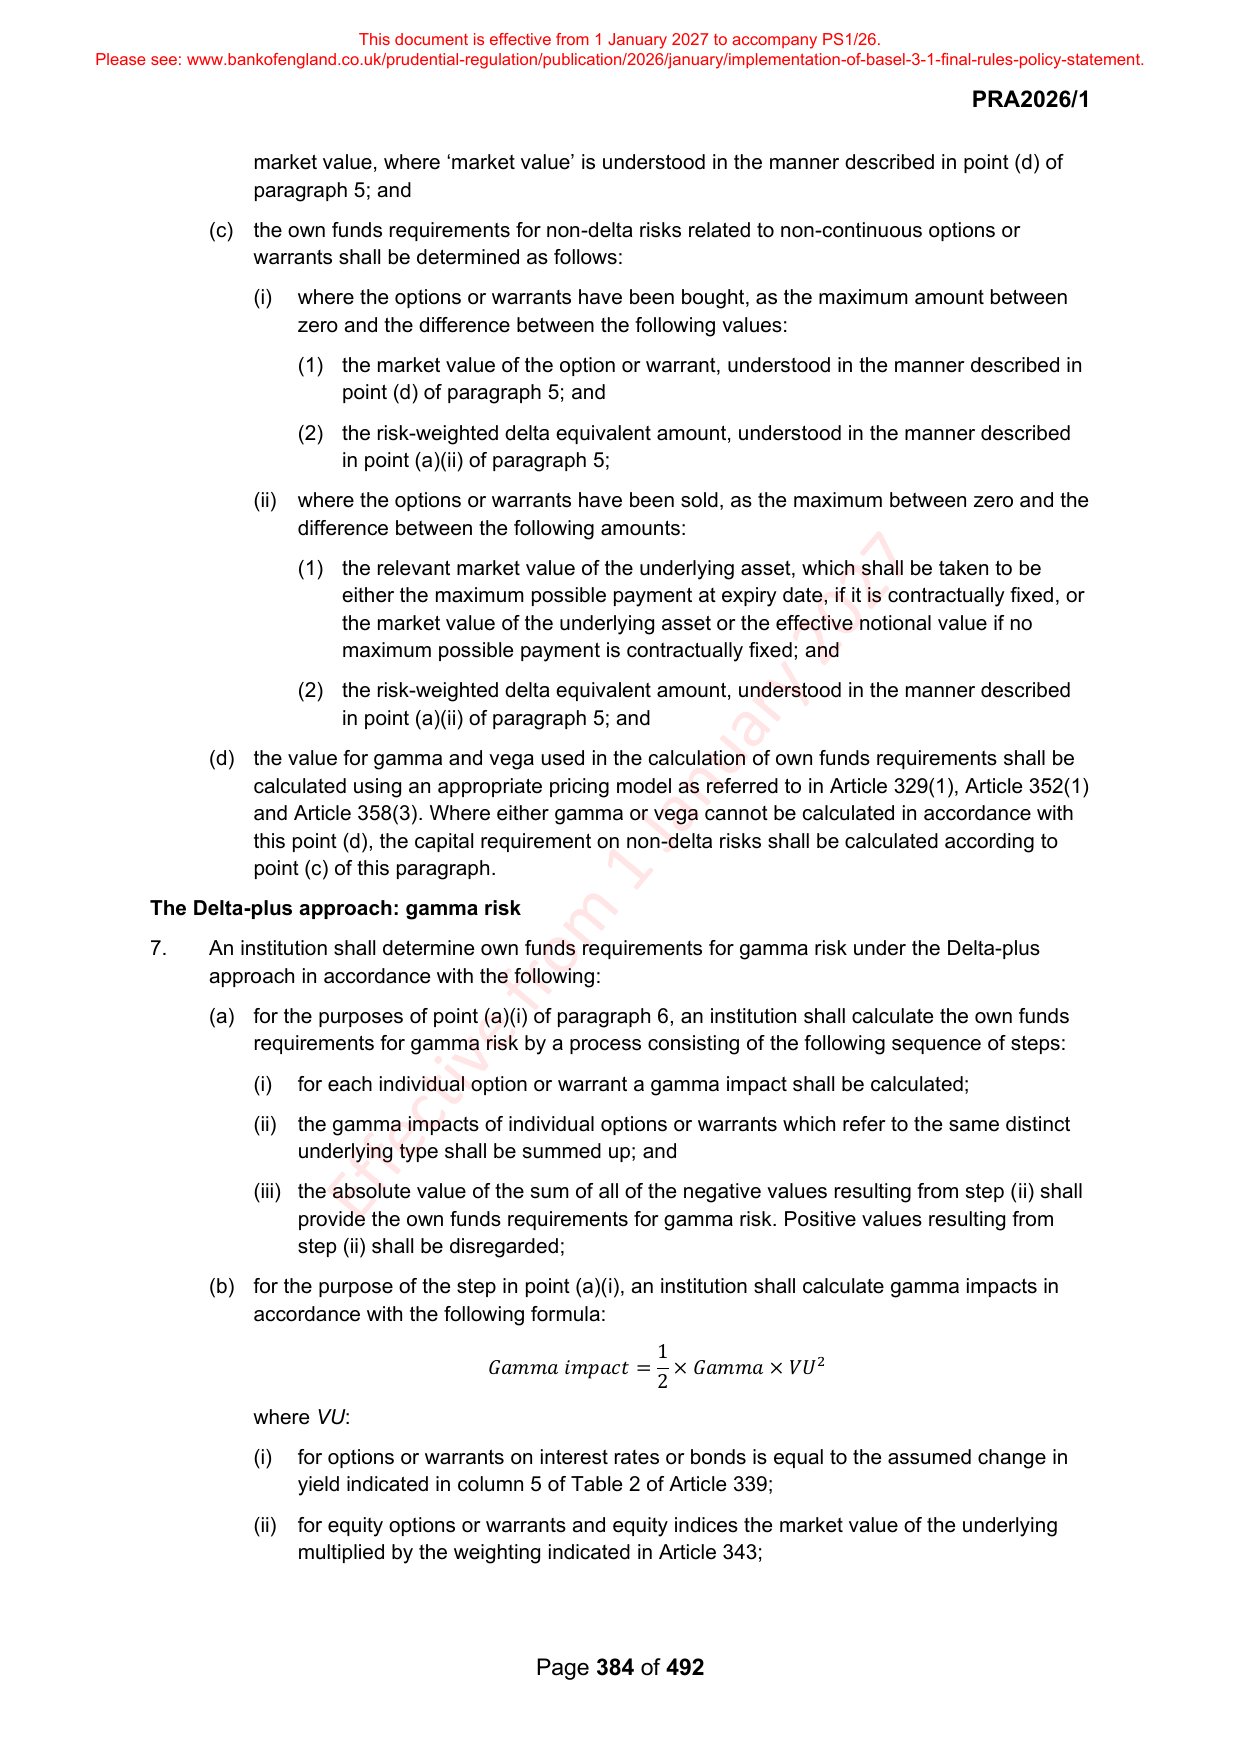
20482 (b) for the purpose of the step in point (a)(i), an institution shall calculate gamma impacts in
20483 accordance with the following formula:
20484 1
20485 2
20486 𝐺𝑎𝑚𝑚𝑎 𝑖𝑚𝑝𝑎𝑐𝑡 = × 𝐺𝑎𝑚𝑚𝑎 × 𝑉𝑈
20487 2
20488 where VU:
20489 (i) for options or warrants on interest rates or bonds is equal to the assumed change in
20490 yield indicated in column 5 of Table 2 of Article 339;
20491 (ii) for equity options or warrants and equity indices the market value of the underlying
20492 multiplied by the weighting indicated in Article 343;
20494 Page 384 of 492