20038 This document is effective from 1 January 2027 to accompany PS1/26.
20039Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
20040 PRA2026/1
20042 (3) Industrials
20043 (4) Consumer Goods
20044 (5) Health Care
20045 (6) Consumer Services
20046 (7) Telecommunications
20047 (8) Utilities
20048 (9) Financials
20049 (10) Technology
20050 2. [Note: Provision left blank]
20051 3. An institution may break down stock-index futures, the delta-weighted equivalents of options in
20052 stock-index futures and stock indices (collectively referred to hereafter as ‘stock-index futures’),
20053 into positions in each of their constituent equities. The institution may treat these positions as
20054 underlying positions in the equities in question, and may, be netted against opposite positions
20055 in the underlying equities themselves. The institution shall notify the PRA of the use they make
20056 of that treatment.
20057 4. Where a stock-index future is not broken down into its underlying positions, an institution shall
20058 treat it as if it were an individual equity. However, the institution may ignore the specific risk on
20059 this individual equity if the stock-index future in question is exchange traded and represents a
20060 relevant appropriately diversified index.
20061 [Note: Paragraphs 3 and 4 of this rule correspond to Article 344(3) and (4) of CRR as it applied
20062 immediately before revocation by the Treasury]
20064 SECTION 4 UNDERWRITING
20066 Article 345 REDUCTION OF NET POSITIONS
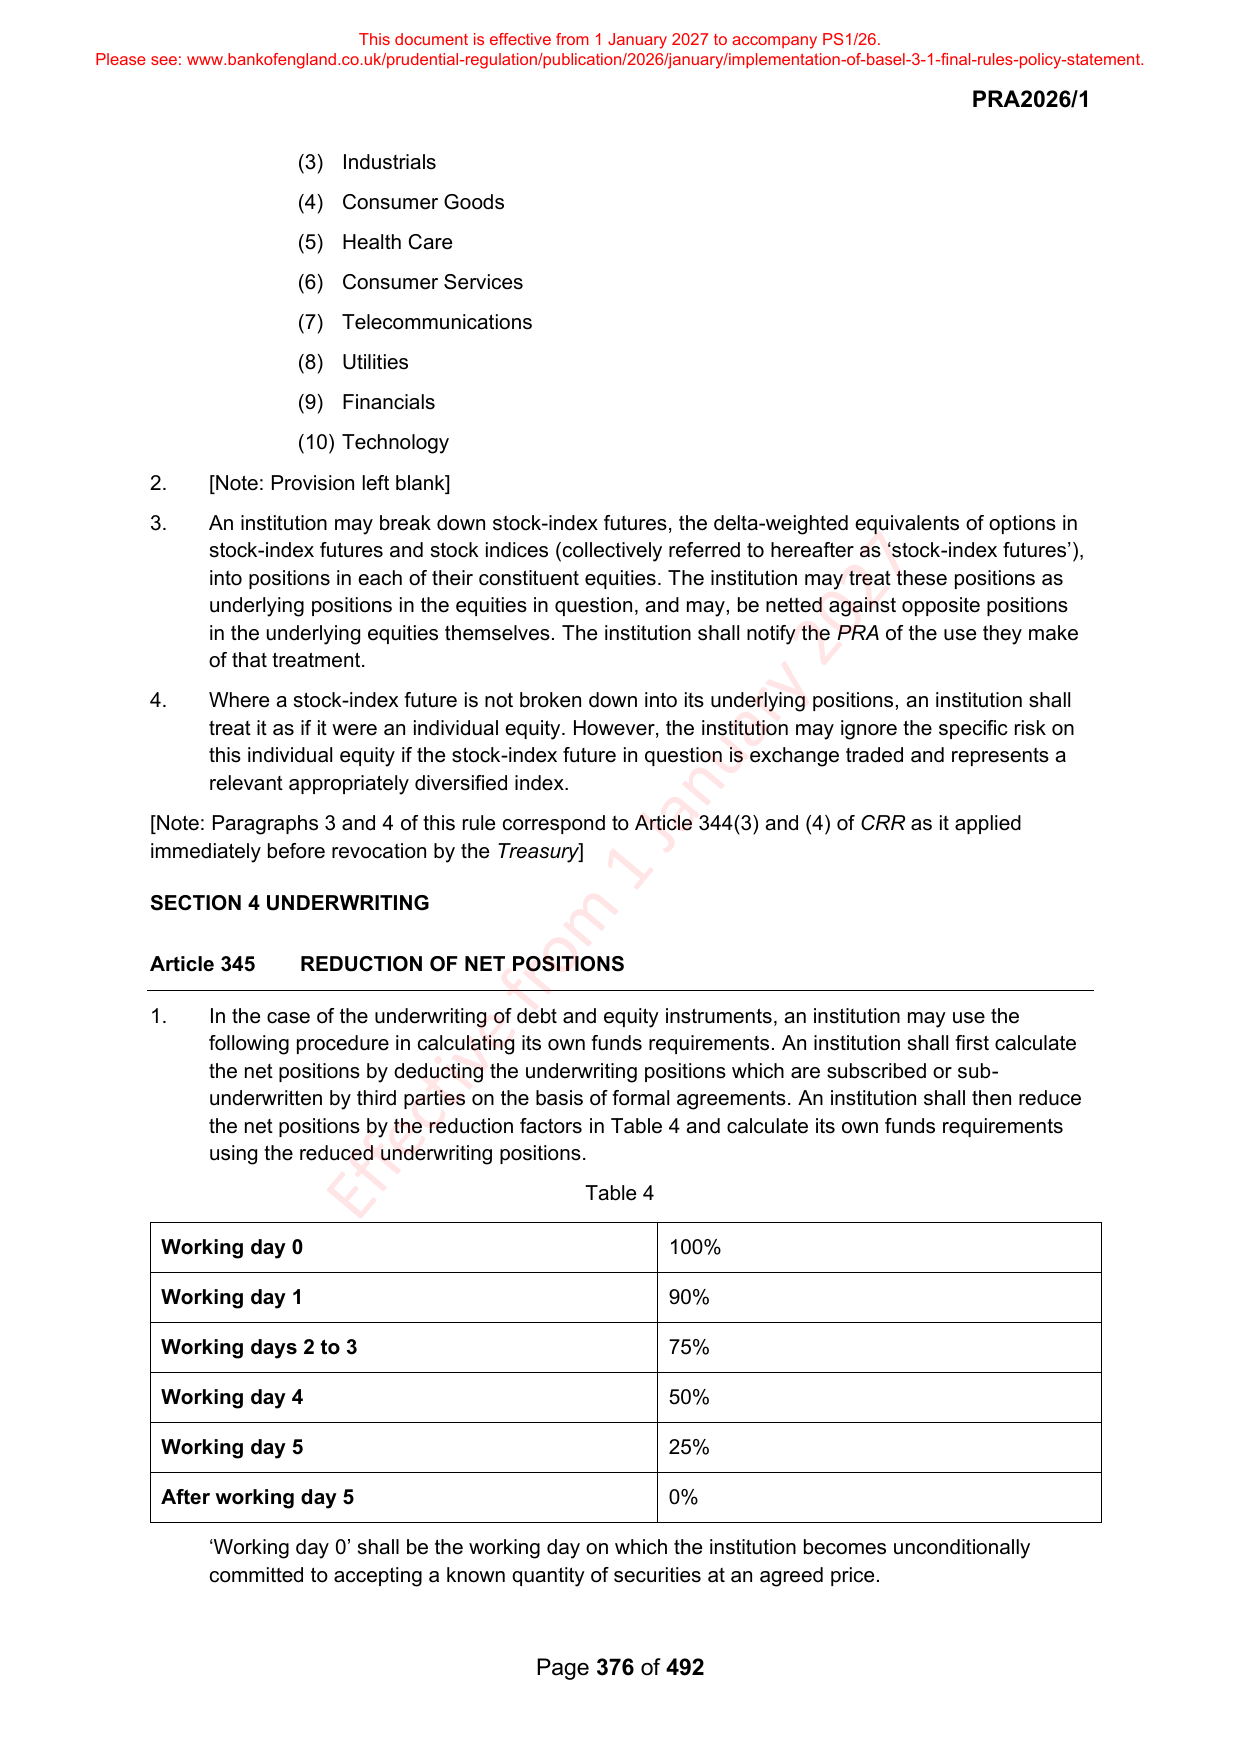
20068 1. In the case of the underwriting of debt and equity instruments, an institution may use the
20069 following procedure in calculating its own funds requirements. An institution shall first calculate
20070 the net positions by deducting the underwriting positions which are subscribed or sub-
20071 underwritten by third parties on the basis of formal agreements. An institution shall then reduce
20072 the net positions by the reduction factors in Table 4 and calculate its own funds requirements
20073 using the reduced underwriting positions.
20074 Table 4
20076 Working day 0 100%
20078 Working day 1 90%
20080 Working days 2 to 3 75%
20082 Working day 4 50%
20084 Working day 5 25%
20086 After working day 5 0%
20088 ‘Working day 0’ shall be the working day on which the institution becomes unconditionally
20089 committed to accepting a known quantity of securities at an agreed price.
20091 Page 376 of 492