19707 This document is effective from 1 January 2027 to accompany PS1/26.
19708Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
19709 PRA2026/1
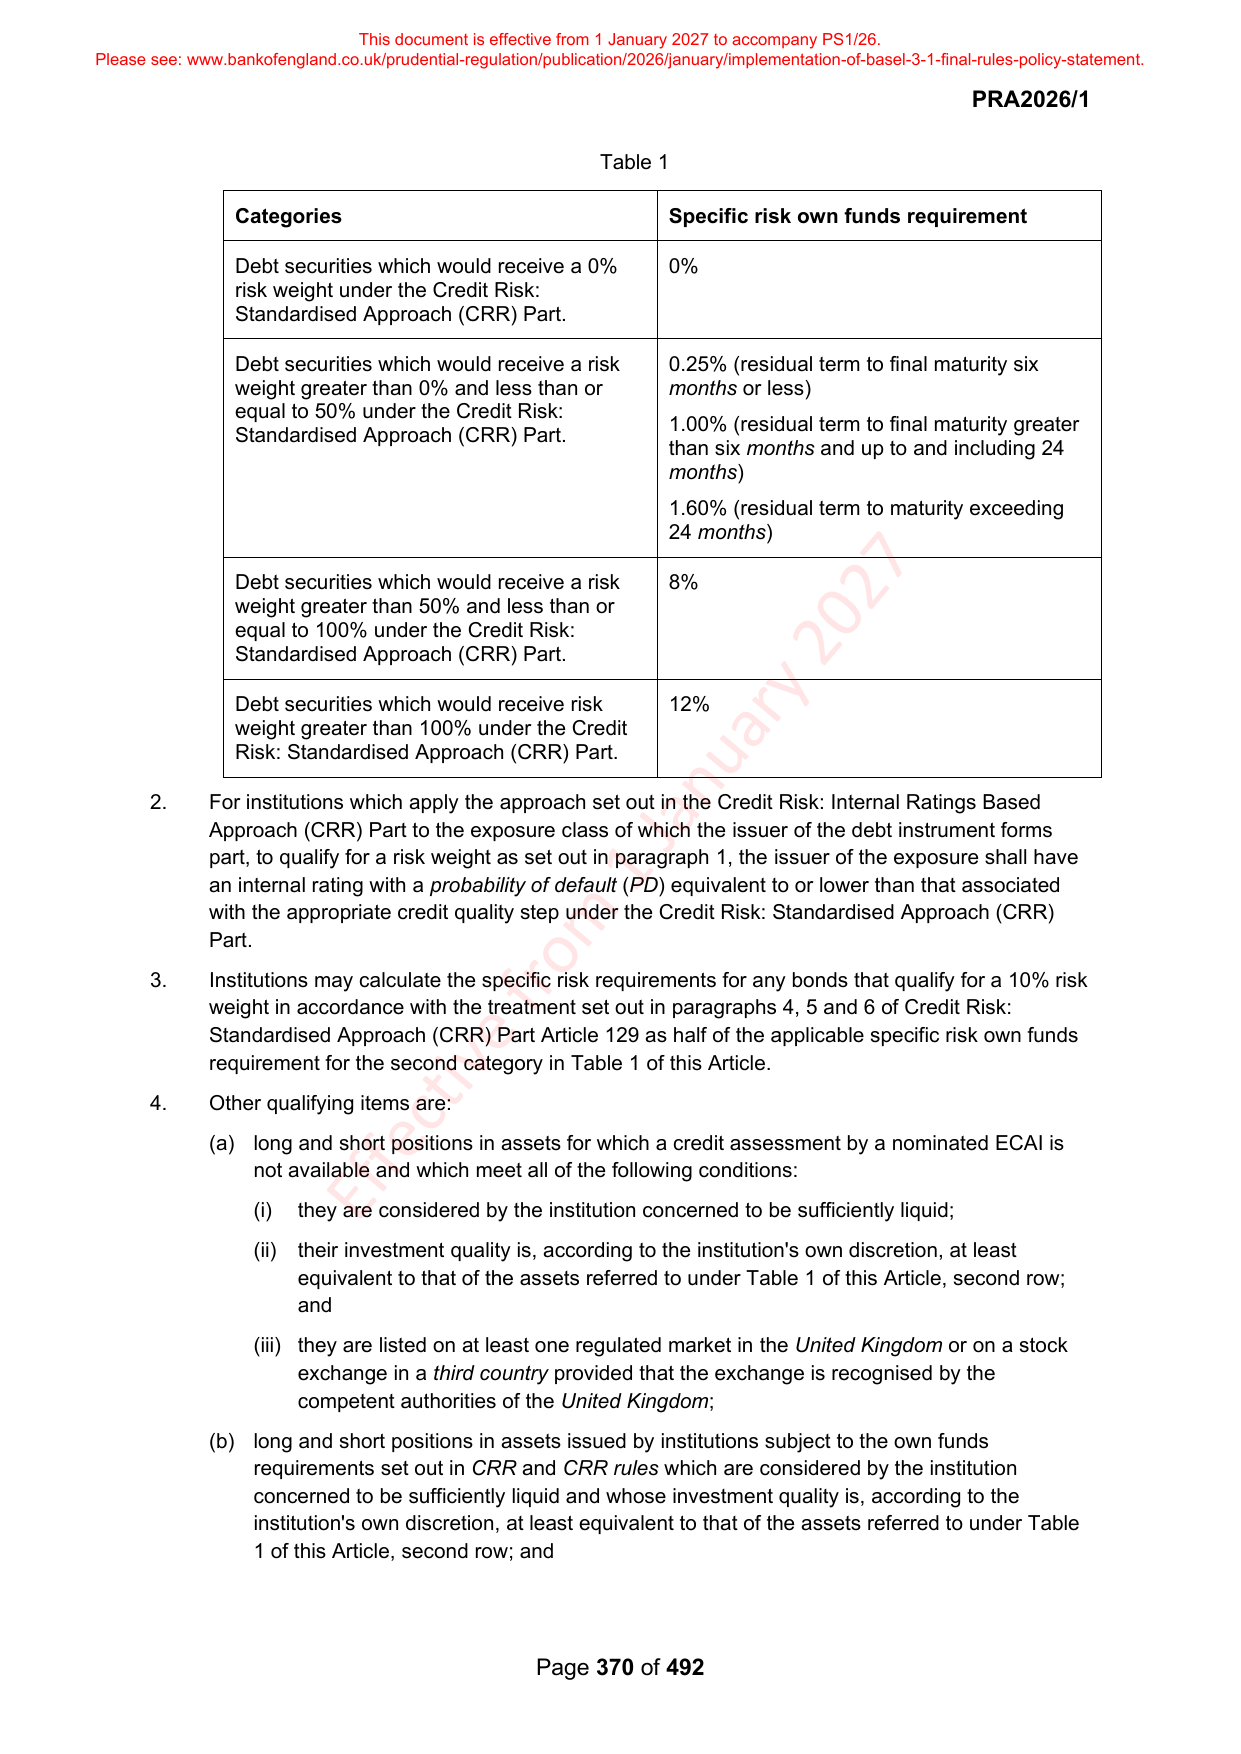
19711 Table 1
19713 Categories Specific risk own funds requirement
19715 Debt securities which would receive a 0% 0%
19716 risk weight under the Credit Risk:
19717 Standardised Approach (CRR) Part.
19719 Debt securities which would receive a risk 0.25% (residual term to final maturity six
19720 weight greater than 0% and less than or months or less)
19721 equal to 50% under the Credit Risk:
19722 1.00% (residual term to final maturity greater
19723 Standardised Approach (CRR) Part.
19724 than six months and up to and including 24
19725 months)
19726 1.60% (residual term to maturity exceeding
19727 24 months)
19729 Debt securities which would receive a risk 8%
19730 weight greater than 50% and less than or
19731 equal to 100% under the Credit Risk:
19732 Standardised Approach (CRR) Part.
19734 Debt securities which would receive risk 12%
19735 weight greater than 100% under the Credit
19736 Risk: Standardised Approach (CRR) Part.
19738 2. For institutions which apply the approach set out in the Credit Risk: Internal Ratings Based
19739 Approach (CRR) Part to the exposure class of which the issuer of the debt instrument forms
19740 part, to qualify for a risk weight as set out in paragraph 1, the issuer of the exposure shall have
19741 an internal rating with a probability of default (PD) equivalent to or lower than that associated
19742 with the appropriate credit quality step under the Credit Risk: Standardised Approach (CRR)
19743 Part.
19744 3. Institutions may calculate the specific risk requirements for any bonds that qualify for a 10% risk
19745 weight in accordance with the treatment set out in paragraphs 4, 5 and 6 of Credit Risk:
19746 Standardised Approach (CRR) Part Article 129 as half of the applicable specific risk own funds
19747 requirement for the second category in Table 1 of this Article.
19748 4. Other qualifying items are:
19749 (a) long and short positions in assets for which a credit assessment by a nominated ECAI is
19750 not available and which meet all of the following conditions:
19751 (i) they are considered by the institution concerned to be sufficiently liquid;
19752 (ii) their investment quality is, according to the institution's own discretion, at least
19753 equivalent to that of the assets referred to under Table 1 of this Article, second row;
19754 and
19755 (iii) they are listed on at least one regulated market in the United Kingdom or on a stock
19756 exchange in a third country provided that the exchange is recognised by the
19757 competent authorities of the United Kingdom;
19758 (b) long and short positions in assets issued by institutions subject to the own funds
19759 requirements set out in CRR and CRR rules which are considered by the institution
19760 concerned to be sufficiently liquid and whose investment quality is, according to the
19761 institution's own discretion, at least equivalent to that of the assets referred to under Table
19762 1 of this Article, second row; and
19764 Page 370 of 492