19238 This document is effective from 1 January 2027 to accompany PS1/26.
19239Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
19240 PRA2026/1
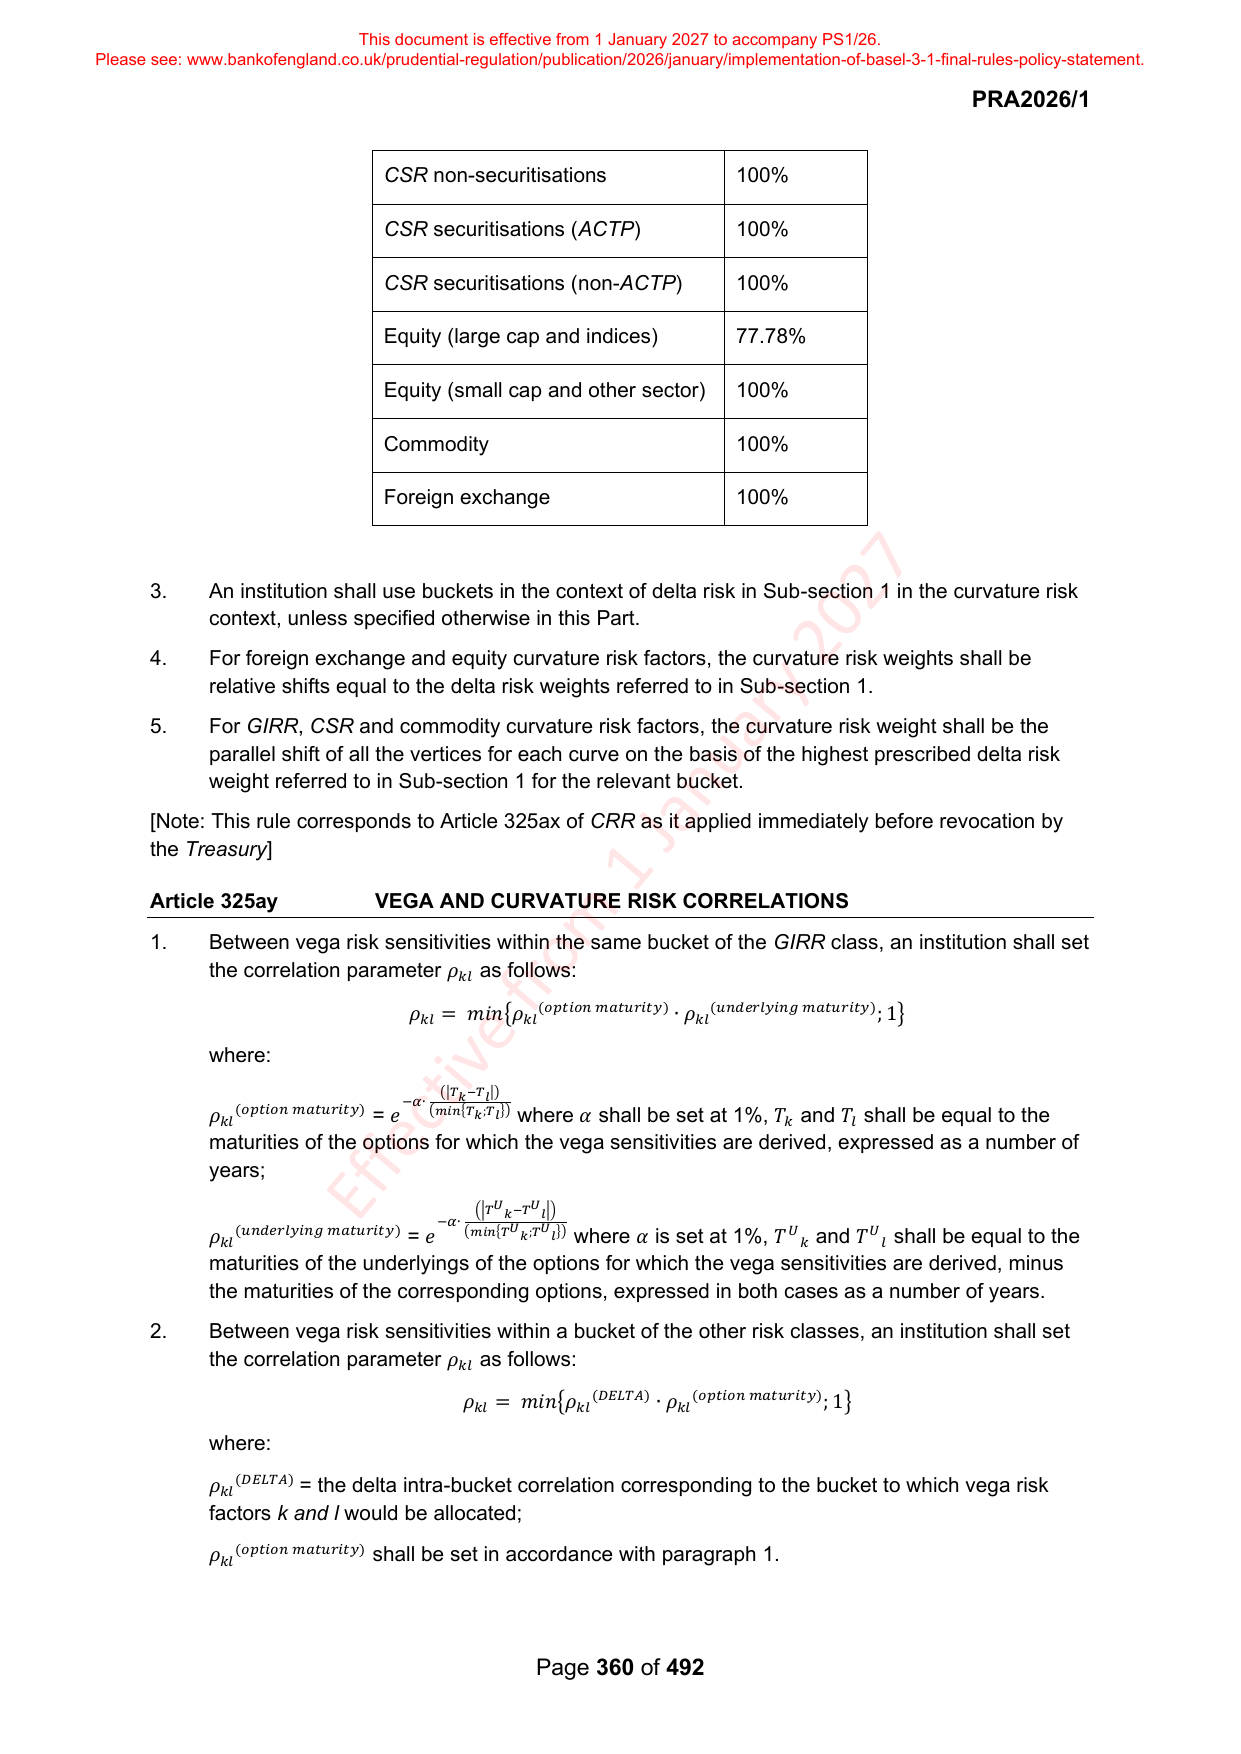
19242 CSR non-securitisations 100%
19244 CSR securitisations (ACTP) 100%
19246 CSR securitisations (non-ACTP) 100%
19248 Equity (large cap and indices) 77.78%
19250 Equity (small cap and other sector) 100%
19252 Commodity 100%
19254 Foreign exchange 100%
19256 3. An institution shall use buckets in the context of delta risk in Sub-section 1 in the curvature risk
19257 context, unless specified otherwise in this Part.
19258 4. For foreign exchange and equity curvature risk factors, the curvature risk weights shall be
19259 relative shifts equal to the delta risk weights referred to in Sub-section 1.
19260 5. For GIRR, CSR and commodity curvature risk factors, the curvature risk weight shall be the
19261 parallel shift of all the vertices for each curve on the basis of the highest prescribed delta risk
19262 weight referred to in Sub-section 1 for the relevant bucket.
19263 [Note: This rule corresponds to Article 325ax of CRR as it applied immediately before revocation by
19264 the Treasury]
19266 Article 325ay VEGA AND CURVATURE RISK CORRELATIONS
19267 1. Between vega risk sensitivities within the same bucket of the GIRR class, an institution shall set
19268 the correlation parameter 𝜌 𝑘𝑙 as follows:
19269 (𝑜𝑝𝑡𝑖𝑜𝑛 𝑚𝑎𝑡𝑢𝑟𝑖𝑡𝑦) (𝑢𝑛𝑑𝑒𝑟𝑙𝑦𝑖𝑛𝑔 𝑚𝑎𝑡𝑢𝑟𝑖𝑡𝑦)
19270 𝜌 𝑘𝑙 = 𝑚𝑖𝑛{𝜌 𝑘𝑙 ∙ 𝜌 𝑘𝑙 ; 1}
19271 where:
19273 (|𝑇𝑘 −𝑇𝑙 |)
19274 −𝛼∙
19275 (𝑜𝑝𝑡𝑖𝑜𝑛 𝑚𝑎𝑡𝑢𝑟𝑖𝑡𝑦) = (𝑚𝑖𝑛{𝑇𝑘 ;𝑇𝑙}) where shall be set at 1%, and shall be equal to the
19276 𝜌 𝑘𝑙 𝑒 𝛼 𝑇 𝑘 𝑇 𝑙
19277 maturities of the options for which the vega sensitivities are derived, expressed as a number of
19278 years;
19279 (|𝑇𝑈 𝑘 −𝑇𝑈 𝑙 |)
19280 −𝛼∙
19281 (𝑢𝑛𝑑𝑒𝑟𝑙𝑦𝑖𝑛𝑔 𝑚𝑎𝑡𝑢𝑟𝑖𝑡𝑦) = (𝑚𝑖𝑛{𝑇𝑈 𝑘 ;𝑇𝑈 𝑙 }) where is set at 1%, 𝑈 and 𝑈 shall be equal to the
19282 𝜌 𝑘𝑙 𝑒 𝛼 𝑇 𝑘 𝑇 𝑙
19283 maturities of the underlyings of the options for which the vega sensitivities are derived, minus
19284 the maturities of the corresponding options, expressed in both cases as a number of years.
19285 2. Between vega risk sensitivities within a bucket of the other risk classes, an institution shall set
19286 the correlation parameter 𝜌 𝑘𝑙 as follows:
19287 (𝐷𝐸𝐿𝑇𝐴) (𝑜𝑝𝑡𝑖𝑜𝑛 𝑚𝑎𝑡𝑢𝑟𝑖𝑡𝑦)
19288 𝜌 𝑘𝑙 = 𝑚𝑖𝑛{𝜌 𝑘𝑙 ∙ 𝜌 𝑘𝑙 ; 1}
19289 where:
19290 (𝐷𝐸𝐿𝑇𝐴) = the delta intra-bucket correlation corresponding to the bucket to which vega risk
19291 𝜌 𝑘𝑙
19292 factors k and l would be allocated;
19293 (𝑜𝑝𝑡𝑖𝑜𝑛 𝑚𝑎𝑡𝑢𝑟𝑖𝑡𝑦) shall be set in accordance with paragraph 1.
19294 𝜌 𝑘𝑙
19296 Page 360 of 492