19127 This document is effective from 1 January 2027 to accompany PS1/26.
19128Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
19129 PRA2026/1
19131 (𝑐𝑜𝑚𝑚𝑜𝑑𝑖𝑡𝑦) (𝑡𝑒𝑛𝑜𝑟) (𝑏𝑎𝑠𝑖𝑠)
19132 𝜌 𝑘𝑙 = 𝜌 𝑘𝑙 ∙ 𝜌 𝑘𝑙 ∙ 𝜌 𝑘𝑙
19134 where:
19135 (𝑐𝑜𝑚𝑚𝑜𝑑𝑖𝑡𝑦) = 1 where the two commodities of sensitivities k and l are identical, otherwise it
19136 𝜌 𝑘𝑙
19137 shall be equal to the intra-bucket correlations in Table 10;
19138 (𝑡𝑒𝑛𝑜𝑟) = 1 where the two vertices of the sensitivities k and l are identical, otherwise it shall be
19139 𝜌 𝑘𝑙
19140 equal to 99%;
19141 (𝑏𝑎𝑠𝑖𝑠) = 1 where the two sensitivities are identical in the delivery location of a commodity,
19142 𝜌 𝑘𝑙
19143 otherwise it shall be equal to 99.90%.
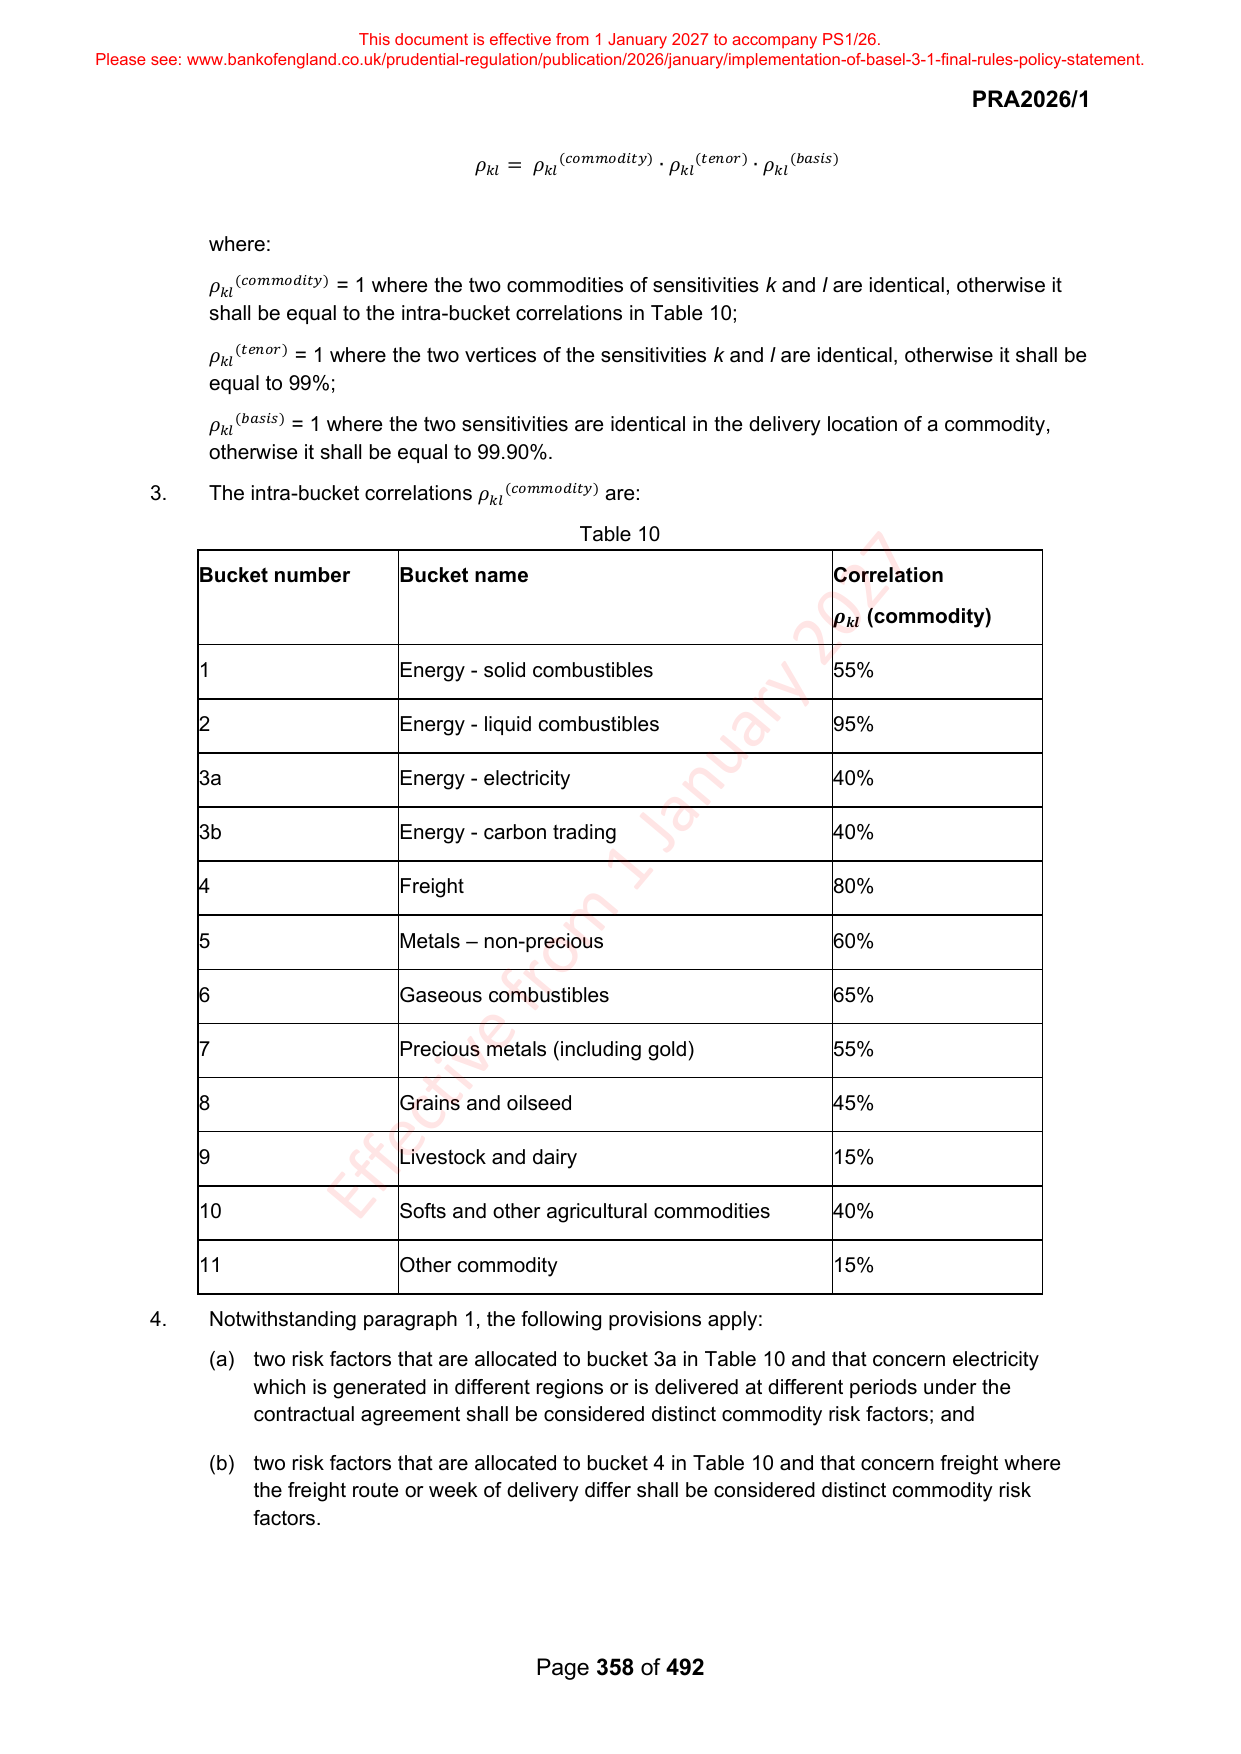
19144 3. The intra-bucket correlations (𝑐𝑜𝑚𝑚𝑜𝑑𝑖𝑡𝑦) are:
19145 𝜌 𝑘𝑙
19146 Table 10
19148 Bucket number Bucket name Correlation
19150 𝝆 𝒌𝒍 (commodity)
19152 1 Energy - solid combustibles 55%
19154 2 Energy - liquid combustibles 95%
19156 3a Energy - electricity 40%
19158 3b Energy - carbon trading 40%
19160 4 Freight 80%
19162 5 Metals – non-precious 60%
19164 6 Gaseous combustibles 65%
19166 7 Precious metals (including gold) 55%
19168 8 Grains and oilseed 45%
19170 9 Livestock and dairy 15%
19172 10 Softs and other agricultural commodities 40%
19174 11 Other commodity 15%
19176 4. Notwithstanding paragraph 1, the following provisions apply:
19177 (a) two risk factors that are allocated to bucket 3a in Table 10 and that concern electricity
19178 which is generated in different regions or is delivered at different periods under the
19179 contractual agreement shall be considered distinct commodity risk factors; and
19181 (b) two risk factors that are allocated to bucket 4 in Table 10 and that concern freight where
19182 the freight route or week of delivery differ shall be considered distinct commodity risk
19183 factors.
19185 Page 358 of 492