18604 This document is effective from 1 January 2027 to accompany PS1/26.
18605Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
18606 PRA2026/1
18608 14
18610 7 and 5% 0% 45% 45%
18611 15
18613 8 0% 45% 45%
18615 16 0% 0%
18617 17 75%
18619 18
18621 [Note: This rule corresponds to Article 325aj of CRR as it applied immediately before revocation by
18622 the Treasury]
18624 Article 325ak RISK WEIGHTS FOR CREDIT SPREAD RISK FOR SECURITISATIONS
18625 INCLUDED IN THE ACTP
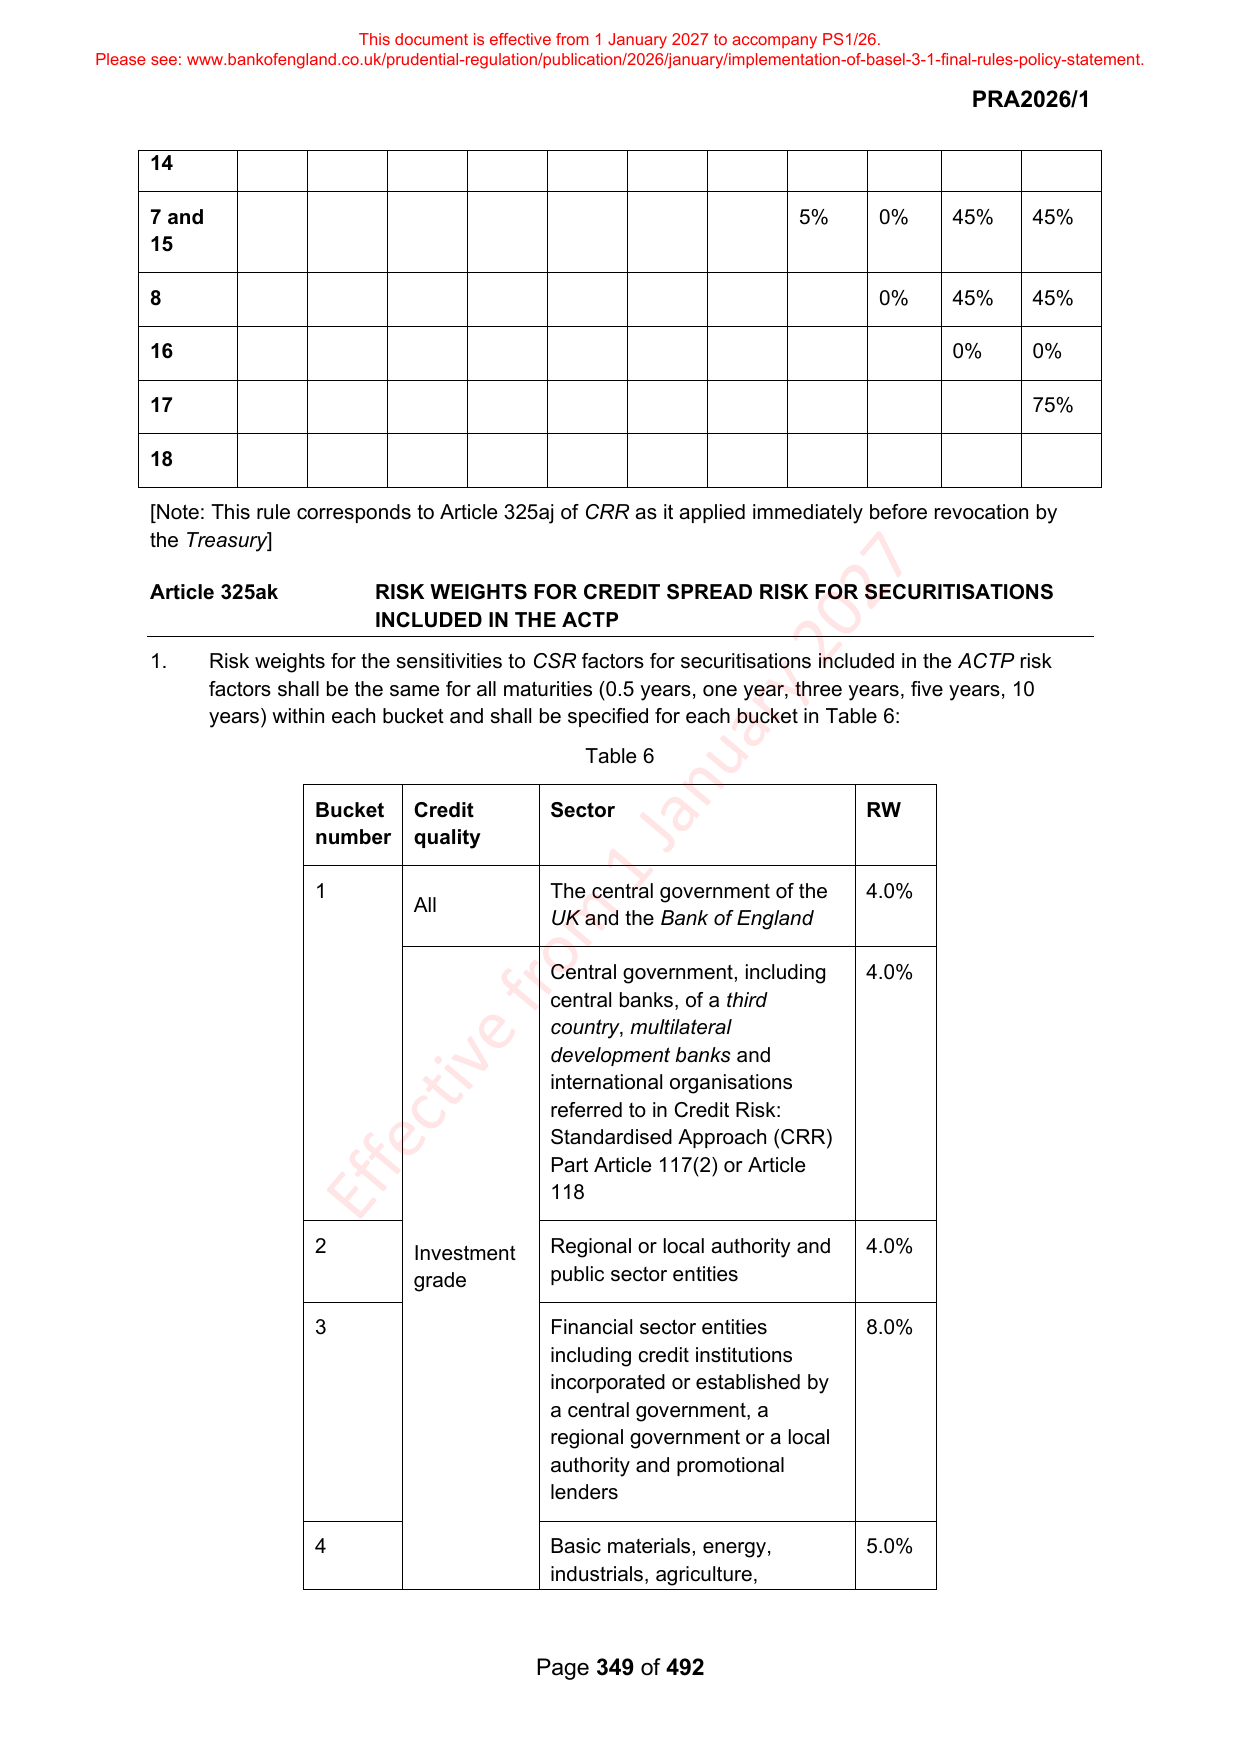
18626 1. Risk weights for the sensitivities to CSR factors for securitisations included in the ACTP risk
18627 factors shall be the same for all maturities (0.5 years, one year, three years, five years, 10
18628 years) within each bucket and shall be specified for each bucket in Table 6:
18629 Table 6
18631 Bucket Credit Sector RW
18632 number quality
18634 1 The central government of the 4.0%
18635 All
18636 UK and the Bank of England
18638 Central government, including 4.0%
18639 central banks, of a third
18640 country, multilateral
18641 development banks and
18642 international organisations
18643 referred to in Credit Risk:
18644 Standardised Approach (CRR)
18645 Part Article 117(2) or Article
18646 118
18648 2 Investment Regional or local authority and 4.0%
18649 grade public sector entities
18651 3 Financial sector entities 8.0%
18652 including credit institutions
18653 incorporated or established by
18654 a central government, a
18655 regional government or a local
18656 authority and promotional
18657 lenders
18659 4 Basic materials, energy, 5.0%
18660 industrials, agriculture,
18662 Page 349 of 492