18487 This document is effective from 1 January 2027 to accompany PS1/26.
18488Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
18489 PRA2026/1
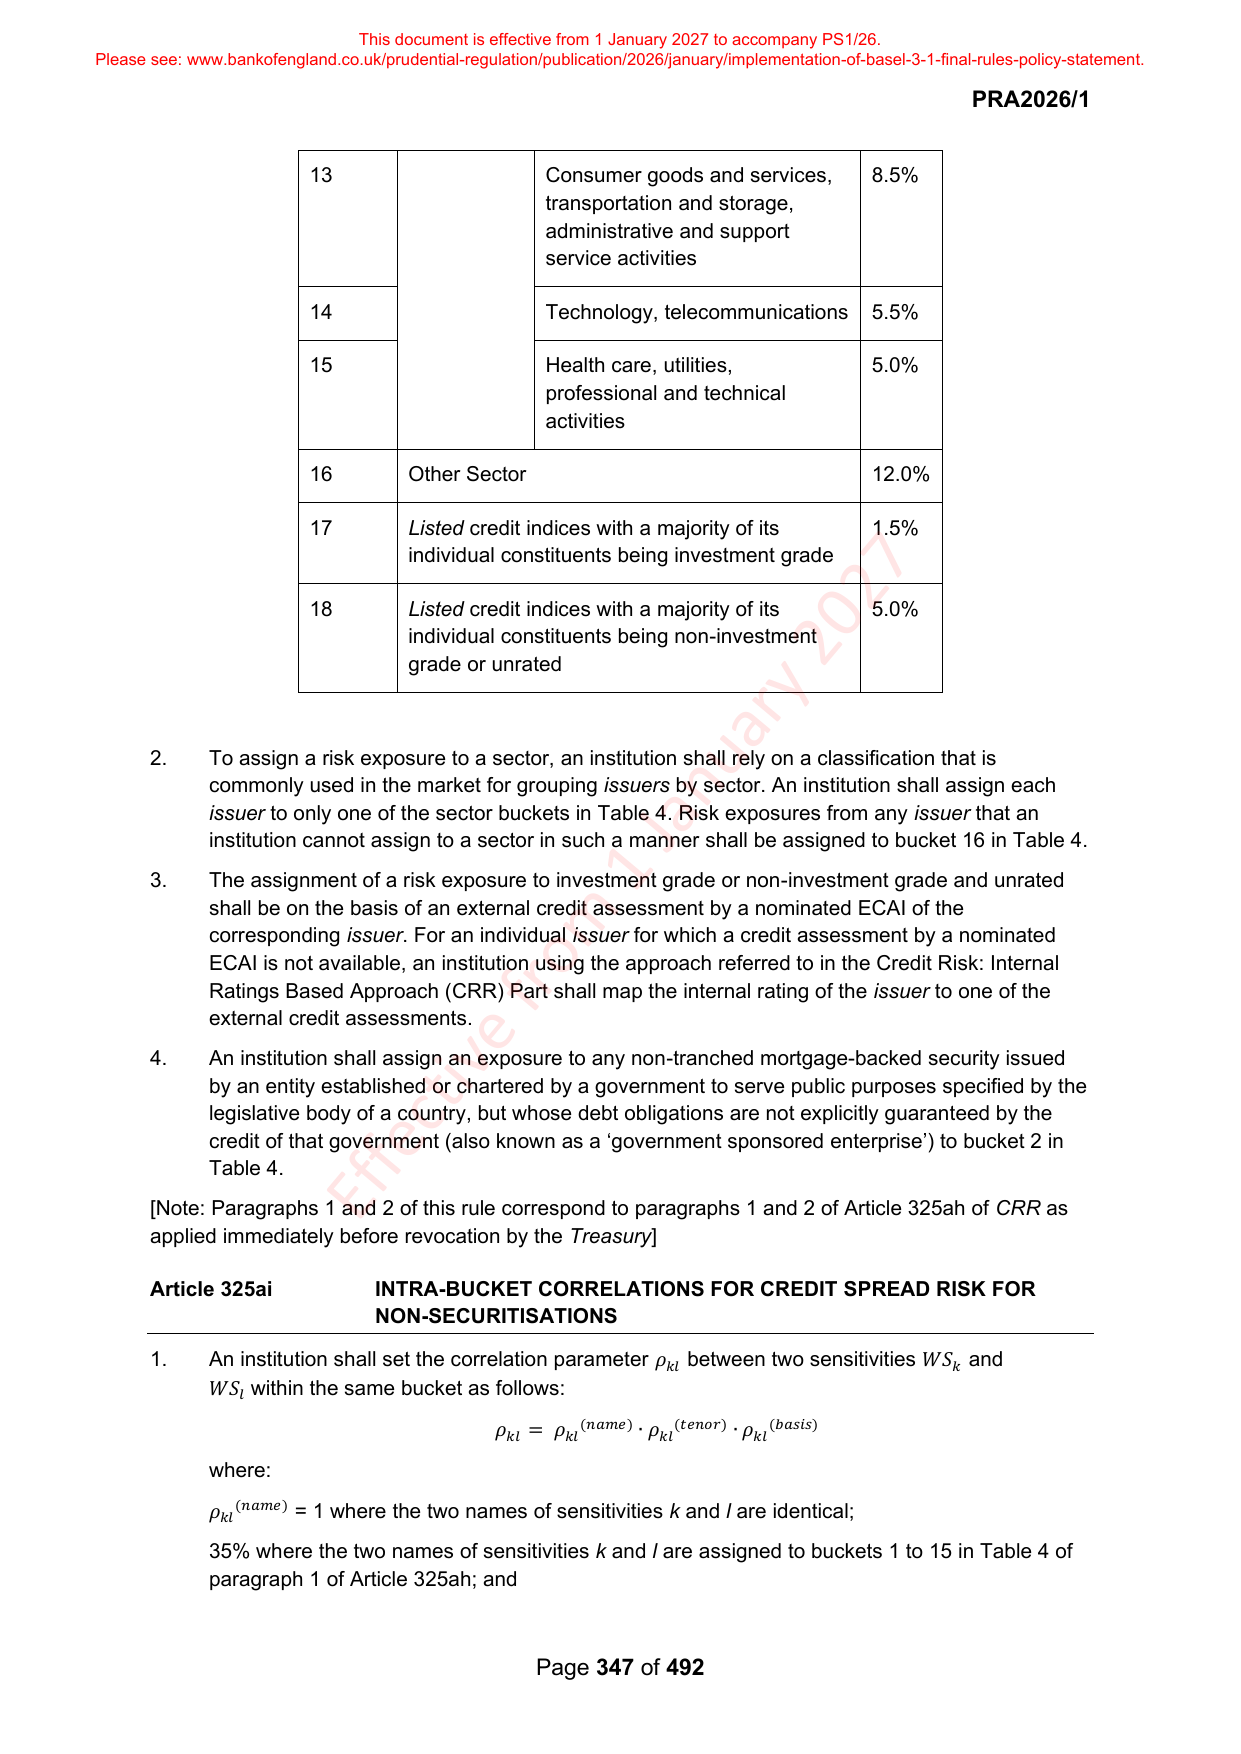
18491 13 Consumer goods and services, 8.5%
18492 transportation and storage,
18493 administrative and support
18494 service activities
18496 14 Technology, telecommunications 5.5%
18498 15 Health care, utilities, 5.0%
18499 professional and technical
18500 activities
18502 16 Other Sector 12.0%
18504 17 Listed credit indices with a majority of its 1.5%
18505 individual constituents being investment grade
18507 18 Listed credit indices with a majority of its 5.0%
18508 individual constituents being non-investment
18509 grade or unrated
18511 2. To assign a risk exposure to a sector, an institution shall rely on a classification that is
18512 commonly used in the market for grouping issuers by sector. An institution shall assign each
18513 issuer to only one of the sector buckets in Table 4. Risk exposures from any issuer that an
18514 institution cannot assign to a sector in such a manner shall be assigned to bucket 16 in Table 4.
18515 3. The assignment of a risk exposure to investment grade or non-investment grade and unrated
18516 shall be on the basis of an external credit assessment by a nominated ECAI of the
18517 corresponding issuer. For an individual issuer for which a credit assessment by a nominated
18518 ECAI is not available, an institution using the approach referred to in the Credit Risk: Internal
18519 Ratings Based Approach (CRR) Part shall map the internal rating of the issuer to one of the
18520 external credit assessments.
18521 4. An institution shall assign an exposure to any non-tranched mortgage-backed security issued
18522 by an entity established or chartered by a government to serve public purposes specified by the
18523 legislative body of a country, but whose debt obligations are not explicitly guaranteed by the
18524 credit of that government (also known as a ‘government sponsored enterprise’) to bucket 2 in
18525 Table 4.
18526 [Note: Paragraphs 1 and 2 of this rule correspond to paragraphs 1 and 2 of Article 325ah of CRR as
18527 applied immediately before revocation by the Treasury]
18529 Article 325ai INTRA-BUCKET CORRELATIONS FOR CREDIT SPREAD RISK FOR
18530 NON-SECURITISATIONS
18532 1. An institution shall set the correlation parameter 𝜌 𝑘𝑙 between two sensitivities 𝑊𝑆 𝑘 and
18533 𝑊𝑆 𝑙 within the same bucket as follows:
18534 (𝑛𝑎𝑚𝑒) (𝑡𝑒𝑛𝑜𝑟) (𝑏𝑎𝑠𝑖𝑠)
18535 𝜌 𝑘𝑙 = 𝜌 𝑘𝑙 ∙ 𝜌 𝑘𝑙 ∙ 𝜌 𝑘𝑙
18536 where:
18537 (𝑛𝑎𝑚𝑒) = 1 where the two names of sensitivities k and l are identical;
18538 𝜌 𝑘𝑙
18539 35% where the two names of sensitivities k and l are assigned to buckets 1 to 15 in Table 4 of
18540 paragraph 1 of Article 325ah; and
18542 Page 347 of 492