17584 This document is effective from 1 January 2027 to accompany PS1/26.
17585Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
17586 PRA2026/1
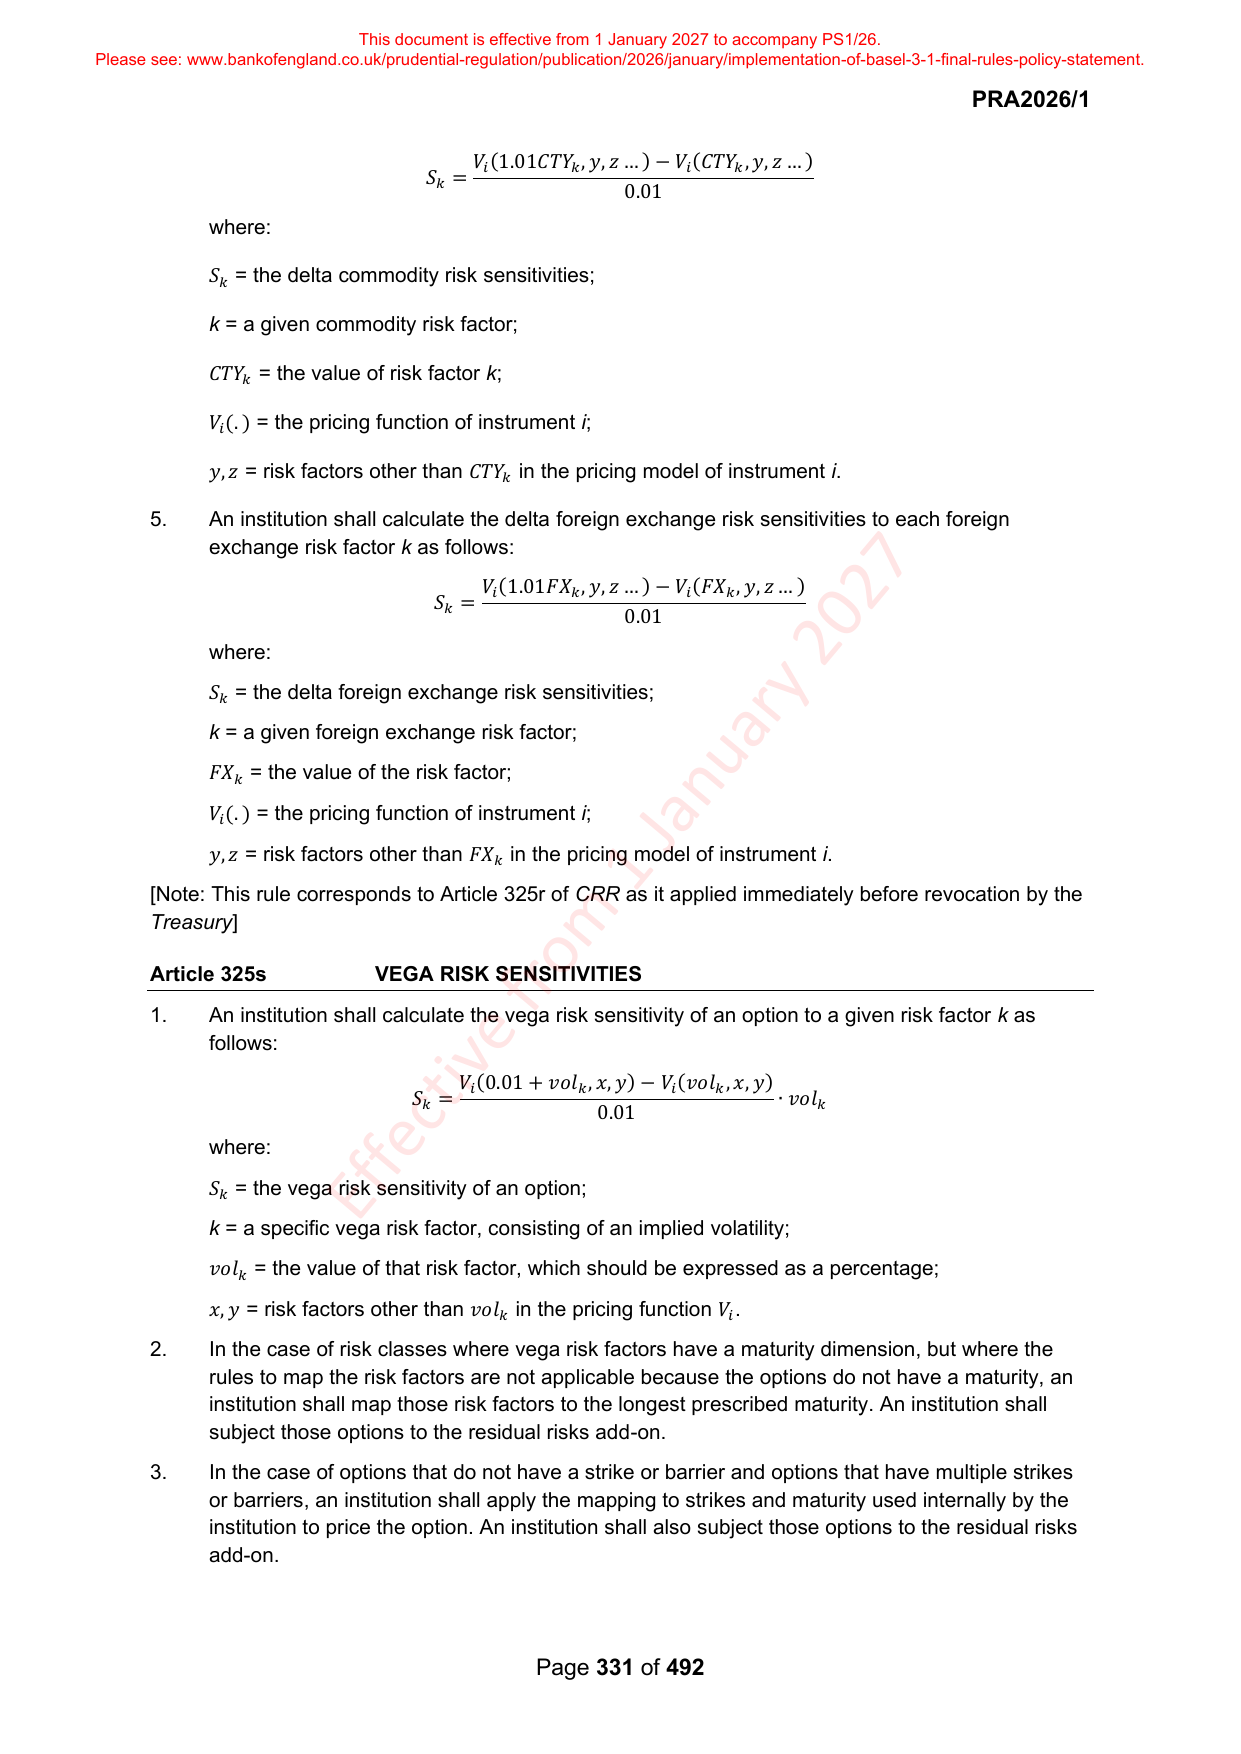
17588 𝑉 𝑖 (1.01𝐶𝑇𝑌 𝑘 , 𝑦, 𝑧 … ) − 𝑉 𝑖 (𝐶𝑇𝑌 𝑘 , 𝑦, 𝑧 … )
17589 𝑆 𝑘 =
17590 0.01
17591 where:
17593 𝑆 𝑘 = the delta commodity risk sensitivities;
17595 k = a given commodity risk factor;
17597 𝐶𝑇𝑌 𝑘 = the value of risk factor k;
17599 𝑉 𝑖 (. ) = the pricing function of instrument i;
17601 𝑦, 𝑧 = risk factors other than 𝐶𝑇𝑌 𝑘 in the pricing model of instrument i.
17603 5. An institution shall calculate the delta foreign exchange risk sensitivities to each foreign
17604 exchange risk factor k as follows:
17606 𝑉 𝑖 (1.01𝐹𝑋 𝑘 , 𝑦, 𝑧 … ) − 𝑉 𝑖 (𝐹𝑋 𝑘 , 𝑦, 𝑧 … )
17607 𝑆 𝑘 =
17608 0.01
17609 where:
17611 𝑆 𝑘 = the delta foreign exchange risk sensitivities;
17612 k = a given foreign exchange risk factor;
17614 𝐹𝑋 𝑘 = the value of the risk factor;
17616 𝑉 𝑖 (. ) = the pricing function of instrument i;
17618 𝑦, 𝑧 = risk factors other than 𝐹𝑋 𝑘 in the pricing model of instrument i.
17619 [Note: This rule corresponds to Article 325r of CRR as it applied immediately before revocation by the
17620 Treasury]
17622 Article 325s VEGA RISK SENSITIVITIES
17623 1. An institution shall calculate the vega risk sensitivity of an option to a given risk factor k as
17624 follows:
17626 𝑉 𝑖 (0.01 + 𝑣𝑜𝑙 𝑘 , 𝑥, 𝑦) − 𝑉 𝑖 (𝑣𝑜𝑙 𝑘 , 𝑥, 𝑦)
17627 𝑆 𝑘 = ∙ 𝑣𝑜𝑙 𝑘
17628 0.01
17629 where:
17631 𝑆 𝑘 = the vega risk sensitivity of an option;
17632 k = a specific vega risk factor, consisting of an implied volatility;
17634 𝑣𝑜𝑙 𝑘 = the value of that risk factor, which should be expressed as a percentage;
17636 𝑥, 𝑦 = risk factors other than 𝑣𝑜𝑙 𝑘 in the pricing function 𝑉 𝑖 .
17637 2. In the case of risk classes where vega risk factors have a maturity dimension, but where the
17638 rules to map the risk factors are not applicable because the options do not have a maturity, an
17639 institution shall map those risk factors to the longest prescribed maturity. An institution shall
17640 subject those options to the residual risks add-on.
17641 3. In the case of options that do not have a strike or barrier and options that have multiple strikes
17642 or barriers, an institution shall apply the mapping to strikes and maturity used internally by the
17643 institution to price the option. An institution shall also subject those options to the residual risks
17644 add-on.
17646 Page 331 of 492