14919 This document is effective from 1 January 2027 to accompany PS1/26.
14920Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
14921 PRA2026/1
14923 𝑙𝑜𝑠𝑠 𝑥 = the loss resulting from point (a);
14925 𝑙𝑜𝑠𝑠 𝐻𝑖𝑠𝑡 + = the loss that would result from the greatest historically observed 10-day increase
14926 in the non-modellable risk factor since 1 January 2007;
14928 𝑙𝑜𝑠𝑠 𝐻𝑖𝑠𝑡 − = the loss that would result from the greatest historically observed 10-day decrease
14929 in the non-modellable risk factor since 1 January 2007;
14930 (c) it shall multiply the maximum loss obtained in accordance with point b by
14932 max (20,LH)
14933 √ ;
14934 10
14936 where:
14938 𝐿𝐻= liquidity horizon of non-modellable risk factor j, as set out in Article 325bd;
14940 and
14942 (d) it shall identify the regulatory extreme scenario of future shock as the shock leading to the
14943 stress scenario risk measure being the scaled maximum loss identified in point (c).
14945 An institution shall not use the regulatory extreme scenario of future shock to calculate a single
14946 stress scenario risk measure for more than one non-modellable risk factor in a standardised
14947 bucket.
14948 Aggregation of stress scenario risk measures
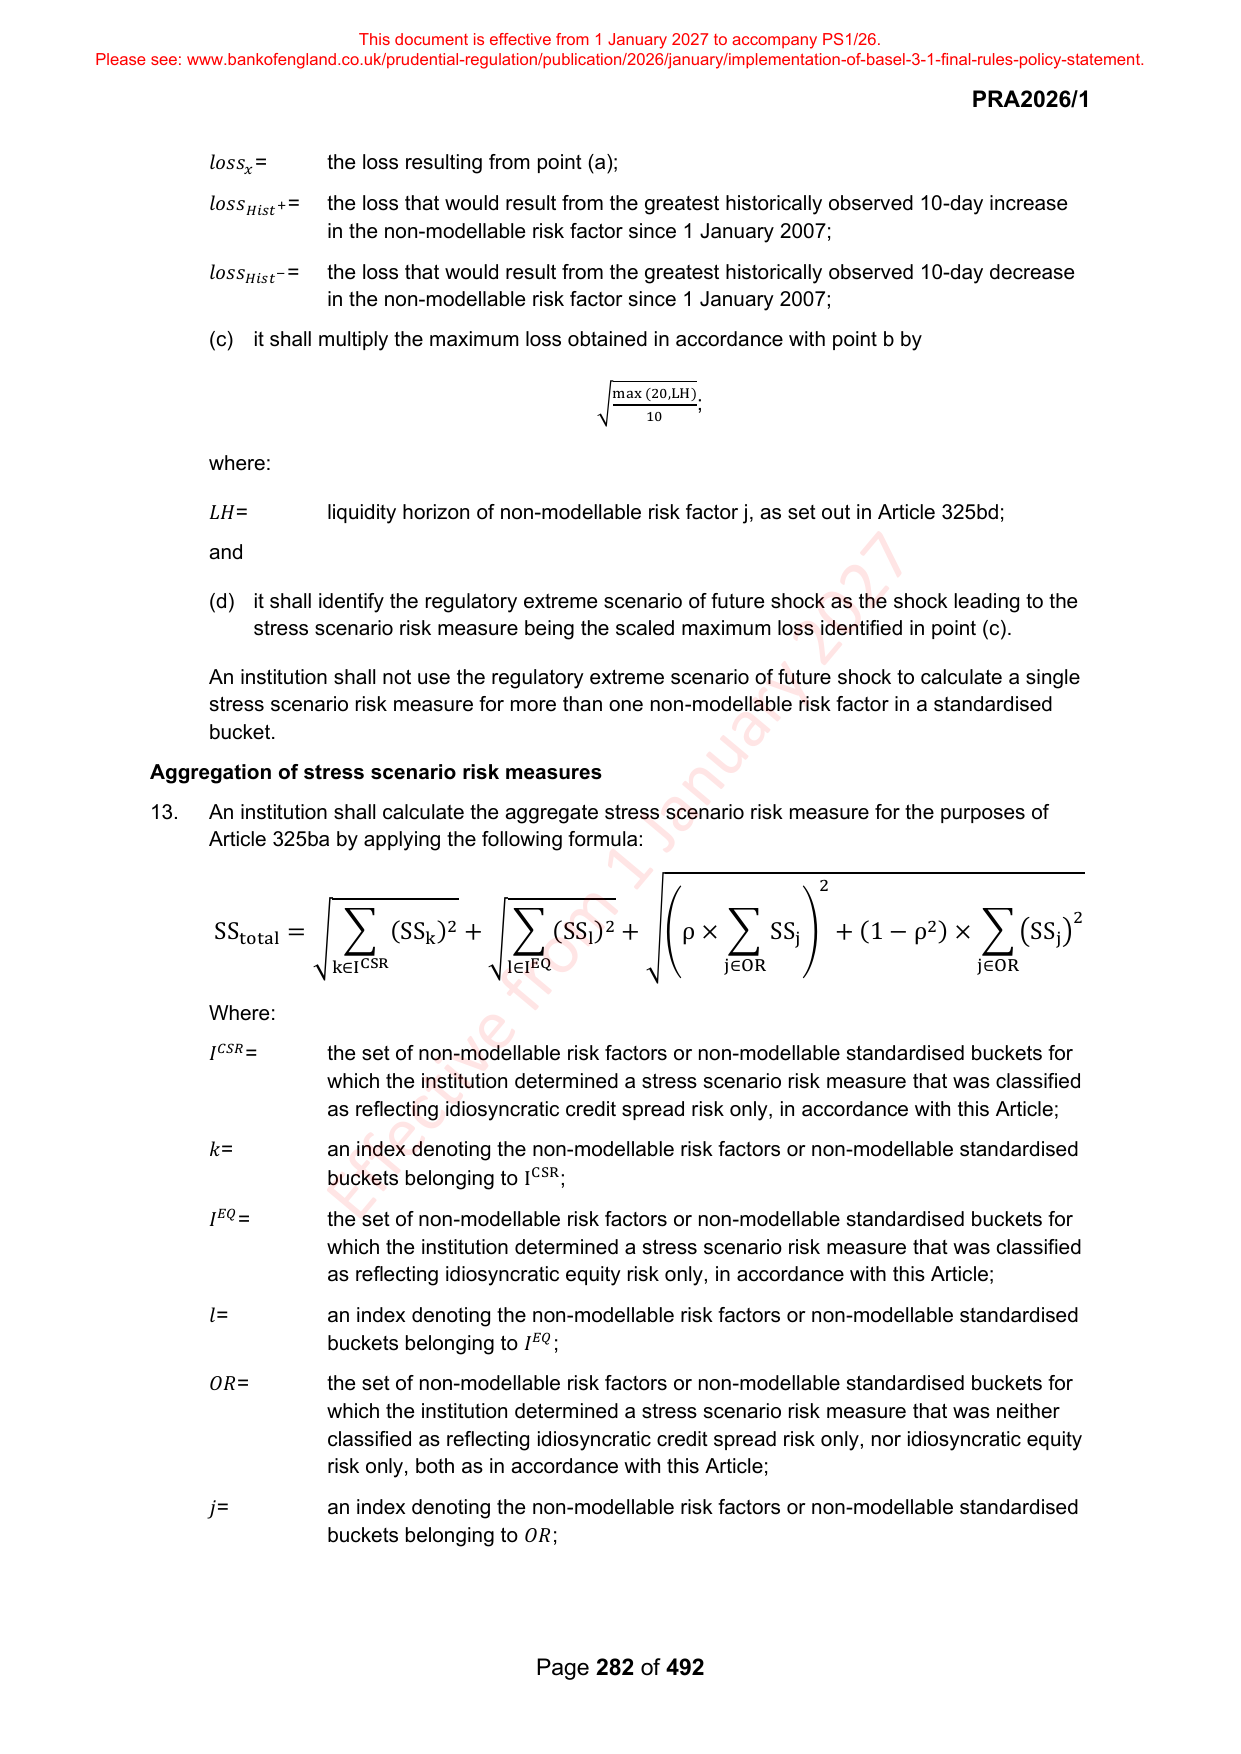
14949 13. An institution shall calculate the aggregate stress scenario risk measure for the purposes of
14950 Article 325ba by applying the following formula:
14952 2
14953 2
14954 SS = ∑ (SS ) 2 + ∑ (SS ) 2 + √(ρ × ∑ SS ) + (1 − ρ 2 ) × ∑ (SS )
14955 total √ k √ l j j
14956 k∈I CSR l∈I EQ j∈OR j∈OR
14958 Where:
14959 𝐶𝑆𝑅 = the set of non-modellable risk factors or non-modellable standardised buckets for
14960 𝐼
14961 which the institution determined a stress scenario risk measure that was classified
14962 as reflecting idiosyncratic credit spread risk only, in accordance with this Article;
14964 𝑘= an index denoting the non-modellable risk factors or non-modellable standardised
14965 buckets belonging to CSR ;
14966 I
14968 𝐸𝑄 = the set of non-modellable risk factors or non-modellable standardised buckets for
14969 𝐼
14970 which the institution determined a stress scenario risk measure that was classified
14971 as reflecting idiosyncratic equity risk only, in accordance with this Article;
14973 𝑙= an index denoting the non-modellable risk factors or non-modellable standardised
14974 buckets belonging to 𝐸𝑄 ;
14975 𝐼
14977 𝑂𝑅= the set of non-modellable risk factors or non-modellable standardised buckets for
14978 which the institution determined a stress scenario risk measure that was neither
14979 classified as reflecting idiosyncratic credit spread risk only, nor idiosyncratic equity
14980 risk only, both as in accordance with this Article;
14982 𝑗= an index denoting the non-modellable risk factors or non-modellable standardised
14983 buckets belonging to 𝑂𝑅;
14985 Page 282 of 492