14089 This document is effective from 1 January 2027 to accompany PS1/26.
14090Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
14091 PRA2026/1
14093 (iv) consider as time series of ranks the time series of the labels obtained in accordance
14094 with points (ii) and (iii).
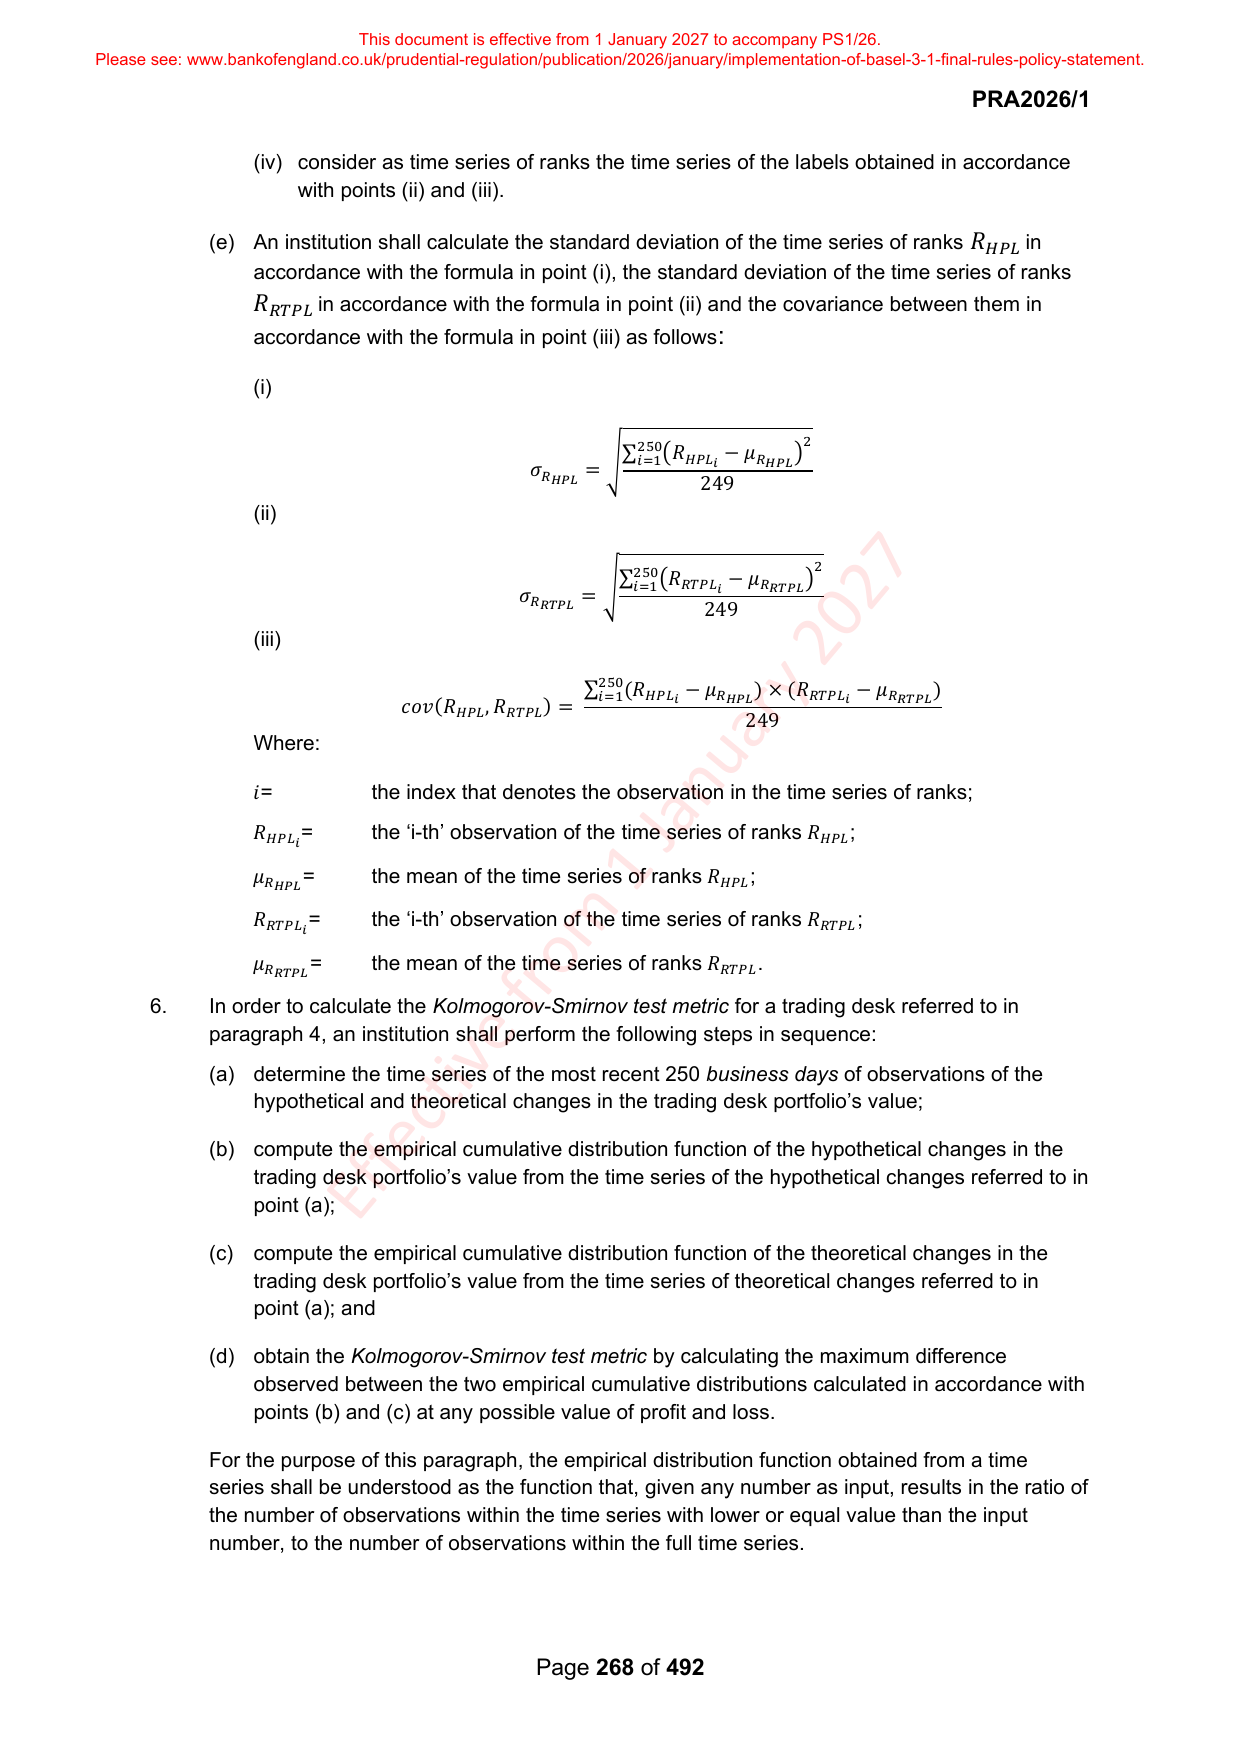
14096 (e) An institution shall calculate the standard deviation of the time series of ranks 𝑅 𝐻𝑃𝐿 in
14097 accordance with the formula in point (i), the standard deviation of the time series of ranks
14098 𝑅 𝑅𝑇𝑃𝐿 in accordance with the formula in point (ii) and the covariance between them in
14099 accordance with the formula in point (iii) as follows :
14101 (i)
14103 250 2
14104 ∑ 𝑖=1 (𝑅 𝐻𝑃𝐿 − 𝜇 𝑅 )
14105 𝜎 = √ 𝑖 𝐻𝑃𝐿
14106 𝑅 𝐻𝑃𝐿
14107 249
14108 (ii)
14110 2
14111 ∑ 250
14112 𝑖=1 (𝑅 𝑅𝑇𝑃𝐿 − 𝜇 𝑅 )
14113 𝜎 = √ 𝑖 𝑅𝑇𝑃𝐿
14114 𝑅 𝑅𝑇𝑃𝐿
14115 249
14116 (iii)
14118 ∑ 250
14119 𝑖=1 (𝑅 𝐻𝑃𝐿 − 𝜇 𝑅 ) × (𝑅 𝑅𝑇𝑃𝐿 − 𝜇 𝑅 )
14120 𝑖 𝐻𝑃𝐿 𝑖 𝑅𝑇𝑃𝐿
14121 𝑐𝑜𝑣(𝑅 𝐻𝑃𝐿 , 𝑅 𝑅𝑇𝑃𝐿 ) =
14122 249
14123 Where:
14125 𝑖= the index that denotes the observation in the time series of ranks;
14127 𝑅 𝐻𝑃𝐿 = the ‘i-th’ observation of the time series of ranks 𝑅 𝐻𝑃𝐿 ;
14128 𝑖
14130 𝜇 𝑅 = the mean of the time series of ranks 𝑅 𝐻𝑃𝐿 ;
14131 𝐻𝑃𝐿
14133 𝑅 𝑅𝑇𝑃𝐿 = the ‘i-th’ observation of the time series of ranks 𝑅 𝑅𝑇𝑃𝐿 ;
14134 𝑖
14136 𝜇 𝑅 = the mean of the time series of ranks 𝑅 𝑅𝑇𝑃𝐿 .
14137 𝑅𝑇𝑃𝐿
14139 6. In order to calculate the Kolmogorov-Smirnov test metric for a trading desk referred to in
14140 paragraph 4, an institution shall perform the following steps in sequence:
14141 (a) determine the time series of the most recent 250 business days of observations of the
14142 hypothetical and theoretical changes in the trading desk portfolio’s value;
14144 (b) compute the empirical cumulative distribution function of the hypothetical changes in the
14145 trading desk portfolio’s value from the time series of the hypothetical changes referred to in
14146 point (a);
14148 (c) compute the empirical cumulative distribution function of the theoretical changes in the
14149 trading desk portfolio’s value from the time series of theoretical changes referred to in
14150 point (a); and
14152 (d) obtain the Kolmogorov-Smirnov test metric by calculating the maximum difference
14153 observed between the two empirical cumulative distributions calculated in accordance with
14154 points (b) and (c) at any possible value of profit and loss.
14156 For the purpose of this paragraph, the empirical distribution function obtained from a time
14157 series shall be understood as the function that, given any number as input, results in the ratio of
14158 the number of observations within the time series with lower or equal value than the input
14159 number, to the number of observations within the full time series.
14161 Page 268 of 492