13507 This document is effective from 1 January 2027 to accompany PS1/26.
13508Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
13509 PRA2026/1
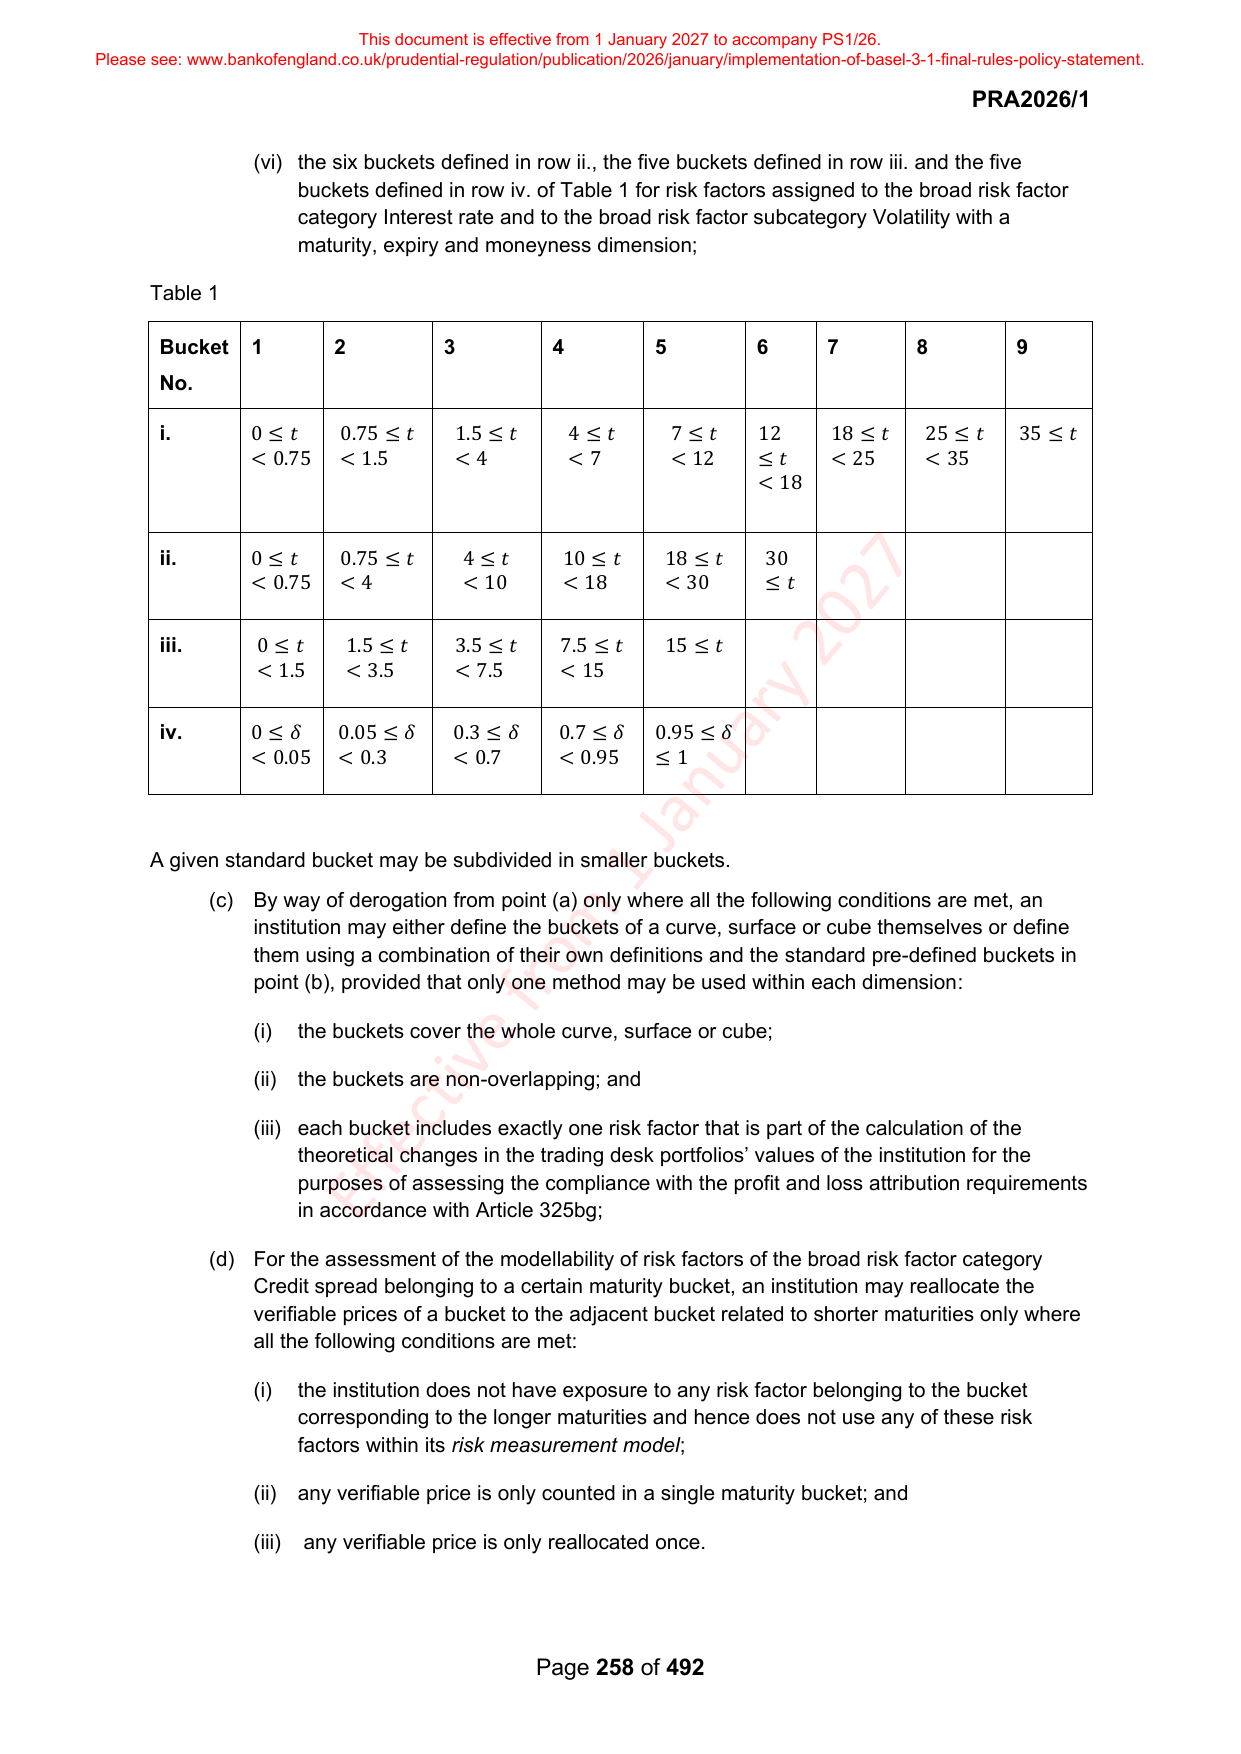
13511 (vi) the six buckets defined in row ii., the five buckets defined in row iii. and the five
13512 buckets defined in row iv. of Table 1 for risk factors assigned to the broad risk factor
13513 category Interest rate and to the broad risk factor subcategory Volatility with a
13514 maturity, expiry and moneyness dimension;
13516 Table 1
13518 Bucket 1 2 3 4 5 6 7 8 9
13519 No.
13521 i. 0≤𝑡 0.75 ≤ 𝑡 1.5 ≤ 𝑡 4≤𝑡 7≤𝑡 12 18 ≤ 𝑡 25 ≤ 𝑡 35 ≤ 𝑡
13522 < 0.75 < 1.5 <4 <7 < 12 ≤𝑡 < 25 < 35
13523 < 18
13525 ii. 0≤𝑡 0.75 ≤ 𝑡 4≤𝑡 10 ≤ 𝑡 18 ≤ 𝑡 30
13526 < 0.75 <4 < 10 < 18 < 30 ≤𝑡
13528 iii. 0≤𝑡 1.5 ≤ 𝑡 3.5 ≤ 𝑡 7.5 ≤ 𝑡 15 ≤ 𝑡
13529 < 1.5 < 3.5 < 7.5 < 15
13531 iv. 0≤𝛿 0.05 ≤ 𝛿 0.3 ≤ 𝛿 0.7 ≤ 𝛿 0.95 ≤ 𝛿
13532 < 0.05 < 0.3 < 0.7 < 0.95 ≤1
13534 A given standard bucket may be subdivided in smaller buckets.
13535 (c) By way of derogation from point (a) only where all the following conditions are met, an
13536 institution may either define the buckets of a curve, surface or cube themselves or define
13537 them using a combination of their own definitions and the standard pre-defined buckets in
13538 point (b), provided that only one method may be used within each dimension:
13540 (i) the buckets cover the whole curve, surface or cube;
13542 (ii) the buckets are non-overlapping; and
13544 (iii) each bucket includes exactly one risk factor that is part of the calculation of the
13545 theoretical changes in the trading desk portfolios’ values of the institution for the
13546 purposes of assessing the compliance with the profit and loss attribution requirements
13547 in accordance with Article 325bg;
13549 (d) For the assessment of the modellability of risk factors of the broad risk factor category
13550 Credit spread belonging to a certain maturity bucket, an institution may reallocate the
13551 verifiable prices of a bucket to the adjacent bucket related to shorter maturities only where
13552 all the following conditions are met:
13554 (i) the institution does not have exposure to any risk factor belonging to the bucket
13555 corresponding to the longer maturities and hence does not use any of these risk
13556 factors within its risk measurement model;
13558 (ii) any verifiable price is only counted in a single maturity bucket; and
13560 (iii) any verifiable price is only reallocated once.
13562 Page 258 of 492