13094 This document is effective from 1 January 2027 to accompany PS1/26.
13095Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
13096 PRA2026/1
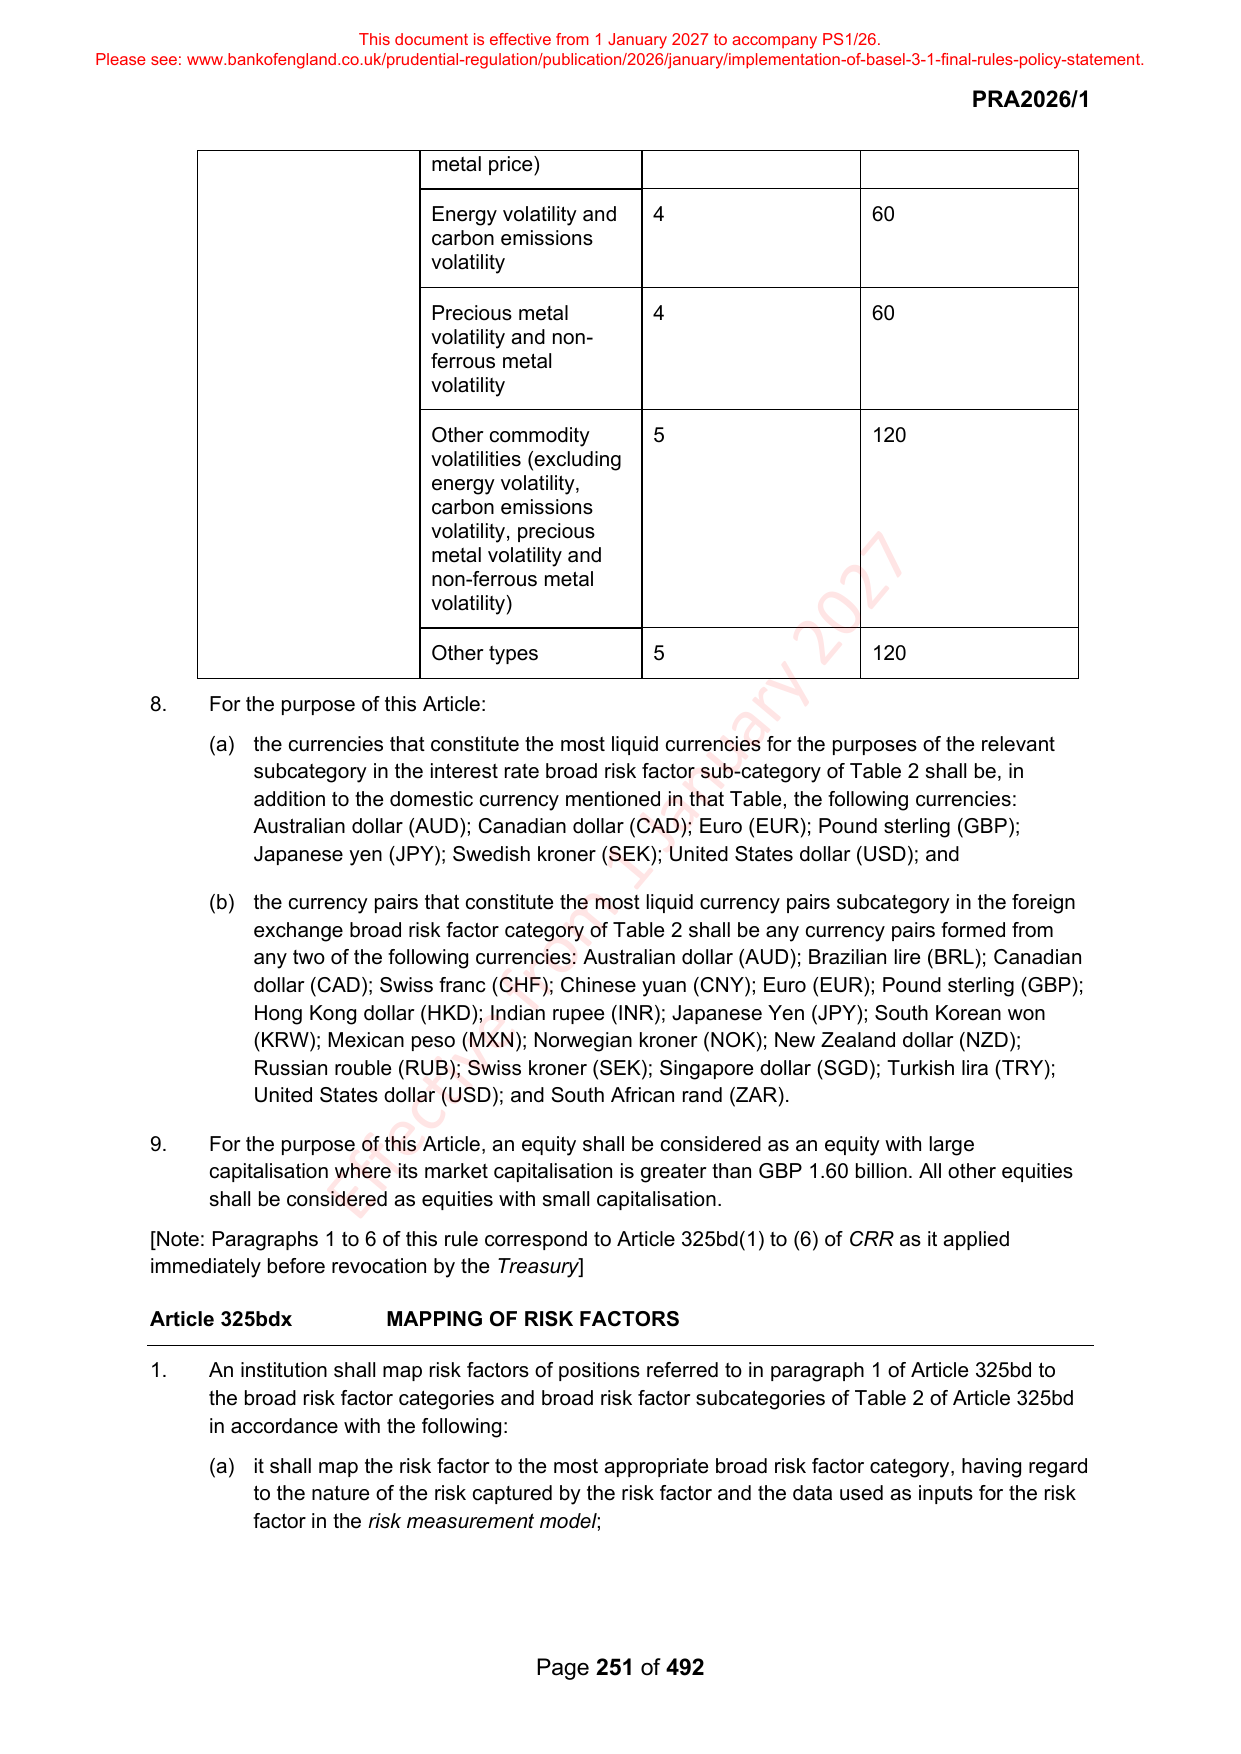
13098 metal price)
13100 Energy volatility and 4 60
13101 carbon emissions
13102 volatility
13104 Precious metal 4 60
13105 volatility and non-
13106 ferrous metal
13107 volatility
13109 Other commodity 5 120
13110 volatilities (excluding
13111 energy volatility,
13112 carbon emissions
13113 volatility, precious
13114 metal volatility and
13115 non-ferrous metal
13116 volatility)
13118 Other types 5 120
13120 8. For the purpose of this Article:
13121 (a) the currencies that constitute the most liquid currencies for the purposes of the relevant
13122 subcategory in the interest rate broad risk factor sub-category of Table 2 shall be, in
13123 addition to the domestic currency mentioned in that Table, the following currencies:
13124 Australian dollar (AUD); Canadian dollar (CAD); Euro (EUR); Pound sterling (GBP);
13125 Japanese yen (JPY); Swedish kroner (SEK); United States dollar (USD); and
13127 (b) the currency pairs that constitute the most liquid currency pairs subcategory in the foreign
13128 exchange broad risk factor category of Table 2 shall be any currency pairs formed from
13129 any two of the following currencies: Australian dollar (AUD); Brazilian lire (BRL); Canadian
13130 dollar (CAD); Swiss franc (CHF); Chinese yuan (CNY); Euro (EUR); Pound sterling (GBP);
13131 Hong Kong dollar (HKD); Indian rupee (INR); Japanese Yen (JPY); South Korean won
13132 (KRW); Mexican peso (MXN); Norwegian kroner (NOK); New Zealand dollar (NZD);
13133 Russian rouble (RUB); Swiss kroner (SEK); Singapore dollar (SGD); Turkish lira (TRY);
13134 United States dollar (USD); and South African rand (ZAR).
13136 9. For the purpose of this Article, an equity shall be considered as an equity with large
13137 capitalisation where its market capitalisation is greater than GBP 1.60 billion. All other equities
13138 shall be considered as equities with small capitalisation.
13139 [Note: Paragraphs 1 to 6 of this rule correspond to Article 325bd(1) to (6) of CRR as it applied
13140 immediately before revocation by the Treasury]
13142 Article 325bdx MAPPING OF RISK FACTORS
13144 1. An institution shall map risk factors of positions referred to in paragraph 1 of Article 325bd to
13145 the broad risk factor categories and broad risk factor subcategories of Table 2 of Article 325bd
13146 in accordance with the following:
13147 (a) it shall map the risk factor to the most appropriate broad risk factor category, having regard
13148 to the nature of the risk captured by the risk factor and the data used as inputs for the risk
13149 factor in the risk measurement model;
13151 Page 251 of 492