12975 This document is effective from 1 January 2027 to accompany PS1/26.
12976Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
12977 PRA2026/1
12979 institution takes such a decision, the longer liquidity horizon shall apply to all the modellable risk
12980 factors of the positions assigned to that trading desk that have been mapped to that broad sub-
12981 category of risk factors for the purpose of calculating the partial expected shortfall measures in
12982 accordance with point (c) of Article 325bc(1).
12983 An institution shall notify the PRA of the trading desks and the broad sub-categories of risk
12984 factors to which it decides to apply the treatment referred to in this paragraph.
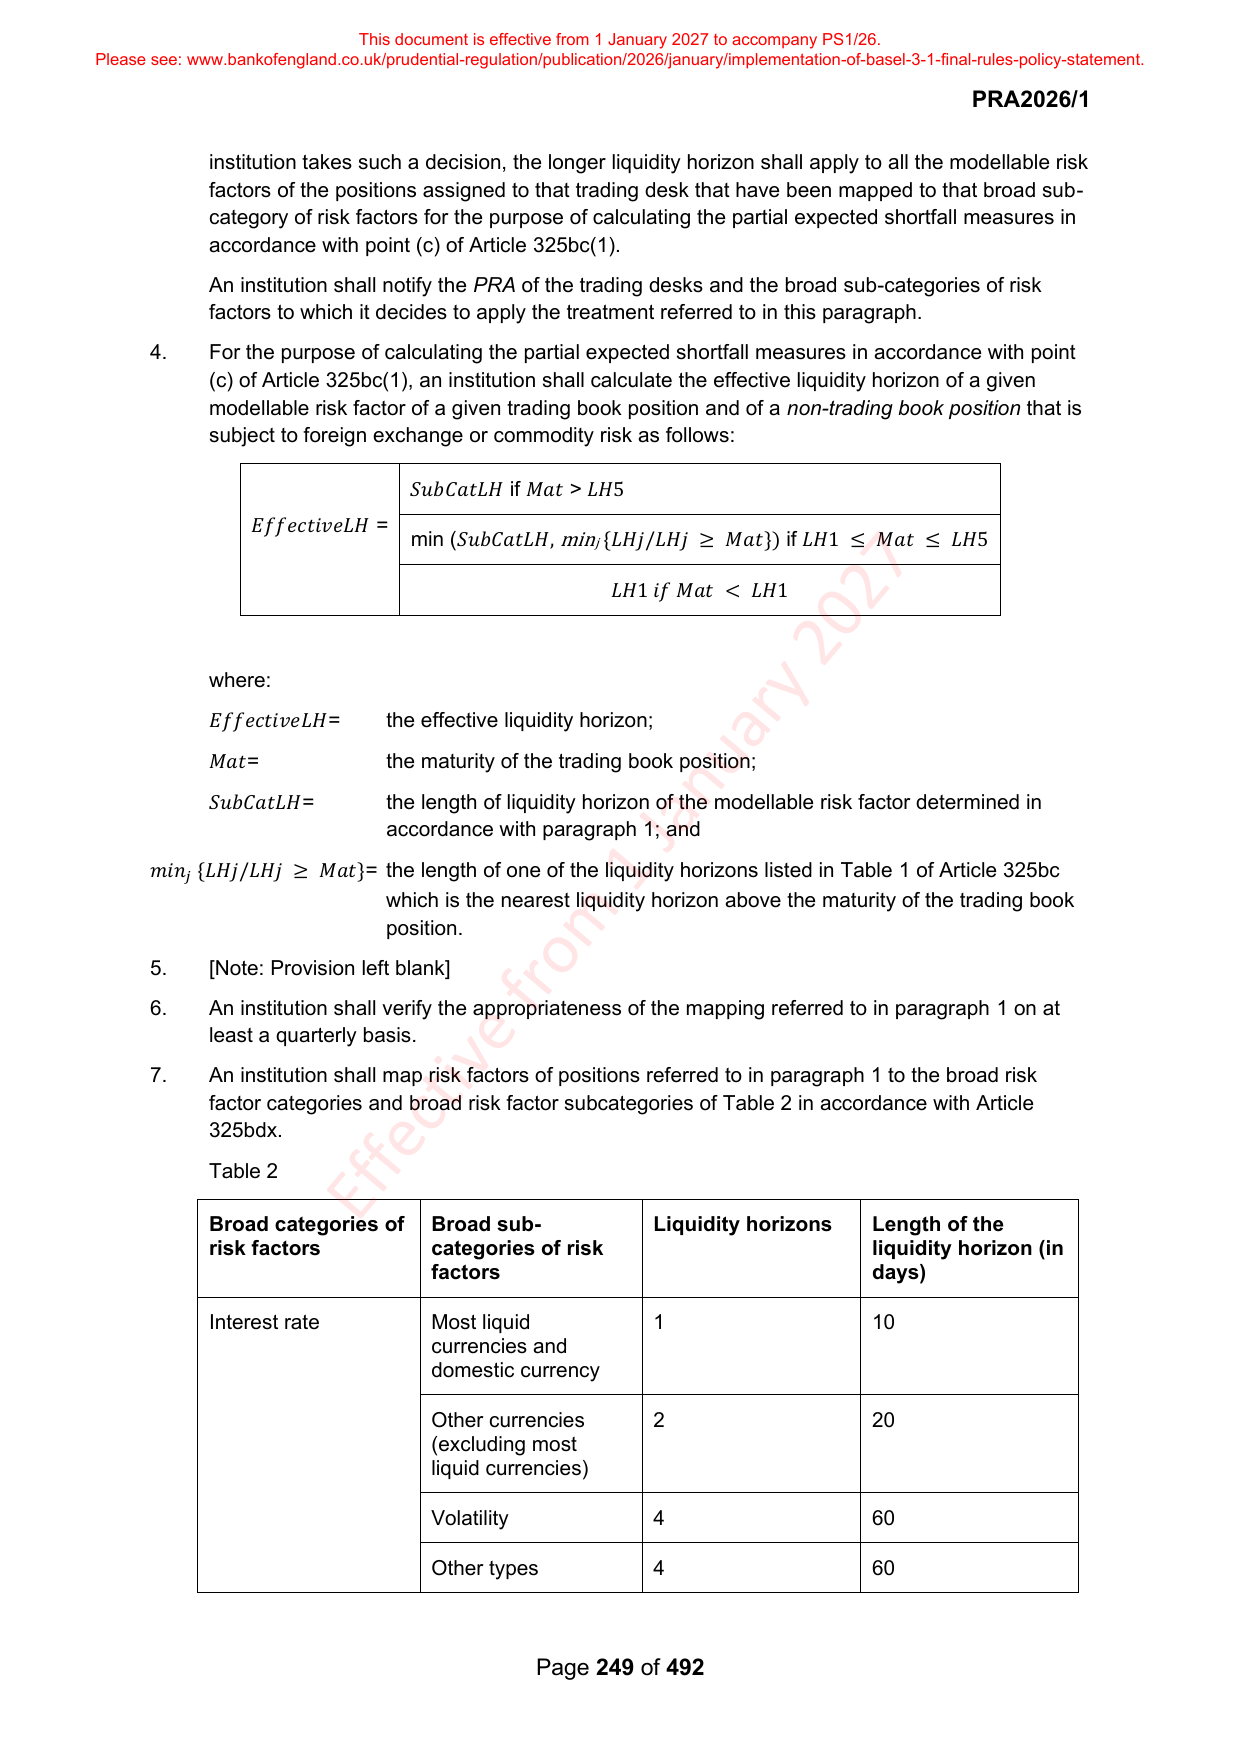
12985 4. For the purpose of calculating the partial expected shortfall measures in accordance with point
12986 (c) of Article 325bc(1), an institution shall calculate the effective liquidity horizon of a given
12987 modellable risk factor of a given trading book position and of a non-trading book position that is
12988 subject to foreign exchange or commodity risk as follows:
12990 𝑆𝑢𝑏𝐶𝑎𝑡𝐿𝐻 if 𝑀𝑎𝑡 > 𝐿𝐻5
12991 𝐸𝑓𝑓𝑒𝑐𝑡𝑖𝑣𝑒𝐿𝐻 =
12992 min (𝑆𝑢𝑏𝐶𝑎𝑡𝐿𝐻, min j {𝐿𝐻𝑗/𝐿𝐻𝑗 ≥ 𝑀𝑎𝑡}) if 𝐿𝐻1 ≤ 𝑀𝑎𝑡 ≤ 𝐿𝐻5
12994 𝐿𝐻1 𝑖𝑓 𝑀𝑎𝑡 < 𝐿𝐻1
12996 where:
12998 𝐸𝑓𝑓𝑒𝑐𝑡𝑖𝑣𝑒𝐿𝐻= the effective liquidity horizon;
13000 𝑀𝑎𝑡= the maturity of the trading book position;
13002 𝑆𝑢𝑏𝐶𝑎𝑡𝐿𝐻= the length of liquidity horizon of the modellable risk factor determined in
13003 accordance with paragraph 1; and
13005 𝑚𝑖𝑛 𝑗 {𝐿𝐻𝑗/𝐿𝐻𝑗 ≥ 𝑀𝑎𝑡}= the length of one of the liquidity horizons listed in Table 1 of Article 325bc
13006 which is the nearest liquidity horizon above the maturity of the trading book
13007 position.
13008 5. [Note: Provision left blank]
13009 6. An institution shall verify the appropriateness of the mapping referred to in paragraph 1 on at
13010 least a quarterly basis.
13011 7. An institution shall map risk factors of positions referred to in paragraph 1 to the broad risk
13012 factor categories and broad risk factor subcategories of Table 2 in accordance with Article
13013 325bdx.
13014 Table 2
13016 Broad categories of Broad sub- Liquidity horizons Length of the
13017 risk factors categories of risk liquidity horizon (in
13018 factors days)
13020 Interest rate Most liquid 1 10
13021 currencies and
13022 domestic currency
13024 Other currencies 2 20
13025 (excluding most
13026 liquid currencies)
13028 Volatility 4 60
13030 Other types 4 60
13032 Page 249 of 492