12558 This document is effective from 1 January 2027 to accompany PS1/26.
12559Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
12560 PRA2026/1
12562 (a) min (IMA g&y +Capital surcharge + C U ;SA all desks )
12564 (b) max (IMA g&y - SA g&y ;0)
12566 Where:
12568 𝐼𝑀𝐴 𝑔&𝑦 = the own funds requirements calculated in accordance with this Article for the
12569 portfolio of all positions assigned to trading desks that meet the requirements set
12570 out in Article 325bf(3) for the preceding 12 months and have been classified as
12571 green or yellow desks among those in accordance with Article 325bg and for
12572 which the institution calculates the own funds requirements in accordance with this
12573 Part;
12575 𝑆𝐴 𝑔&𝑦 = the own funds requirements calculated in accordance with the Market Risk:
12576 Advanced Standardised Approach (CRR) Part for the portfolio of all positions
12577 assigned to trading desks that meet the requirements set out in Article 325bf(3) for
12578 the preceding 12 months and have been classified as green zone or yellow zone
12579 trading desks among those in accordance with Article 325bg and for which the
12580 institution has permission to calculate the own funds requirements using internal
12581 models in accordance with this Part;
12583 Capital surcharge = the capital surcharge calculated in accordance with paragraph 4 ;
12585 C U = the own funds requirements calculated in accordance with the Market Risk:
12586 Advanced Standardised Approach (CRR) Part for the portfolio of positions not
12587 assigned to trading desks for which the institution has permission to calculate the
12588 own funds requirements using internal models in accordance with this Part,
12589 including the positions that are assigned to red zone or orange zone trading desks
12590 as specified in Paragraph 7 of Article 325bg or to trading desks that cease to meet
12591 the requirements set out in Article 325bf(3) for the preceding 12 months;
12592 SA (all desks)= the own funds requirements of all trading book positions and all non-trading book
12593 positions generating foreign exchange or commodity risks in accordance with the
12594 Market Risk: Advanced Standardised Approach (CRR) Part.
12595 4. An institution which calculates the own funds requirements in accordance with this Part for
12596 positions assigned to trading desks that have been classified as yellow zone desks in
12597 accordance with Article 325bg shall compute, in relation to those positions, a capital surcharge
12598 in accordance with the following formula:
12600 𝐶𝑎𝑝𝑖𝑡𝑎𝑙 𝑠𝑢𝑟𝑐ℎ𝑎𝑟𝑔𝑒 = 𝑘 × max(𝑆𝐴 𝑔&𝑦 − 𝐼𝑀𝐴 𝑔&𝑦 ; 0)
12602 Where:
12604 𝑘= as specified in paragraph 5;
12606 𝐼𝑀𝐴 𝑔&𝑦 = as specified in paragraph 3;
12608 𝑆𝐴 𝑔&𝑦 = as specified in paragraph 3.
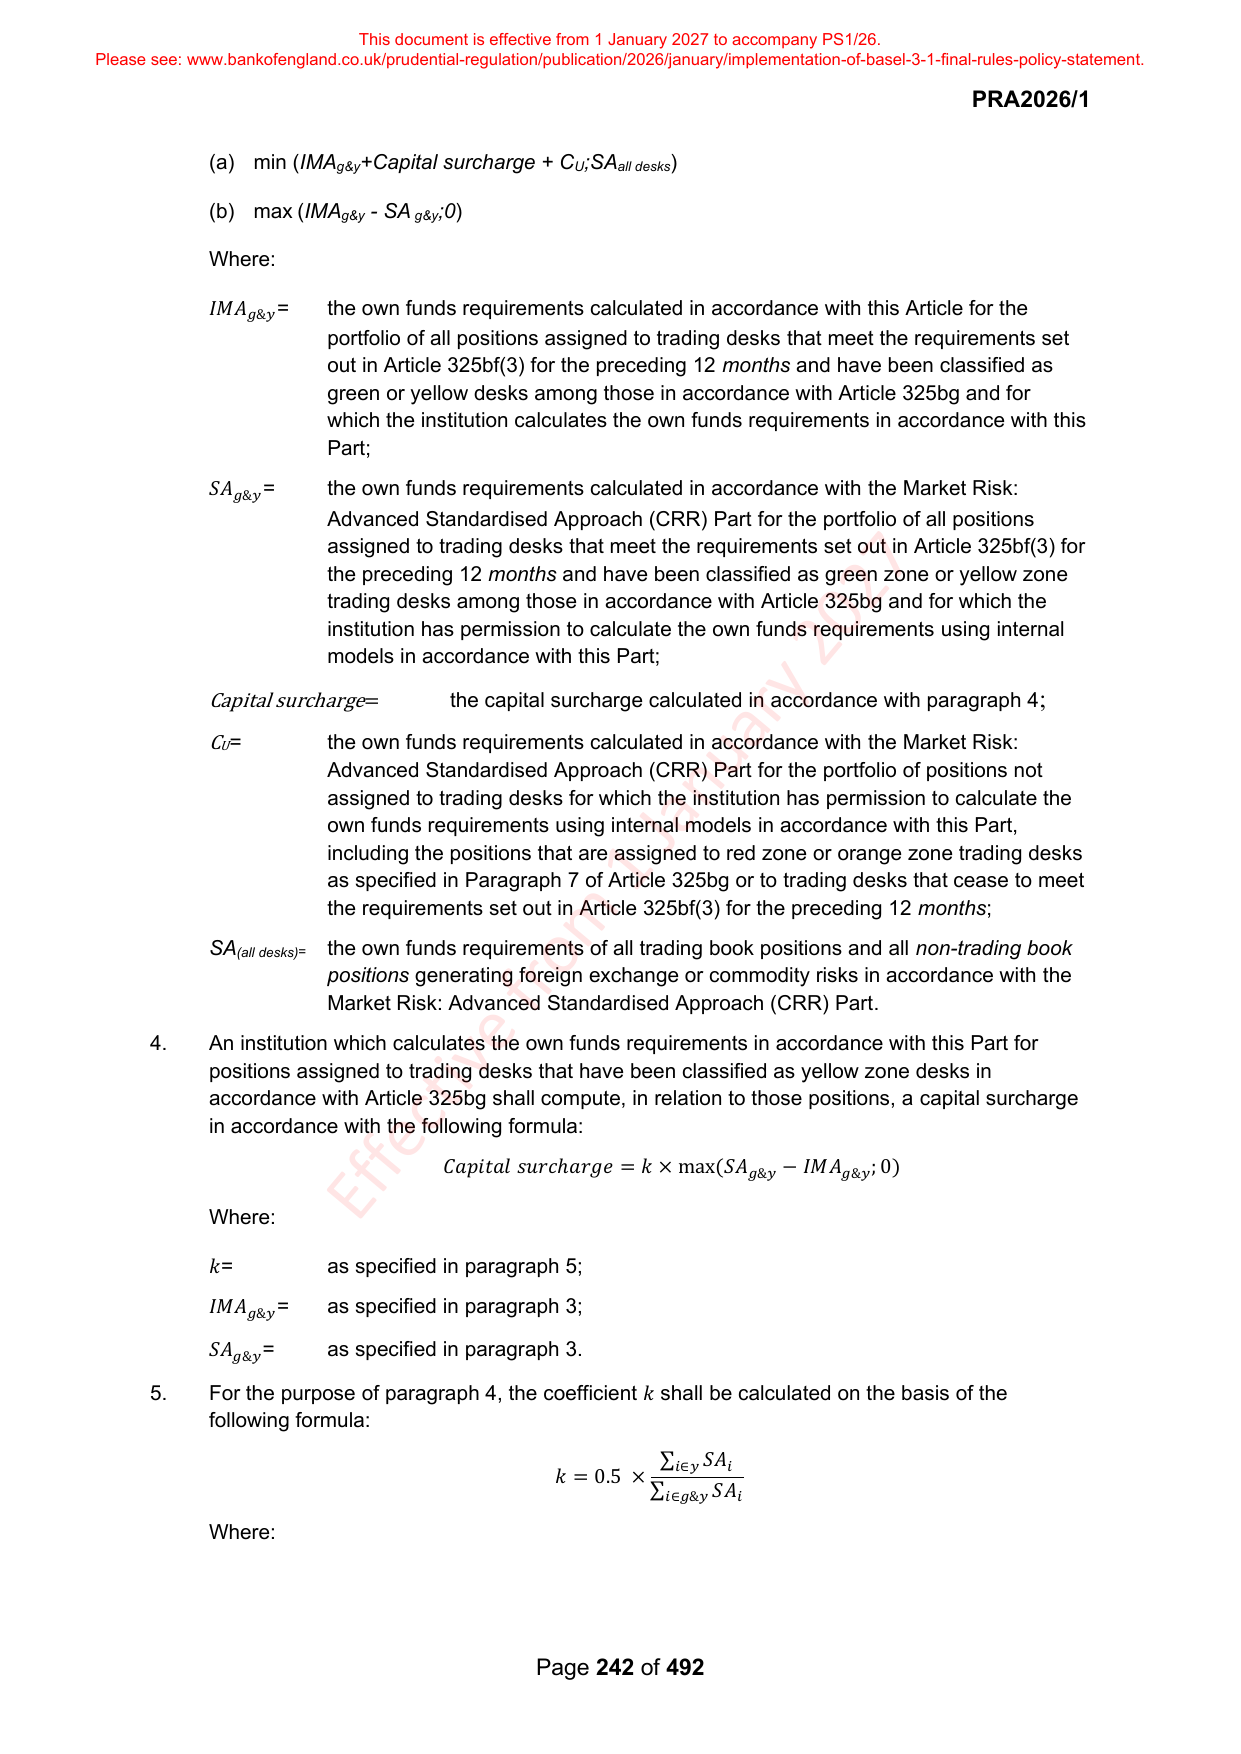
12610 5. For the purpose of paragraph 4, the coefficient 𝑘 shall be calculated on the basis of the
12611 following formula:
12612 ∑ 𝑖∈𝑦 𝑆𝐴 𝑖
12613 𝑘 = 0.5 ×
12614 ∑ 𝑖∈𝑔&𝑦 𝑆𝐴 𝑖
12615 Where:
12617 Page 242 of 492