11295 This document is effective from 1 January 2027 to accompany PS1/26.
11296Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
11297 PRA2026/1
11299 1A. For the purposes of point (2) of the definition of Parameter Substitution Method, the institution
11300 shall calculate the expected loss separately for the covered and uncovered parts of the
11301 exposure as follows:
11303 (a) The expected loss for the uncovered part, e n , shall be the expected loss of the exposure
11304 calculated in accordance with Credit Risk: Internal Ratings Based Approach (CRR) Part
11305 Article 158 as if there were no unfunded credit protection.
11307 (b) The expected loss for the covered part, e g , shall be PD ∙ LGD , where PD and LGD are as
11308 defined for the purposes of calculating r g in point (a) of paragraph 1.
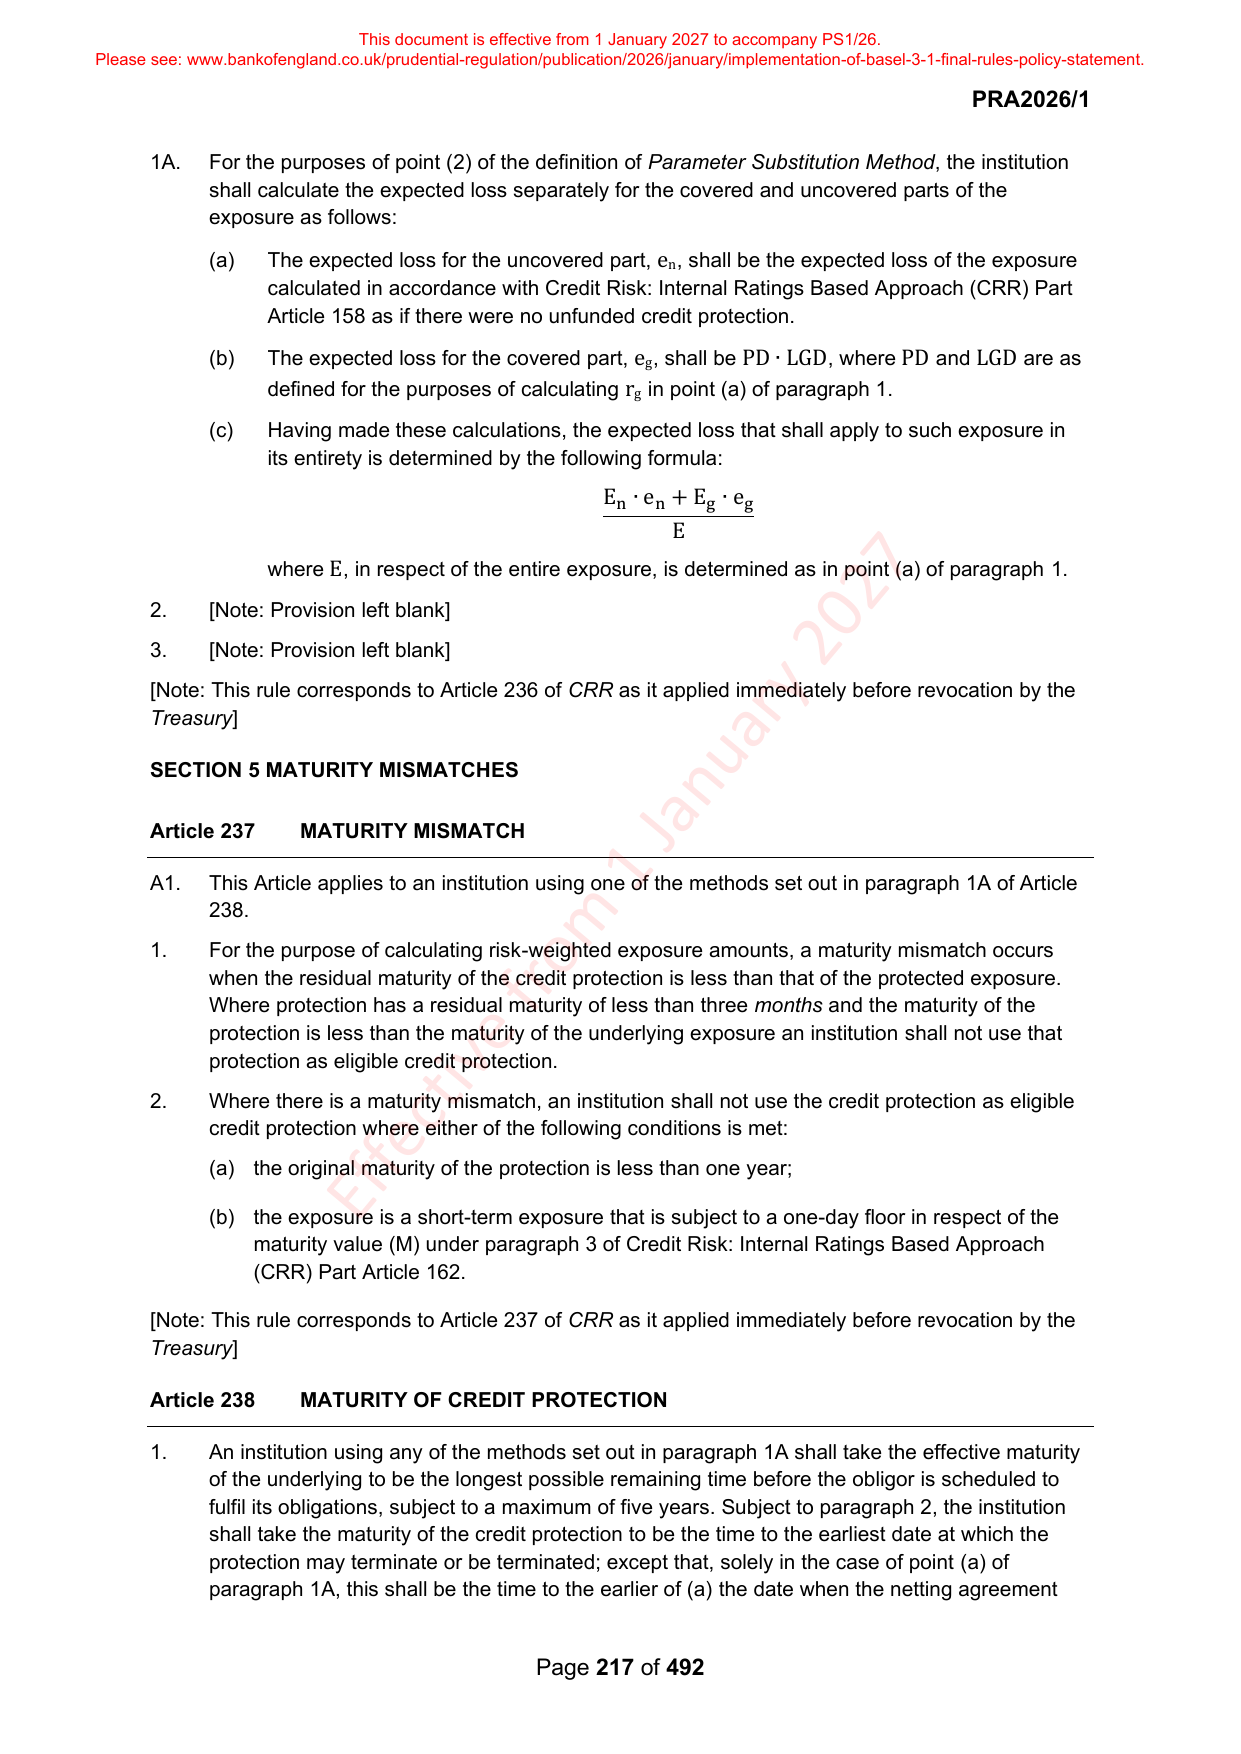
11309 (c) Having made these calculations, the expected loss that shall apply to such exposure in
11310 its entirety is determined by the following formula:
11311 E n ∙ e n + E g ∙ e g
11312 E
11313 where E , in respect of the entire exposure, is determined as in point (a) of paragraph 1.
11314 2. [Note: Provision left blank]
11315 3. [Note: Provision left blank]
11316 [Note: This rule corresponds to Article 236 of CRR as it applied immediately before revocation by the
11317 Treasury]
11319 SECTION 5 MATURITY MISMATCHES
11321 Article 237 MATURITY MISMATCH
11323 A1. This Article applies to an institution using one of the methods set out in paragraph 1A of Article
11324 238.
11325 1. For the purpose of calculating risk-weighted exposure amounts, a maturity mismatch occurs
11326 when the residual maturity of the credit protection is less than that of the protected exposure.
11327 Where protection has a residual maturity of less than three months and the maturity of the
11328 protection is less than the maturity of the underlying exposure an institution shall not use that
11329 protection as eligible credit protection.
11330 2. Where there is a maturity mismatch, an institution shall not use the credit protection as eligible
11331 credit protection where either of the following conditions is met:
11332 (a) the original maturity of the protection is less than one year;
11334 (b) the exposure is a short-term exposure that is subject to a one-day floor in respect of the
11335 maturity value (M) under paragraph 3 of Credit Risk: Internal Ratings Based Approach
11336 (CRR) Part Article 162.
11338 [Note: This rule corresponds to Article 237 of CRR as it applied immediately before revocation by the
11339 Treasury]
11341 Article 238 MATURITY OF CREDIT PROTECTION
11343 1. An institution using any of the methods set out in paragraph 1A shall take the effective maturity
11344 of the underlying to be the longest possible remaining time before the obligor is scheduled to
11345 fulfil its obligations, subject to a maximum of five years. Subject to paragraph 2, the institution
11346 shall take the maturity of the credit protection to be the time to the earliest date at which the
11347 protection may terminate or be terminated; except that, solely in the case of point (a) of
11348 paragraph 1A, this shall be the time to the earlier of (a) the date when the netting agreement
11350 Page 217 of 492