11124 This document is effective from 1 January 2027 to accompany PS1/26.
11125Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
11126 PRA2026/1
11128 (ii) for exposures where the institution calculates risk-weighted exposure
11129 amounts using the IRB Approach, the exposure value in accordance with
11130 Credit Risk: Internal Ratings Based Approach (CRR) Part Articles 166A to
11131 166D, with the exception that for the purposes of this paragraph the exposure
11132 value of an off-balance sheet item shall be 100% of its value;
11134 G A = the amount of credit protection as calculated under paragraphs 3 and 4 of Article
11135 233 ( ∗ ), further adjusted for any maturity mismatch as laid down in Articles 237 to
11136 G
11137 239.
11138 The risk weight that applies to the covered part shall be:
11140 r g = the risk weight of a comparable direct exposure to the protection provider as
11141 specified under the Credit Risk: Standardised Approach (CRR) Part and Chapter 2
11142 of Title II of Part Three of CRR.
11143 (b) The uncovered part shall be the remainder of the exposure, and the size of this part prior
11144 to the application of any applicable conversion factors, E n , shall be calculated by
11145 subtracting the size of the covered part (E g ) from the size of the total exposure ( E ).
11146 The risk weight that applies to the uncovered part shall be:
11148 r n = the risk weight of the exposure calculated as if there were no unfunded credit
11149 protection.
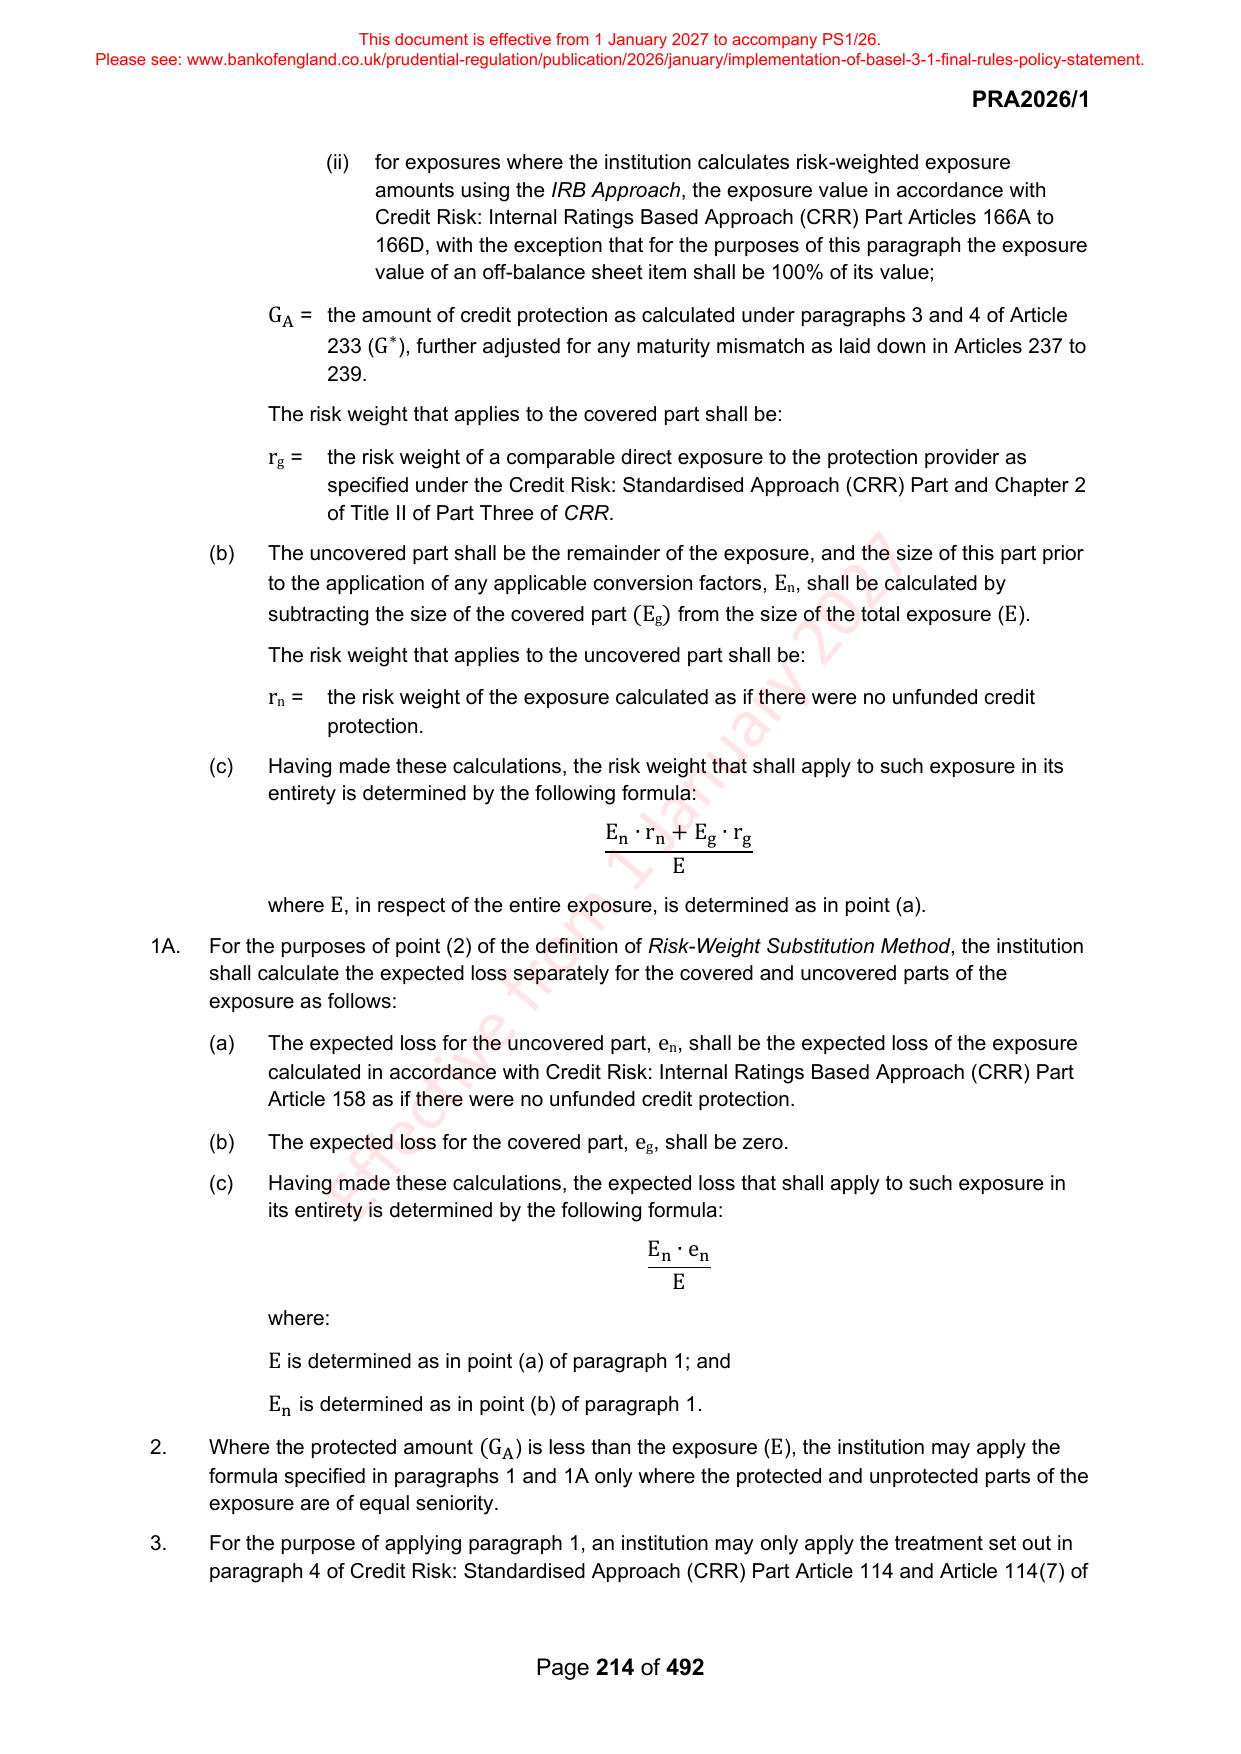
11150 (c) Having made these calculations, the risk weight that shall apply to such exposure in its
11151 entirety is determined by the following formula:
11152 E n ∙ r n + E g ∙ r g
11153 E
11154 where E , in respect of the entire exposure, is determined as in point (a).
11155 1A. For the purposes of point (2) of the definition of Risk-Weight Substitution Method, the institution
11156 shall calculate the expected loss separately for the covered and uncovered parts of the
11157 exposure as follows:
11159 (a) The expected loss for the uncovered part, e n , shall be the expected loss of the exposure
11160 calculated in accordance with Credit Risk: Internal Ratings Based Approach (CRR) Part
11161 Article 158 as if there were no unfunded credit protection.
11163 (b) The expected loss for the covered part, e g , shall be zero.
11164 (c) Having made these calculations, the expected loss that shall apply to such exposure in
11165 its entirety is determined by the following formula:
11166 E n ∙ e n
11167 E
11168 where:
11170 E is determined as in point (a) of paragraph 1; and
11172 E n is determined as in point (b) of paragraph 1.
11173 2. Where the protected amount (G A ) is less than the exposure ( E ), the institution may apply the
11174 formula specified in paragraphs 1 and 1A only where the protected and unprotected parts of the
11175 exposure are of equal seniority.
11176 3. For the purpose of applying paragraph 1, an institution may only apply the treatment set out in
11177 paragraph 4 of Credit Risk: Standardised Approach (CRR) Part Article 114 and Article 114(7) of
11179 Page 214 of 492