10653 This document is effective from 1 January 2027 to accompany PS1/26.
10654Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
10655 PRA2026/1
10657 Article 226 SCALING UP OF VOLATILITY ADJUSTMENT UNDER THE FINANCIAL
10658 COLLATERAL COMPREHENSIVE METHOD
10660 1. An institution using the Financial Collateral Comprehensive Method shall apply the volatility
10661 adjustments set out in Article 224 where there is daily revaluation. Where the frequency of
10662 revaluation is less than daily, the institution shall apply larger volatility adjustments. The
10663 institution shall calculate the larger volatility adjustments by scaling up the daily revaluation
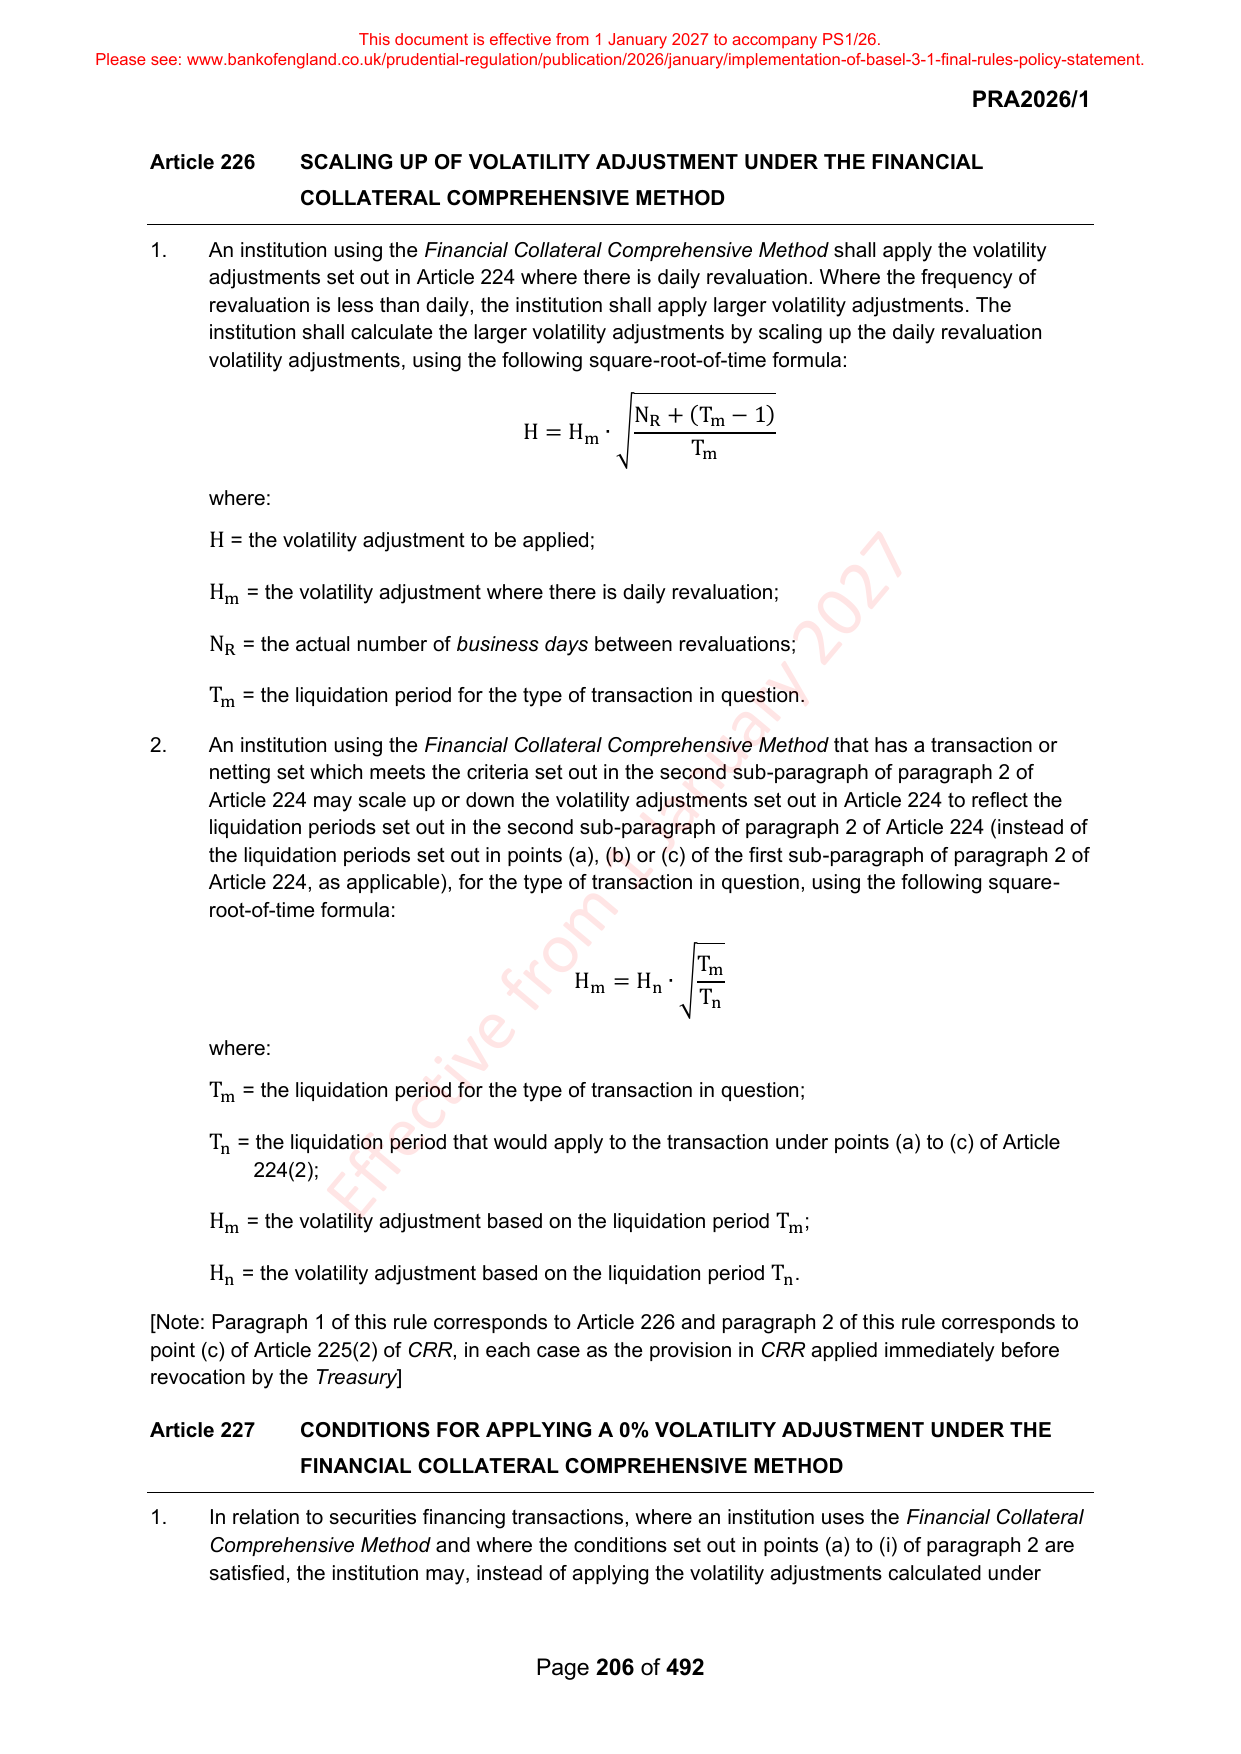
10664 volatility adjustments, using the following square-root-of-time formula:
10666 N R + (T m − 1)
10667 H = H m ∙ √
10668 T m
10670 where:
10672 H = the volatility adjustment to be applied;
10674 H m = the volatility adjustment where there is daily revaluation;
10676 N R = the actual number of business days between revaluations;
10678 T m = the liquidation period for the type of transaction in question.
10680 2. An institution using the Financial Collateral Comprehensive Method that has a transaction or
10681 netting set which meets the criteria set out in the second sub-paragraph of paragraph 2 of
10682 Article 224 may scale up or down the volatility adjustments set out in Article 224 to reflect the
10683 liquidation periods set out in the second sub-paragraph of paragraph 2 of Article 224 (instead of
10684 the liquidation periods set out in points (a), (b) or (c) of the first sub-paragraph of paragraph 2 of
10685 Article 224, as applicable), for the type of transaction in question, using the following square-
10686 root-of-time formula:
10688 T m
10689 H m = H n ∙ √
10690 T n
10692 where:
10694 T m = the liquidation period for the type of transaction in question;
10696 T n = the liquidation period that would apply to the transaction under points (a) to (c) of Article
10697 224(2);
10699 H m = the volatility adjustment based on the liquidation period T m ;
10701 H n = the volatility adjustment based on the liquidation period T n .
10703 [Note: Paragraph 1 of this rule corresponds to Article 226 and paragraph 2 of this rule corresponds to
10704 point (c) of Article 225(2) of CRR, in each case as the provision in CRR applied immediately before
10705 revocation by the Treasury]
10707 Article 227 CONDITIONS FOR APPLYING A 0% VOLATILITY ADJUSTMENT UNDER THE
10708 FINANCIAL COLLATERAL COMPREHENSIVE METHOD
10710 1. In relation to securities financing transactions, where an institution uses the Financial Collateral
10711 Comprehensive Method and where the conditions set out in points (a) to (i) of paragraph 2 are
10712 satisfied, the institution may, instead of applying the volatility adjustments calculated under
10714 Page 206 of 492