9939 This document is effective from 1 January 2027 to accompany PS1/26.
9940Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
9941 PRA2026/1
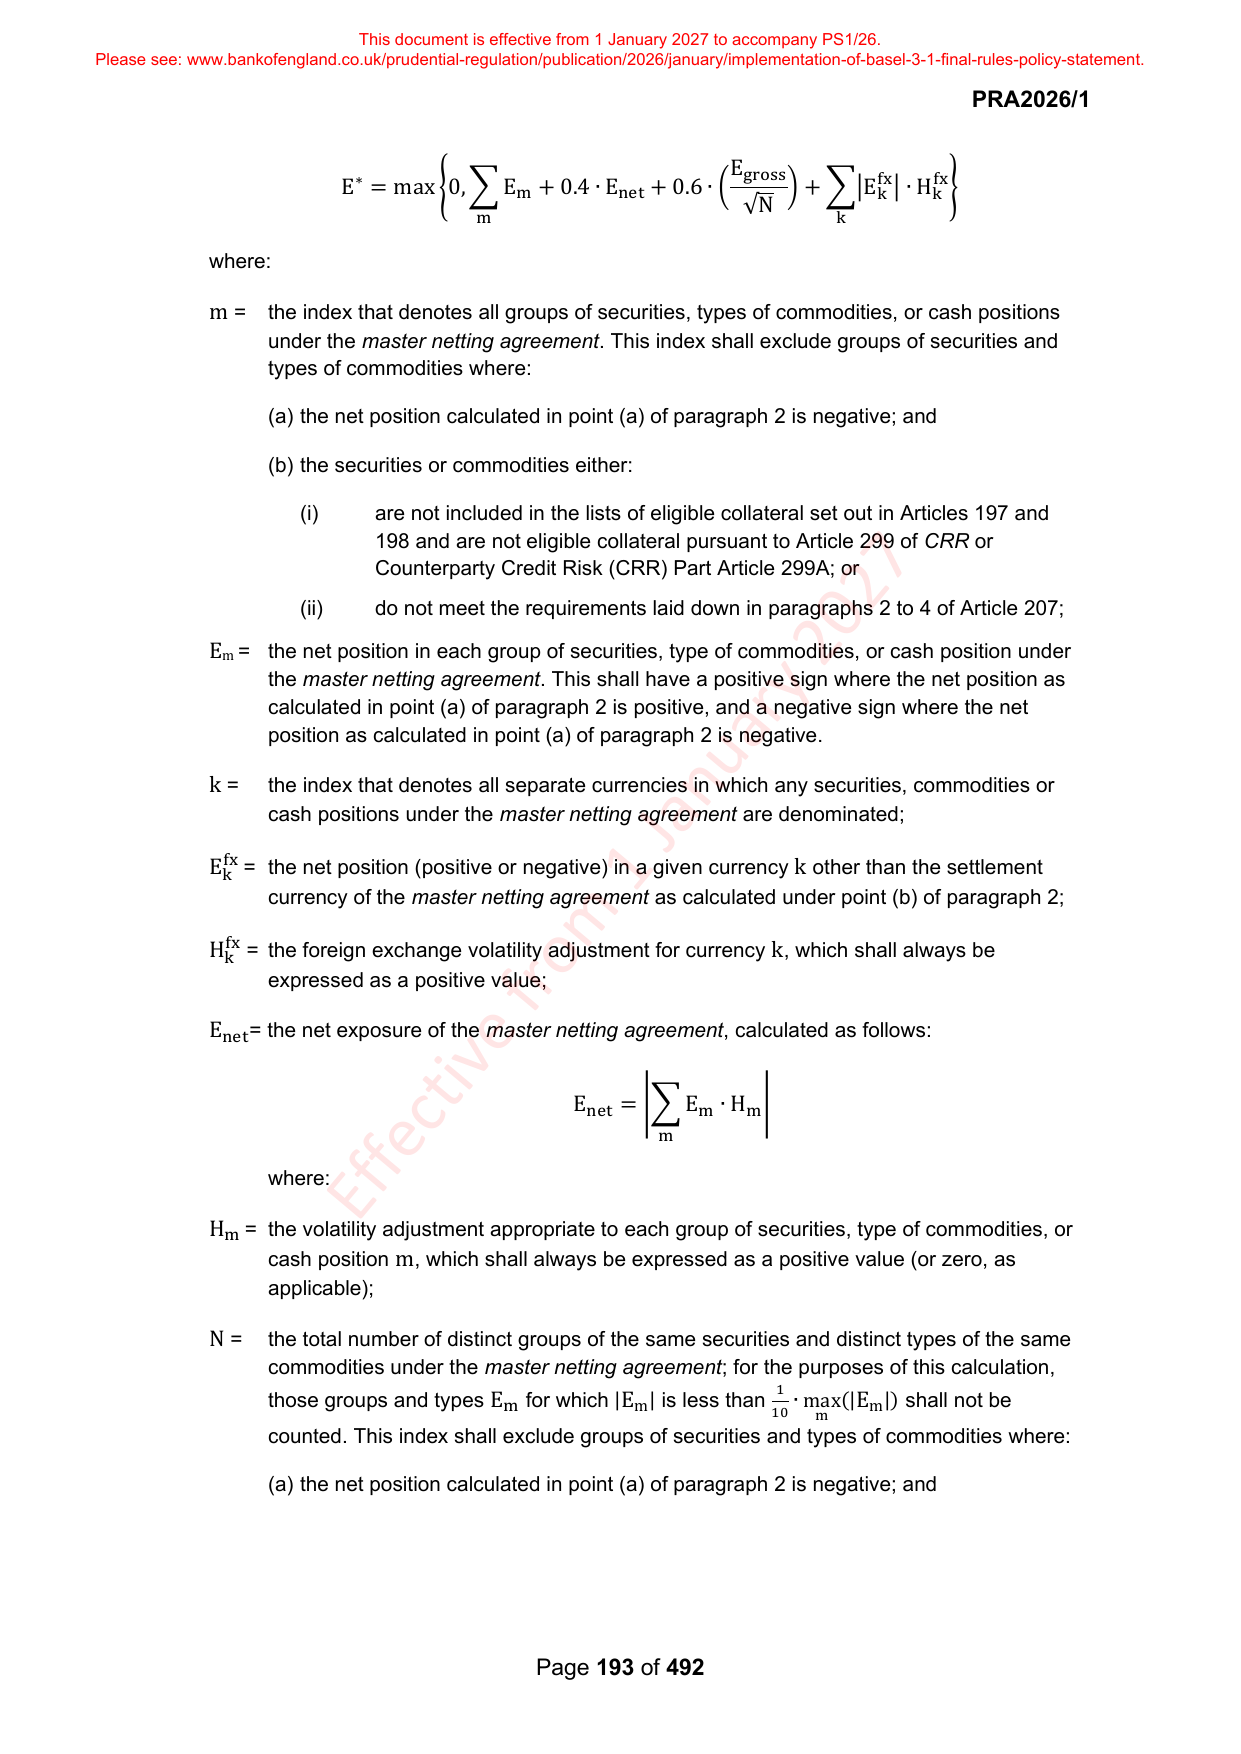
9943 E gross
9944 ∗
9945 E = max {0, ∑ E m + 0.4 ∙ E net + 0.6 ∙ ( ) + ∑|E kfx | ∙ H kfx }
9946 √N
9947 m k
9949 where:
9951 m = the index that denotes all groups of securities, types of commodities, or cash positions
9952 under the master netting agreement. This index shall exclude groups of securities and
9953 types of commodities where:
9955 (a) the net position calculated in point (a) of paragraph 2 is negative; and
9957 (b) the securities or commodities either:
9959 (i) are not included in the lists of eligible collateral set out in Articles 197 and
9960 198 and are not eligible collateral pursuant to Article 299 of CRR or
9961 Counterparty Credit Risk (CRR) Part Article 299A; or
9962 (ii) do not meet the requirements laid down in paragraphs 2 to 4 of Article 207;
9964 E m = the net position in each group of securities, type of commodities, or cash position under
9965 the master netting agreement. This shall have a positive sign where the net position as
9966 calculated in point (a) of paragraph 2 is positive, and a negative sign where the net
9967 position as calculated in point (a) of paragraph 2 is negative.
9969 k = the index that denotes all separate currencies in which any securities, commodities or
9970 cash positions under the master netting agreement are denominated;
9972 E kfx = the net position (positive or negative) in a given currency k other than the settlement
9973 currency of the master netting agreement as calculated under point (b) of paragraph 2;
9975 H kfx = the foreign exchange volatility adjustment for currency k , which shall always be
9976 expressed as a positive value;
9978 E net = the net exposure of the master netting agreement, calculated as follows:
9980 E net = |∑ E m ∙ H m |
9981 m
9983 where:
9985 H m = the volatility adjustment appropriate to each group of securities, type of commodities, or
9986 cash position m , which shall always be expressed as a positive value (or zero, as
9987 applicable);
9989 N = the total number of distinct groups of the same securities and distinct types of the same
9990 commodities under the master netting agreement; for the purposes of this calculation,
9991 1
9992 those groups and types E m for which | E m | is less than ∙ max (| E m |) shall not be
9993 10 m
9994 counted. This index shall exclude groups of securities and types of commodities where:
9996 (a) the net position calculated in point (a) of paragraph 2 is negative; and
9998 Page 193 of 492