7363 This document is effective from 1 January 2027 to accompany PS1/26.
7364Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
7365 PRA2026/1
7367 Appendix 1 – SLOTTING APPROACH CRITERIA
7368 (for Article 153, paragraph 5)
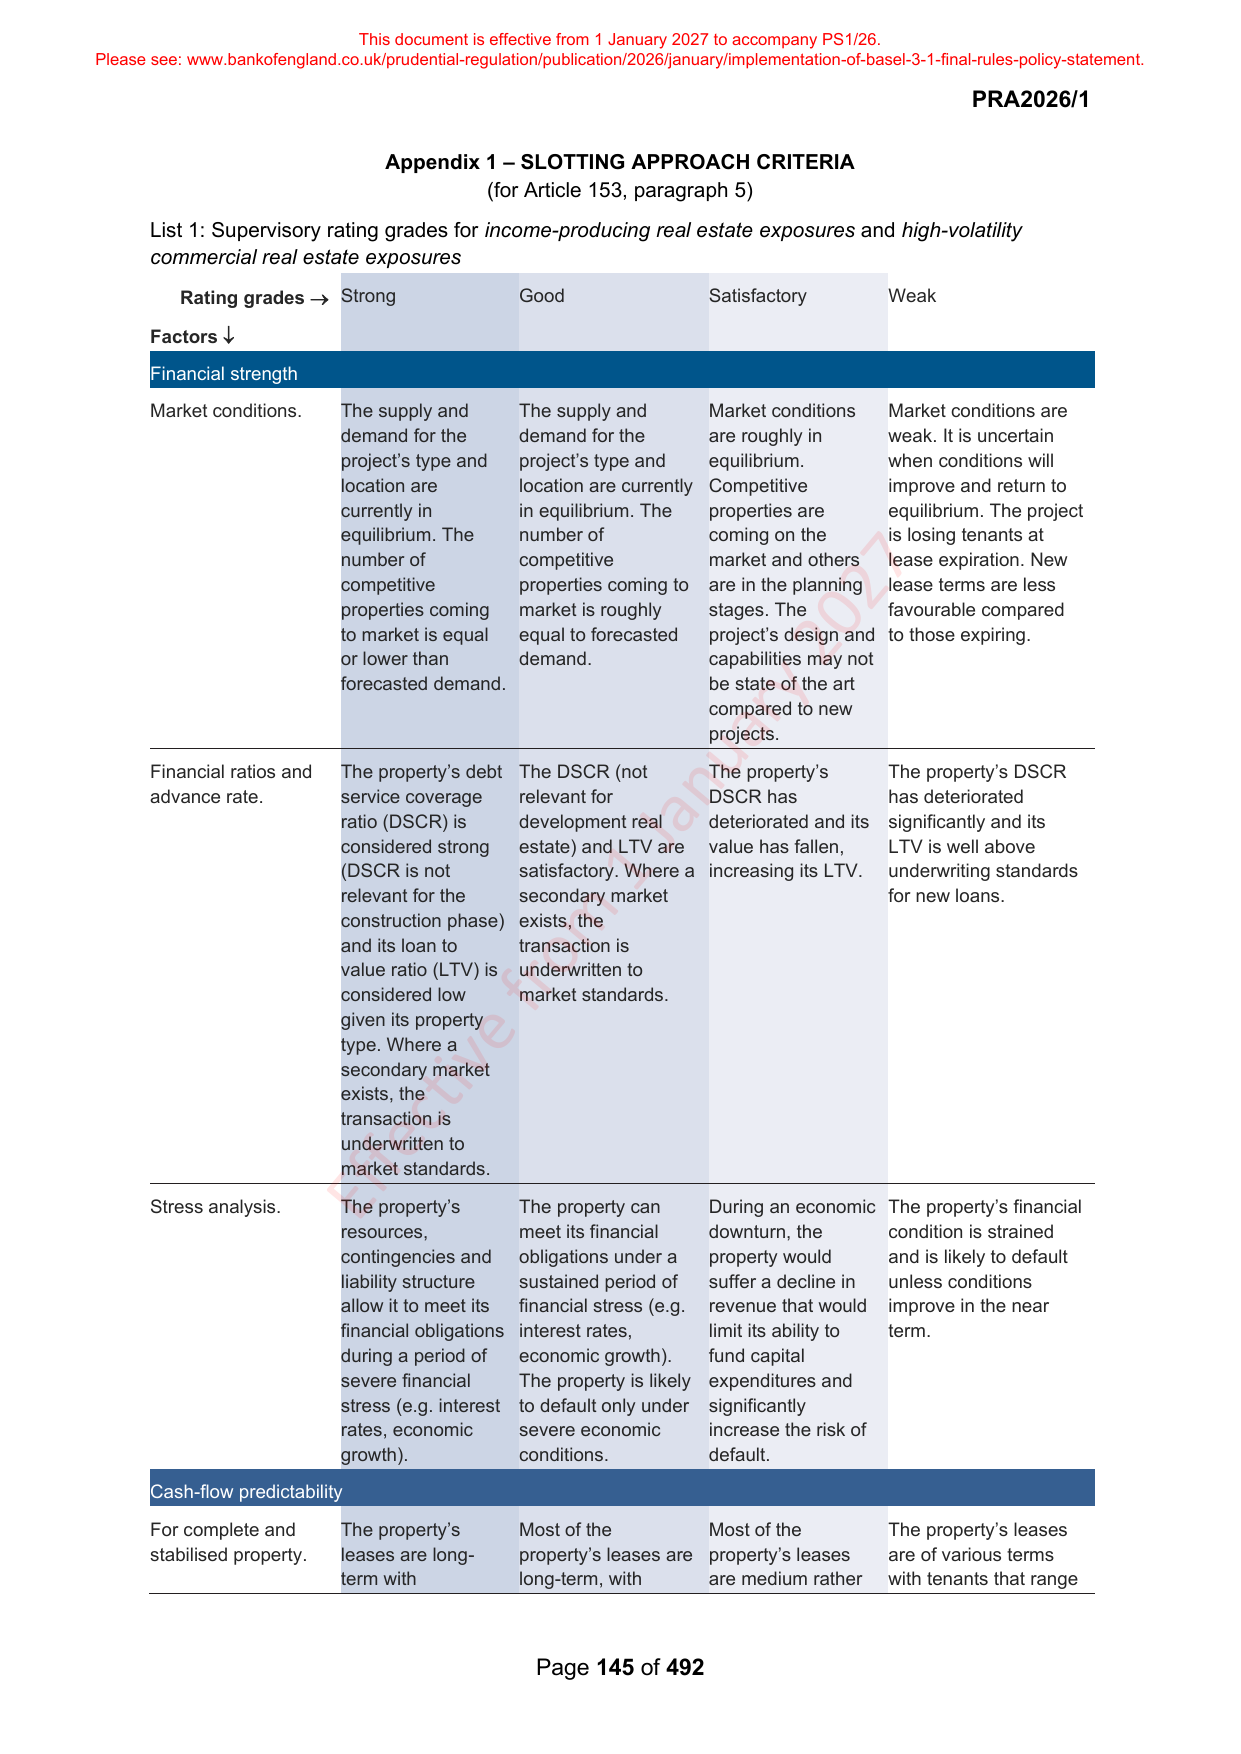
7369 List 1: Supervisory rating grades for income-producing real estate exposures and high-volatility
7370 commercial real estate exposures
7371 Rating grades → Strong Good Satisfactory Weak
7373 Factors
7374 Financial strength
7375 Market conditions. The supply and The supply and Market conditions Market conditions are
7376 demand for the demand for the are roughly in weak. It is uncertain
7377 project’s type and project’s type and equilibrium. when conditions will
7378 location are location are currently Competitive improve and return to
7379 currently in in equilibrium. The properties are equilibrium. The project
7380 equilibrium. The number of coming on the is losing tenants at
7381 number of competitive market and others lease expiration. New
7382 competitive properties coming to are in the planning lease terms are less
7383 properties coming market is roughly stages. The favourable compared
7384 to market is equal equal to forecasted project’s design and to those expiring.
7385 or lower than demand. capabilities may not
7386 forecasted demand. be state of the art
7387 compared to new
7388 projects.
7390 Financial ratios and The property’s debt The DSCR (not The property’s The property’s DSCR
7391 advance rate. service coverage relevant for DSCR has has deteriorated
7392 ratio (DSCR) is development real deteriorated and its significantly and its
7393 considered strong estate) and LTV are value has fallen, LTV is well above
7394 (DSCR is not satisfactory. Where a increasing its LTV. underwriting standards
7395 relevant for the secondary market for new loans.
7396 construction phase) exists, the
7397 and its loan to transaction is
7398 value ratio (LTV) is underwritten to
7399 considered low market standards.
7400 given its property
7401 type. Where a
7402 secondary market
7403 exists, the
7404 transaction is
7405 underwritten to
7406 market standards.
7408 Stress analysis. The property’s The property can During an economic The property’s financial
7409 resources, meet its financial downturn, the condition is strained
7410 contingencies and obligations under a property would and is likely to default
7411 liability structure sustained period of suffer a decline in unless conditions
7412 allow it to meet its financial stress (e.g. revenue that would improve in the near
7413 financial obligations interest rates, limit its ability to term.
7414 during a period of economic growth). fund capital
7415 severe financial The property is likely expenditures and
7416 stress (e.g. interest to default only under significantly
7417 rates, economic severe economic increase the risk of
7418 growth). conditions. default.
7419 Cash-flow predictability
7420 For complete and The property’s Most of the Most of the The property’s leases
7421 stabilised property. leases are long- property’s leases are property’s leases are of various terms
7422 term with long-term, with are medium rather with tenants that range
7424 Page 145 of 492