6158 This document is effective from 1 January 2027 to accompany PS1/26.
6159Please see: www.bankofengland.co.uk/prudential-regulation/publication/2026/january/implementation-of-basel-3-1-final-rules-policy-statement.
6160 PRA2026/1
6162 collateral in its LGD estimates. Collateral recognised by the institution shall be taken into account
6163 in its LGD estimates as follows:
6164 (a) for an exposure where Article 169B does not apply to any collateral recognised by the
6165 institution that secures the exposure, the institution shall:
6166 (i) include the collateral recognised by the institution in its consideration of risk drivers in
6167 accordance with point (b) of Article 170(4); and
6168 (ii) take the collateral recognised by the institution into account when quantifying LGD
6169 estimates;
6170 (b) for an exposure where Article 169B applies to any collateral recognised by the institution that
6171 secures the exposure, the institution shall take the collateral into account in accordance with
6172 that Article.
6173 2. An institution may only use the LGD Modelling Collateral Method referred to in paragraph 1 to the
6174 extent which it has:
6175 (a) established internal requirements for collateral management, operational procedures, legal
6176 certainty and risk management in respect of the types of collateral that it takes into account in
6177 its LGD estimates; and
6178 (b) those internal requirements are generally consistent with those required for the Foundation
6179 Collateral Method.
6180 3. Where an institution has an exposure that is covered by unfunded credit protection that, in turn, is
6181 covered by collateral, the institution uses both the LGD Adjustment Method and the LGD
6182 Modelling Collateral Method in accordance with paragraph 2 of Credit Risk Mitigation (CRR) Part
6183 Article 191A, and Article 169B does not apply to any collateral recognised by the institution that
6184 secures the exposure, the institution may apply the LGD Modelling Collateral Method by reflecting
6185 the effect of collateral by adjusting facility grades or LGD estimates in accordance with Article
6186 183(2A) instead of applying the approach set out in point (a) of paragraph 1.
6187 Article 169B LGD MODELLING COLLATERAL METHOD: LACK OF MODELLING DATA
6189 1. This article applies where an institution applying the LGD Modelling Collateral Method recognises
6190 a particular type of collateral located in a particular jurisdiction that is held against an exposure,
6191 and it does not have sufficient data to model robustly the effect of that particular type of collateral
6192 on recoveries in that particular jurisdiction.
6193 2. Where the condition in paragraph 1 is met, an institution shall calculate own LGD estimates for
6194 the exposure by:
6195 (a) in the case of an exposure secured by a single type of collateral that is recognised by the
6196 institution, applying the formula in Credit Risk Mitigation (CRR) Part Article 230; or
6197 (b) in the case of an exposure secured by multiple types of collateral that is recognised by the
6198 institution, applying the formula in Credit Risk Mitigation (CRR) Part Article 231,
6199 and, in applying these formulae:
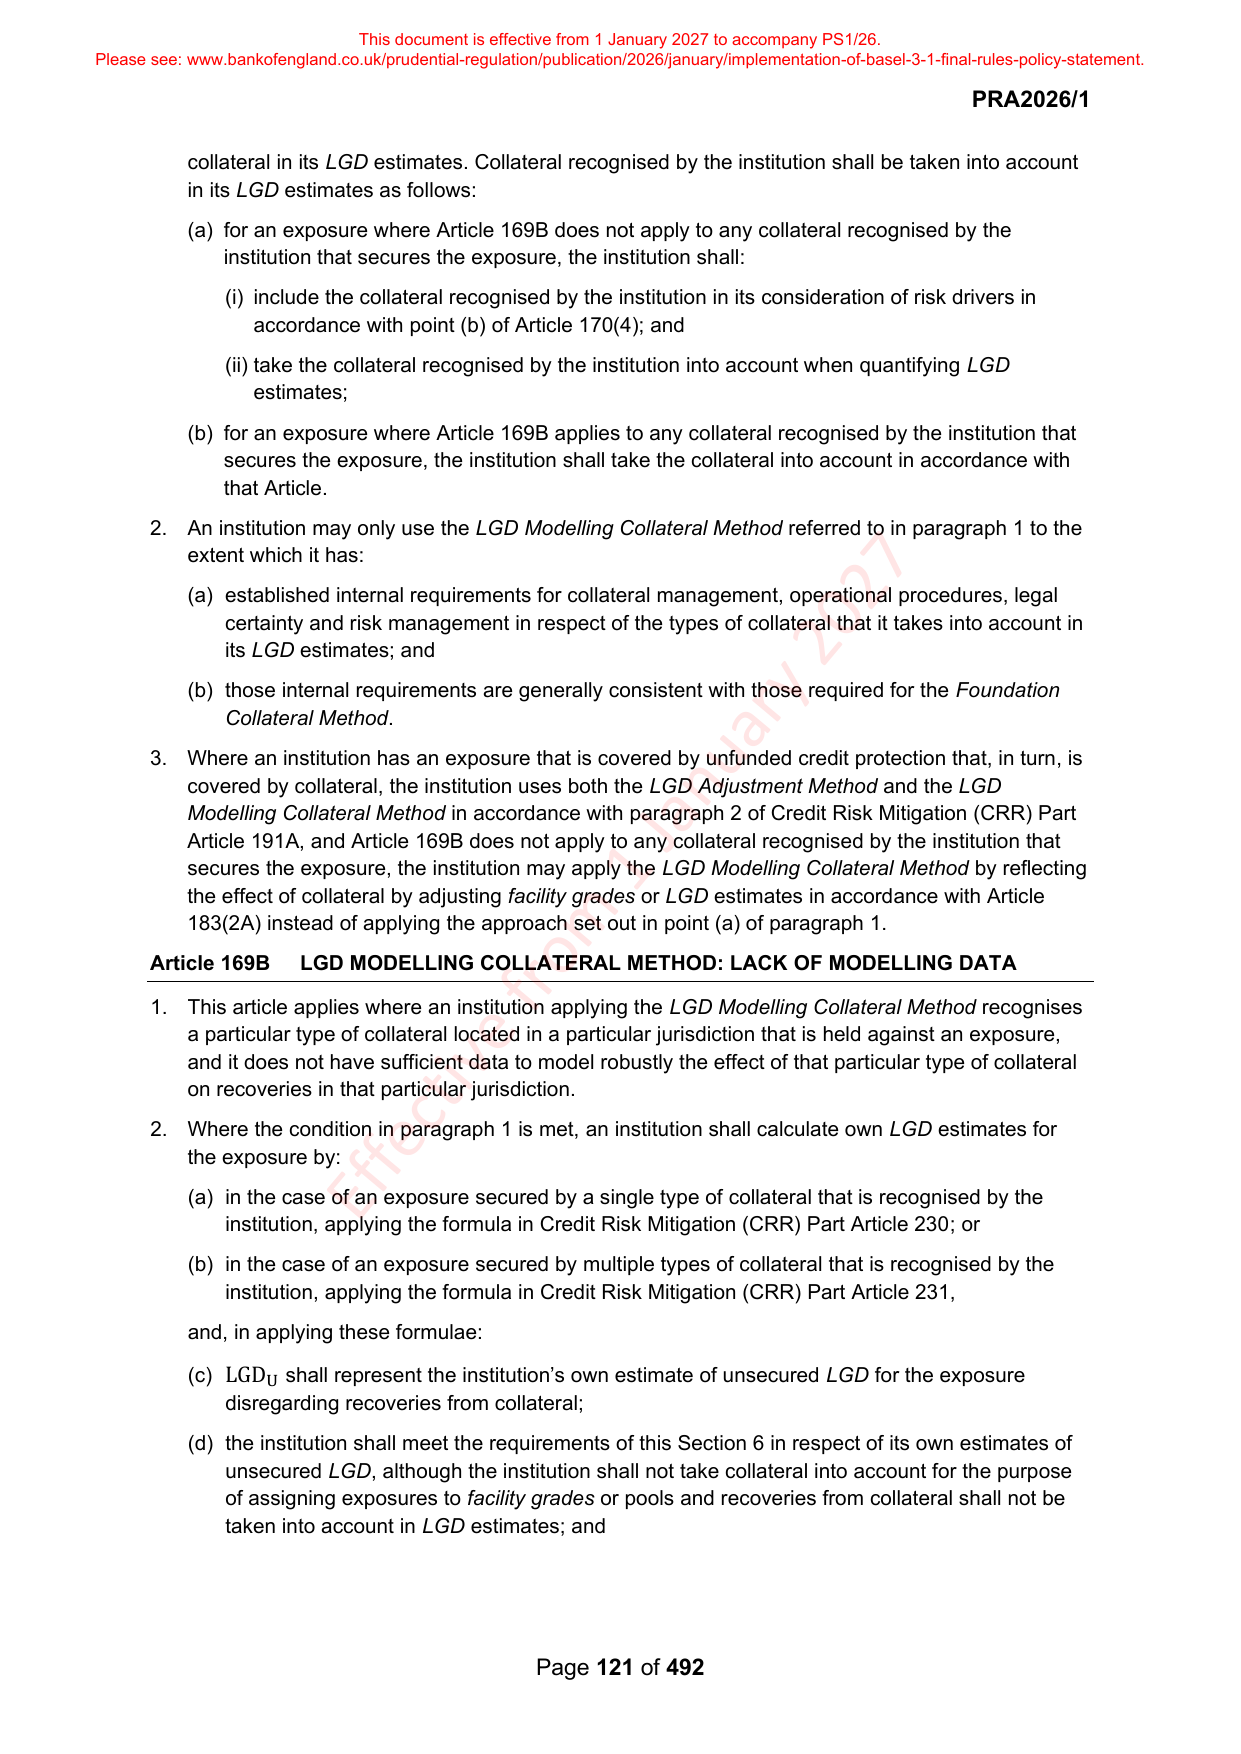
6201 (c) LGD U shall represent the institution’s own estimate of unsecured LGD for the exposure
6202 disregarding recoveries from collateral;
6203 (d) the institution shall meet the requirements of this Section 6 in respect of its own estimates of
6204 unsecured LGD, although the institution shall not take collateral into account for the purpose
6205 of assigning exposures to facility grades or pools and recoveries from collateral shall not be
6206 taken into account in LGD estimates; and
6208 Page 121 of 492